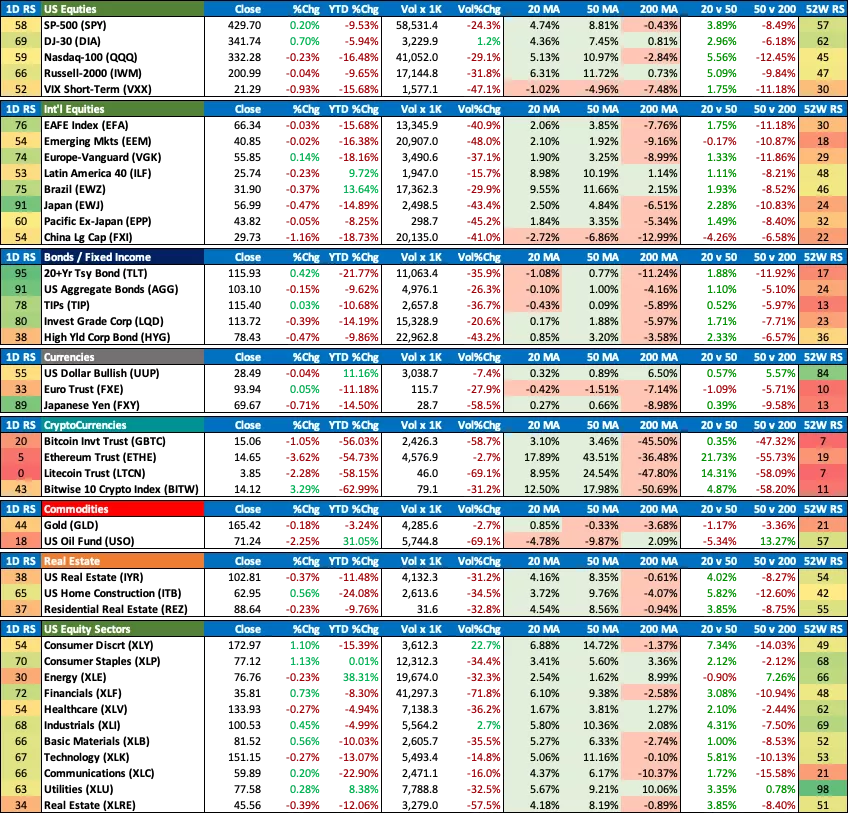
Equity markets encountered mixed trading as investor preferences shifted toward blue chip and value oriented stocks. Consequentially, the Nasdaq-100 and Russell-2000 indexes were unable to participate in today’s upside.
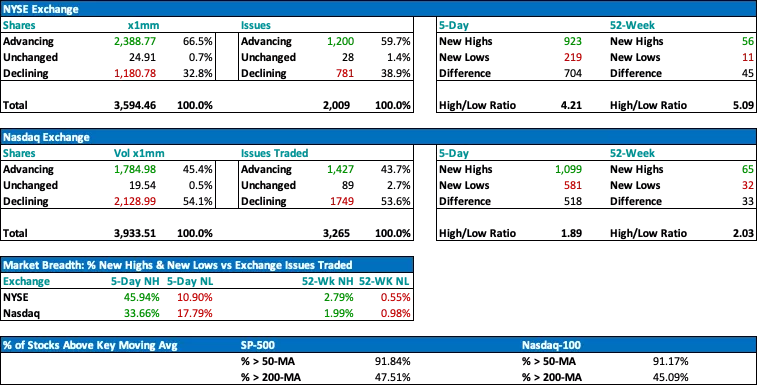
Equity markets encountered mixed trading as investor preferences shifted toward blue chip and value oriented stocks. Consequentially, the Nasdaq-100 and Russell-2000 indexes were unable to participate in today’s upside. Technology stocks stood out as a lagging sector. Although some blame the uptick in the 10-year treasury rates for today’s demise in semiconductor stocks, the truth is that interest rates have been consolidating since the beginning of August-2022 and remain relatively unchanged. What I suspect to be the real culprit is the emergence of a technically overbought market. Fast Stochastics for weekly timeframes on the SPY and QQQ are respectively indicating readings of 91 and 84. Meanwhile the percentage of their underlying components trading above 50-day moving averages is over 90 for both. Simply put, momentum is starting to hit inertia and decelerate. A correction should be forthcoming soon and hopefully without too much damage to the recently established uptrends.
Bullish Events
Economy / Real Estate for Jul-2022
Building Permits @ 1.674m vs estimates @ 1.65m and prior @ 1.696m.
Building Permits (m/m) @ -1.3% vs prior @ 0.1%.
Earnings / Consumer Staples: WMT reported better than expected earnings and increased its full year sales forecast. The news provided bullish support for other retailers, e.g. TGT; ROST; BBY; and COST.
Business Outlook / Consumer Discretionary:
CCL reported a surge in cruise line bookings since pandemic restrictions have been lifted.
HD reported beat earnings estimates on stronger than expected sales and provided positive guidance for Q3-2022.
Neutral Events
Economy / Production for Jul-2022
Industrial Production (m/m) @ 0.6% vs estimates @ 0.3% and prior @ -0.2%.
Industrial Production (y/y) @ 3.9% vs prior @ 4.02%.
Bearish Events
Economy / Real Estate for Jul-2022:
Housing Starts @1.446m vs estimates @ 1.540m and prior @ 1.599m.
Housing Starts (m/m) @ -9.6% vs prior @ 2.4%.
Commodities / Energy: API Weekly Crude Stocks @ -0.448m vs estimates @ -0.117m and prior @ 2.156m.
Analyst Downgrades / Technology: Citigroup downgraded ZM on concerns for its “sustainable growth”. It faces competition which impacts its customer retention.
Technically Speaking
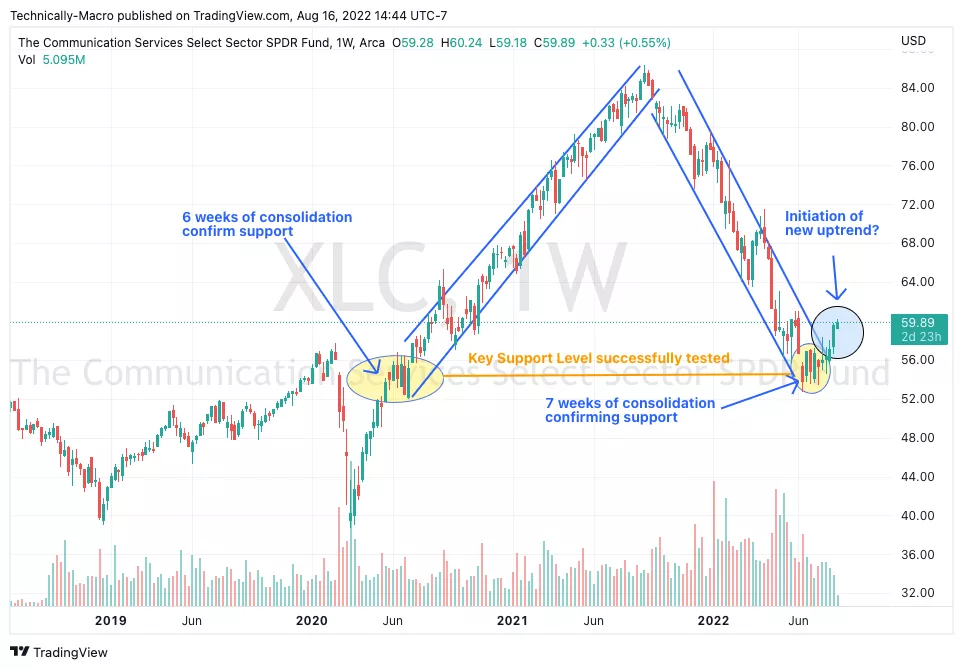
A sector which has caught my eye recently is the SP-500 Communications index, which appears to be initiating a key bullish reversal. It is comprised of 25 components with an aggregate market capitalization @ $3.5trn. 6 of its top 10 components (GOOG; META; DIS; TMU; VZ; T) represent 80% of its total market capitalization @ $2.8tr. Because this is a market-cap weighted index and the above mentioned stocks have either bottomed and initiated new uptrends or are currently trading within a bullish channel with potential for higher upside, the group has a high probability of continuing its advance.
The Communications sector ETF (XLC) is structured to mimic the performance of the SP-500 Communications index and investors might want to consider overweighted allocations. It should be noted that from its Aug-2021 high to its Jun-2022 low, XLC declined -38.93% or ($33.62). I have it pegged to a target price @ $77, which translates into potential profit @ 28%.
Performance: DJ Real Estate Index @ 398.44 (-0.36%); DJ Home Construction @ 1284.08 (+0.18%)
Comments: n/a
Daily ETF Performance Monitor
Market Diary
Earnings
Sector
Positive Surprise
Meeting Expectations
Negative Surprise
Consumer Discretionary
HD
Consumer Staples
WMT
Healthcare
A
*Earnings reported After-market hours
Market SWOT Analysis
Strengths (happening now)
Weaknesses (happening now)
Energy Production Capacity Growing: Decline in WTI Crude Oil rapidly accelerating and the mantra that higher prices correct higher prices is being realized. Even more significant is the contraction in RBOB Gasoline futures, which ultimately translates into relief at the gas pumps for American consumers.
Strong Employment Situation: The July-2022 employment report indicated an 528k increase of new jobs vs June-2022’s already robust gain of 398k. The unemployment rate is ticked lower to 3.5% vs prior @ 3.6%. It’s a tight labor market and therefore wage inflation should be expected. However, it the Fed is able to reign in high fuel and food prices by raising rates, then this creates a situation for a strong recovery in consumer activity.
Cryptocurrencies: Bitcoin and Ethereum are proxies or investor sentiment toward risk and appear to have found support and are initiating new uptrends. If so, this could have bullish implications for equity markets.
Untamed Inflation: Consumer prices (CPI data), which are closely monitored by the Fed, have been trending above 8%+ with potential for double digit inflation. The June-2022 report to be released in July-2022 could trigger more aggressive rate hikes.
Geopolitical Risk in Greater China: House Speaker Nancy Pelosi’s visit to Taiwan has clearly upset China and emboldened it to step up its military exercises and threaten invasion of the the island. The risk of confrontation with the U.S. must be balanced and taken into consideration.
Continued Disruptions in China Supply Chain: Covid infection rates in are increasing and prompting Chinese officials to once again shut down its economy, thus exacerbating supply chain bottlenecks.
Opportunities (could happen)
Threats (could happen)
Lower Energy Prices: The Federal Reserve’s resolve to combat inflation with aggressive rate hikes will have the collateral effect of creating a stronger dollar and, if a soft landing is achieved, a mild recession will contribute to demand destruction for energy and lower prices for consumers. A decline in energy prices could reignite consumer demand and confidence, especially if the labor market remains stable.
Cutting a deal with Iran: The U.S. and Iran are currently negotiating to end sanctions and bring Iranian oil back online if certain parameters for nuclear testing and development can be accomplished. If so, this would immediately alleviate any supply imbalance in the energy markets as Iran has the capability to restart production almost immediately. A successful outcome for these negotiations could happen instantaneously and presents a legitimate risk for anyone committed to long exposure to crude oil futures or the actual product itself.
EU negotiations with Iran: More than 15 months have been invested between the U.S. and Iran to revive the 2015 nuclear deal. It is reported that EU officials have submitted a final text for Tehran to sign. In the event this actually happens, it would have the same aforementioned bearish implications for Oil prices.
EU Winter Energy Supply: Russia could weaponize its energy supplies to EU countries for the upcoming winter in response to sanctions imposed against it as well as the military and financial aid it is providing Ukraine to thwart its invasion. If so, energy prices could explode higher.
Analysts’ Downgrades and Revisions: As the Fed continues to tighten, another wave of negative earnings revisions would require recalibration of equity market valuations.
Global Food Inflation and Famine: Russia vs Ukraine conflict has the potential to destabilize food supplies and create a domino effect of food inflation and famine in LDCs as well as more developed countries.
Mid-term elections: The outcome of the upcoming election in November is uncertain and given the divided state of the US, it could bring about more uncertainty and exacerbate the gridlock for which Washington DC is notorious.
This report is not distributed for the purpose of providing individualized market advice. The information published in it regards securities in which it is believed that readers may have interest and this report only reflects sincere opinions on the investment markets and events or news impacting them. Nevertheless, this report is not intended to be personalized recommendations to buy, hold, or sell securities. Investments in the securities markets, and especially in options or futures, are speculative and involve substantial risk. Each individual investor should determine their respective appropriate level of risk. It is recommended that you seek personal advice from your professional investment advisor and conduct further independent due diligence research before acting on any information published in this report. Most of the content contained herein is derived directly from information published by the companies mentioned in this report and/or from other sources deemed to be reliable, but without independent verification of such. Therefore, no assurance of the completeness or accuracy of information contained within is guaranteed and in no manner warrants or guarantees the success of any action which you take in reliance on its statements and opinions.
Disclaimer:This and other personal blog posts are not reviewed, monitored or endorsed by
TalkMarkets. The content is solely the view of the author and TalkMarkets is not
responsible for the content of this post in any way. Our curated content which is
handpicked by our editorial team may be viewed here.

Comments
Log in or sign up to join the conversation.