
For the last two years, I have been writing about the promise of Artificial Intelligence, noting the extraordinary, unbelievable, galactic-sized capital investments needed to move this new technology forward. And while I am a believer in the impact of AI, I have been steadfast in maintaining that not every hyper-scaler is going to be successful and profitable. We just don’t know which ones yet. The cash flow return numbers we see from the AI companies in their investment presentations as they seek literally hundreds of billions of dollars of financing are possible for any one given company, but they are not possible in the aggregate. There will be losers.
At some point, the market is going to realize that those outsized investments have to have outsized returns in order to be able to justify them. From time to time, we see some analysis that agrees with that thesis, but just like the hyper-scalers in their presentations, there are a lot of assumptions that make the analysis interesting but not particularly useful.
Until now. The last week has seen a number of different analysts talking about what are clearly cracks in the AI fundament. For those of us with a few gray hairs, we can remember the same scenario in the late 90s as a slow trickle of question marks around the viability of some of the dot-com era companies became a flood and then we had a crash. Eyeballs and clicks were not cash flow. The demand for Cisco (CSCO) routers was not infinite even though the stock suggested that it would be. Cisco took 20 years to recover pricewise after its stock crashed, even as revenues and profits kept increasing. The stock got ahead of itself simply on enthusiasm.
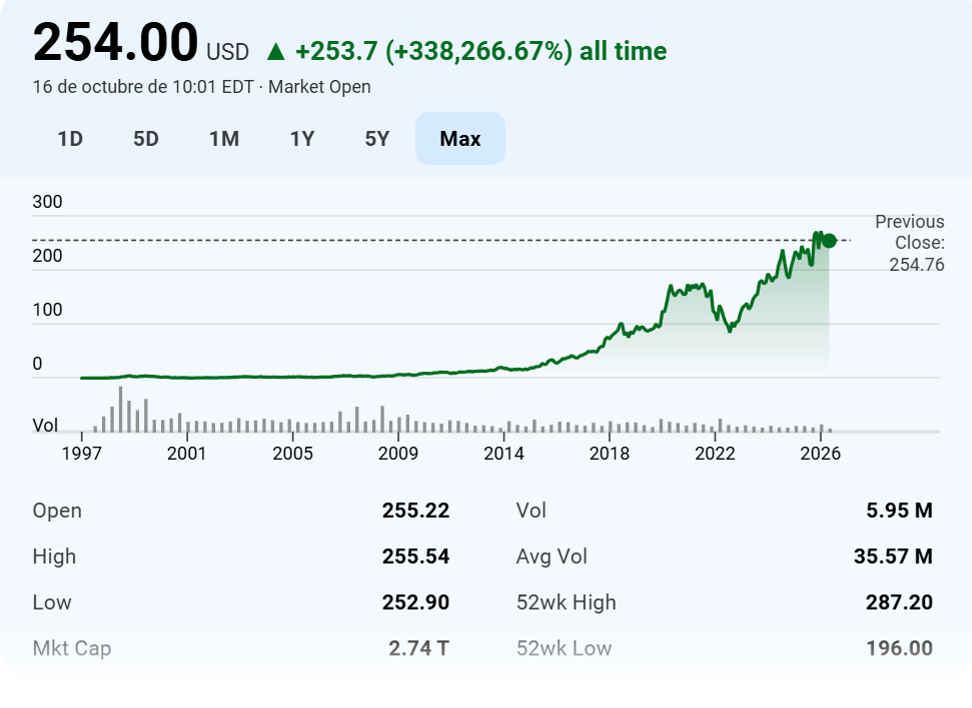
I should point out that the original point the market and investors of that era were making was that the Internet was going to be this powerful economy-changing tool. And in fact, the Internet changed things far more than even most of the most enthusiastic proponents believed. I remember being skeptical of Amazon (AMZN) in the early 2000s. I was clearly wrong, but it took the stock price a little while to demonstrate the potential growth. And nobody was talking about a company that would be worth $2.7 trillion in 25 years.
Source: LSEG
So today, we are going to look at some of the cracks which are becoming visible in the AI space. It will change the nature of index investing, the economy and portfolio management for the next decade. And generally, not in a good way as far as current AI investors are concerned. And if you are an index investor, then you are perforce an AI investor, because the mainstream indexes are 34% or more AI.
I am not saying that AI is not possibly the most impactful technology in a history that includes steam engines, railroads, electricity, and the Internet. And I do believe that there will be companies in 25 years that will see a 300,000% increase. We just don’t know which ones, and it wouldn’t surprise me for it to be a new startup company that is not yet on our collective radar.
Quickly, at the end of this letter I will be talking about something far more important, and that is your health. We are doing a free health and longevity symposium next Saturday with some of the all-stars of the cutting edge of the biotechnology future. Details below. And now let’s look at AI.
Where’s the AI Cash Flow?
In the latest quarter, Anthropic reported revenue of $16.8 billion, marking a 45% increase from the previous quarter. The company is also profitable on an adjusted basis and has reached $518 billion in computing commitments. Anthropic is preparing for a potential $2 trillion IPO, with expectations of a valuation well above $1 trillion. (Note that I currently use Claude as my go-to AI, so I’m not picking on them.)
Let’s give Anthropic the benefit of the doubt and assume that the revenues grow to $100 billion a year by the end of the year. That puts their cash-to-revenue valuation anywhere from 10 to 20 times actual sales. Not profit, revenues. You will see similar numbers from all the pure hyper-scalers.
But underneath the astounding growth of the various AI companies is a great deal of debt and leverage, plus a massive need for even more debt and leverage. Let’s take Oracle (ORCL), as it is one of the current problem children.
First of all, capital expenditures (capex) were $55.6 billion for their fiscal 2026. Its free cash flow dropped to a negative $24 billion. They are projecting $70 billion in total capex for 2026. The stock is in freefall, down over 55%, erasing almost $500 billion in market cap. (Not that we will feel sorry for him, as he is still a multibillionaire, but Larry Ellison did lose over $200 billion in net worth.)
But that’s not the issue. Oracle is a big company with an ongoing profitable business. The company can stand a hit or two, even though the company is projecting to remain cash flow negative through 2030. Why? The problem is that Oracle has $630 billion in Remaining Performance Obligations, half of which is from one company, Open AI, whose IPO is already slipping into (maybe) 2027 and must raise hundreds of billions of dollars simply to meet its commitments and stay viable in the AI arms race. And while revenues are rising, they are a long way from positive cash flow that can justify hundreds of billions of investments.
They are currently running $50 billion (their estimate as of October) in annual revenue. New money will theoretically be raised at a valuation of $1.4 trillion. Their last round raised $110 billion from Softbank (SFTBY) at a post-money valuation of $840 billion. I assume they will get an investment basically the same size or larger. That means the total invested capital will be over $250 billion. To get even a 12% return on that amount requires $30 billion in profits.
Oracle is one-third of the now infamous Stargate triumvirate, the ultimate symbol of the AI bubble. The project was unveiled at the White House in January 2025, and the roles were clear-cut: OpenAI is the customer that consumes the compute; SoftBank is the money partner; Oracle is the builder and tenant, turning desert, concrete, and Nvidia (NVDA) chips into working data centers. And while this is only one problematic AI project, incestuous funding in the AI world suggests that it is not the only one. The old rule? There is never just one cockroach.
Let’s look at analysis from a researcher on the platform Medium who hosts insightful documents under the name srgg6701.
“Oracle has to build and equip the data centers and sign multiyear leases — all years before the first dollar from OpenAI shows up. It doesn’t have the cash for that. In July, Oracle raised its fiscal 2027 capex forecast from $60 billion to $90–95 billion. S&P redid its math: this year’s free cash flow shortfall will hit nearly $42 billion (up from the $24 billion it expected before). The gap is being filled with debt. The company’s loans and bonds have already reached $125 billion. On July 9, 2026, S&P cut Oracle’s credit rating to BBB. That’s one notch above junk. But that’s just the tip of the iceberg.”
“…Under accounting rules, a lease on a data center that isn’t up and running yet doesn’t show up on the balance sheet as a liability. It lives in the footnotes. For Oracle, those “footnotes” have already piled up to $288 billion (1, 2). That’s more than twice its entire official debt. It’s worth pausing here to see how this works. Oracle doesn’t own these buildings. Developers build them through special purpose vehicles (SPVs) that borrow against a specific project. And what are the banks lending against? Oracle’s lease. A building is worth exactly what a tenant is willing to pay for it. Oracle’s promise to pay rent is essentially the only guarantee holding the whole thing together.
“…Project Jupiter -- Now let’s get to where the implosion actually starts. Project Jupiter is Stargate’s flagship campus. Yet another monster growing inside the AI bubble. Its capacity is about 2.5 GW, with planned investment of $165 billion. It’s owned by Stack Infrastructure (part of Capital) together with BorderPlex Digital Assets. Blue Owl Construction (OWL) is financed by an $18 billion loan from a syndicate of about 20 banks, including Sumitomo Mitsui (SMFG), BNP Paribas (BNPQY), Goldman Sachs (GS), and MUFG.
“And remember: Oracle is the anchor tenant, reselling that capacity to OpenAI. For this whole layered scheme to work, the campus needs as much power as a major city — think Los Angeles. Hooking into the existing grid turned out to be a problem. The workaround: generate power on site with fuel cells running on natural gas. The gas is supposed to come through a new pipeline spur that still has to be built. Most of the route crosses federal land, but about half a mile runs across state land.
“And that’s exactly where everything got stuck: on March 31, 2026, the New Mexico State Land Office denied the right-of-way, and on July 16 it rejected the second application. The pipeline, originally due to go online in August 2026, has been pushed back to February 2027. On top of that, the air permit for the entire power system still hasn’t been issued: the state Environment Department’s decision isn’t expected before November 23. Meanwhile, local opposition keeps gaining ground — as does the nationwide movement against hyperscale data centers.
“And then, on September 24, 2026, Oracle sent Blue Owl a force majeure notice. In it, Oracle states that it reserves the right to delay switching to full rent by up to three years if the campus isn’t up and running by 2028. Instead, it would keep paying the lower “development stage” rate. Force majeure is a legal move with real consequences for the other side. Here, Oracle is admitting that its flagship project may not make its deadline. The fallout could be dramatic. Every previous warning about the AI bubble came from analysts, short sellers, and critics. This is the first one coming from inside the chain itself. And the market reacted accordingly: investors started dumping Oracle’s 30-year bonds (maturing in 2056), and their price dropped; the cost of insuring against the company’s default (CDS) hit a record high.”
Let’s look at CoreWeave (CRWV). It runs 51 data centers throughout the country, many of which focus on providing services to AI companies. It has $35 billion in debt and interest rate costs of $640 million in the last quarter alone. The market now wants 11% just to insure its debt over five years. The CEO is complaining that he needs an investment-grade rating so that they can borrow “unlimited” (the company’s term) money to finance its obligations.
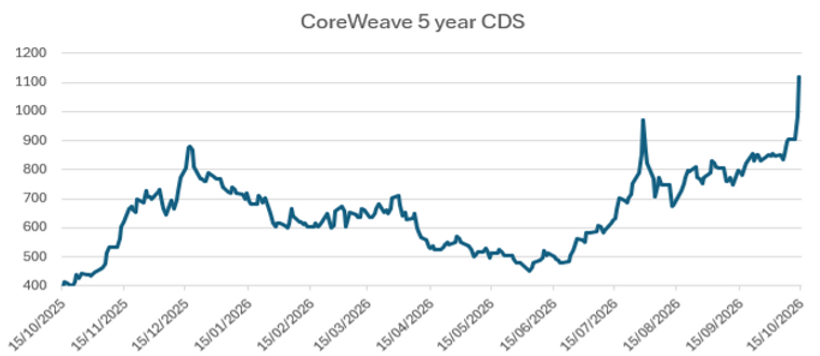
Let’s be clear. There is a demand for these data centers. And that demand is growing. But it doesn’t seem to be generating any profits net of debt costs as of yet.
AI in the Future
Global Crossing (for those of us who remember) was clearly correct in their forecast of the enormous demand for global Internet fiber. And they built it. But the demand was in the future and much of that fiber network went dark. In the bankruptcy, prices dropped and the demand showed up, just later than the optimistic forecasts projected.
I think AI is going to be like that. The demand is going to be huge. But not tomorrow, and the current construction and investment boom is built around tomorrow, not the next decade. The pricing of various AI companies is currently based on all that demand showing up “tomorrow.” Or in the next year or two. It will disappoint investors.
The examples above are just two of many. And while we can point to Oracle and CoreWeave, and perhaps Open AI, there is more under the hood that we don’t know about. At some point, those cracks are going to expand and the markets will react. Many of the AI stocks dropped over 30% this summer. They are now back to close to their highs. Investors saw that dip as a buying opportunity. And they might see the next one in the same way. But at some point, the hype has to live up to the cash flow reality.
Here’s what I expect to happen. The numbers for a few hyper-scalers at some point will show a clear stumble. At some point, investors throw the baby out with the bathwater. Currently, 48% of the S&P 500 is below their 200-day moving average. A large proportion of the earnings growth in the S&P 500 comes from the magnificent seven stocks, especially Nvidia. Which has a 70% gross profit margin. How sustainable is that over time? Answer: not very. They are not a software company, and they have significant competition coming on their heels. They can still be massive and the market leader for some time, just not with 70% margins.
When, not if, the technology stocks finally succumb to real-world cash and profit analysis, the S&P 500 index is going to take a significant hit. The NASDAQ will take an even larger hit. Yes, it will recover over time, but that will likely take years. The NASDAQ investor might be lucky to see 2% compound returns over the following 10 years from the eventual bottom.
I’m not telling you to get out of the market. I am telling you to seriously consider not being an index investor, but to carefully choose which stocks you want to be in. There are hundreds of companies that have positive cash flow, great prospects and solid management. They just don’t have AI in their name. But in 10 years, they will be winners. Along with a few AI companies that outperform their competitors. We just don’t know which ones yet.
Further, as I am usually early in these calls, the market and AI stocks could continue to go up for some time. But not forever. This is not the time to be a buy-and-hold investor in index funds. It is not the time to be a hero. Structure your portfolio to be steady. We will look back in 10 years and realize that compounding at 10% a year is a big win.
My friend David Bahnsen did a fabulous Dividend Cafe yesterday. He summarized the last week when they met with 29 investment managers. The most interesting part was the rationale behind choosing to fire a longtime (and huge) manager because they were changing their strategy and significantly concentrating their portfolios in AI stocks. This is something you should read at his daily newsletter, Dividend Cafe. And if you are looking for someone to talk to about some of those value stocks I was talking about, you should just ask to talk with one of their representatives. They will also send you David’s latest book on dividend investing, which I think is a must-read.
Is my analysis too pessimistic? I said the same thing in 1999 (in my first book), and by the end of the decade the market had gone nowhere. Literally nowhere. Value stocks based on cash flow and earnings? Solid performance and great returns.
There are more implications to this analysis. It has a significant impact on interest rates, real estate and construction, capital expenditures in other industries, employment… Well, pretty much everything. We will explore these in the next few weeks. Stay tuned…
Comments
Log in or sign up to join the conversation.