
We are buried beneath the weight of information, which is being confused with knowledge; quantity is being confused with abundance and wealth with happiness. - Tom Waits Interview "All Songs Considered", NPR, May 20, 2008.
From my earliest memories, I’ve always been an information junkie. In my early years, I just read and absorbed everything I could. The library was my comfort zone. In my early 30s, I began to focus on economics and financial information, as I was running a financial publishing company. By the early 90s, I was writing on economics and finance; in the late 90s I wrote my first book and launched my second newsletter (the first was a newsletter on gold and gold stocks in the 1980s, which I eventually sold).
I started this letter in August of 2000 as a way to organize my own thoughts and communicate with clients. I stuck it on the Internet for free as an afterthought. It took off far beyond anything I could’ve imagined. I was lucky in that most investment and economic newsletters of that era focused on one topic, and over time there’s only so much you can say about one topic.
I wrote then, as I do now, about whatever I read that week that interests me. And while over the years I tried to focus my letters on one topic, the reality is that sometimes the letter just has to focus on multiple topics and ideas. I write my letter as if I’m writing to friends, which I consider you to be. How many times do you get together with friends and you focus on just one topic? The usual friendly dinner conversation covers lots of topics. This week is a multiple topic letter, but with so much happening, how could it not be?
Quickly, at the end of this letter I will provide a link to a free online health and longevity symposium that we are doing in two weeks with 13 of the best experts in the world on their favorite topics over one day. Economics and wealth are important, but health is everything. I want us to be together for a long time.
When Will We Have Humanoid Robots?
The technology revolution is happening so fast and it seems companies and CEOs compete with each other to breathlessly tell us what is around the corner. And a lot of times, it is. But sometimes, reality is a lot harder. It seems that sometimes CEOs paint rather optimistic visions that make it easier to raise money. And sometimes those visions pan out.
I will admit, I’m a sucker for optimistic visions. I want them to be true. And since generally the people painting these visions, or at least the more important ones, have credentials and are renowned experts in their field, it is easier to believe. But sometimes reality hits.
More than one robotics company is promising humanoid robots in the early to mid-2030s. Before long, you can buy one for the price of a Toyota (TM) and it will do everything in your house or business that you need to do. And so many people, like me, have bought into the vision that it can affect the way we invest and behave. And then a couple things come along that burst the bubble, or at least push the vision off for a decade.
Along with my publishing partners and friends, we launched what we call the Rational Optimist Society. The original author of the book, The Rational Optimist, Matt Ridley, is working with us and is the honorary chairman. This is a labor of love as there is no economic benefit. Our team (mostly Stephen McBride and Dan Steinhart, with the occasional essay by Matt Ridley and other friends) literally travel the earth interviewing mostly startup companies doing amazing things. Cutting-edge manufacturing of hundreds of different products is coming back to the US in a big way, if behind-the-scenes. Many of these products and services will end up driving massive companies and creating whole new industries.
The letter comes out Sunday morning with the occasional update and is one of my favorite reads. This week Stephen McBride interviewed AJ Meyer of Pickle Robot Company. AJ is focused on doing something as simple as creating a robot that will take a box out of a truck and put it into a warehouse. My oldest son works for UPS on their docks. I can tell you they have been trying to figure this out for decades, and they are nowhere close. Amazon (AMZN), Walmart (WMT), all the big warehouse companies are trying to solve this problem. Moving boxes inside the warehouse? That’s already been done.
Getting a robot to pick up a box in a truck and put it on the appropriate palletized place in the warehouse? Or take a box and put it into the truck? Turns out that is a bigger problem than it sounds like.
But wait, we have self-driving cars? To my great surprise, Teslas (TSLA) are navigating Puerto Rican roads (not always easy for humans). How much harder can it be to move a box? It turns out that self-driving cars basically make about two decisions at a time (steering and throttle). AJ’s robots that are trying to move packages have to have 15 controls and some of his competitors use 50. The AI needed for that is still being developed. The fine motor control needed to pick up the box is difficult.
Think about it. A robot walks into a truck and sees a box. How much does the box weigh? How fragile is the container? What’s behind it? How do you keep from crushing the box or having enough force to pick it up? And how do you make sure that it works in sync with every other piece of gear and automated systems so that it doesn’t slow the process down? Which is a bigger problem than you might think.
Meyer then makes a possible case where we might not even need a humanoid robot in our homes. Which kind of burst my bubble.
All that was interesting, but it was one interview. Then literally within a few hours a Wall Street Journal report came across my inbox. It talks about the problem that Walmart is having automating its truck loading and other aspects of warehouse management.
“Many of the nation’s largest retailers are struggling through similar automation transitions as pressure grows to boost sales and ship merchandise to homes faster without spending a fortune on additional workers or facilities. The rapid growth of Amazon, which is ahead of its retail rivals on automation and earlier this year surpassed Walmart to become the largest U.S. company by annual revenue, has dialed up the urgency.
“In many cases, investments in automation are an arms race” between retailers, said Rueben Scriven, senior warehouse automation research manager at market-intelligence firm Interact Analysis. “And then the Amazon effect is the big elephant in the room.”
The WSJ article, by Sarah Nassauer, is a fascinating chronicle of the difficulties of doing something that to outsiders seems simple: completely automating the warehouse. We simply take what we see for granted, but the complexity is far beyond anything I understood. Taken together, these two articles will give you an insight into the problems of robotics and why we may not have Rosie the robot in our home in five or 10 years as some (looking at you Elon) predict. And by the way, I am rooting for Elon and all the others working on this project to succeed. And I am glad that we have them and thousands of their compatriots working to solve hard problems and make our world a better place.
The Biggest Problems We Face Today
Adam Tooze is a history professor at Columbia. He also has a letter on Substack called Chart Book. It has become one of my almost daily reads, because he, like me, is seemingly a random information junkie. He will typically focus on 5 to 6 items, anywhere from fascinating charts to book reviews to essays. I nearly always find something or several somethings of interest. If you subscribe, and I suggest you do, just be aware that he is left leaning (he is a Columbia professor, after all) and that is reflected in some of the choices of his essays. For some of you that is not a problem. There are others who like more purity in their sources. 😊 I am not one of the latter. I can be my own filter, thank you very much.
This week he sent two charts which I will share highlighting what he thinks are the two biggest forces in the macroeconomic space. The first is no surprise. It is the energy issue. We are now down to less than 6 billion barrels of aboveground storage in pipelines, refineries, ships, storage facilities and so on. That is the minimum amount that it takes in the system just to keep the pipelines and refineries operating. The chart is evidently made by J.P. Morgan from various government and industry sources. There are going to be some hard choices in the next month or so as to what we have to ramp back simply due to logistics.
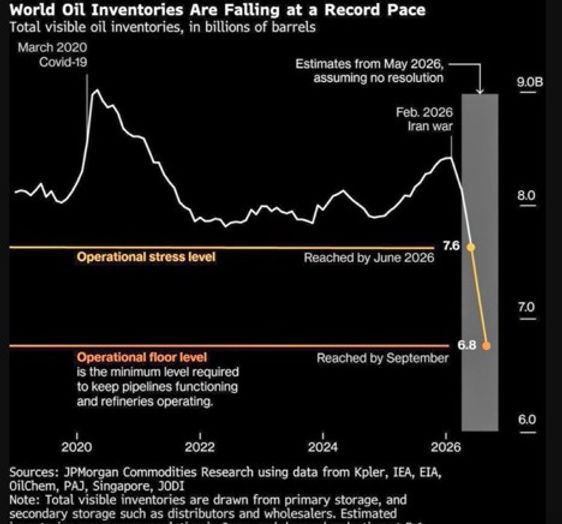
Source: Bloomberg
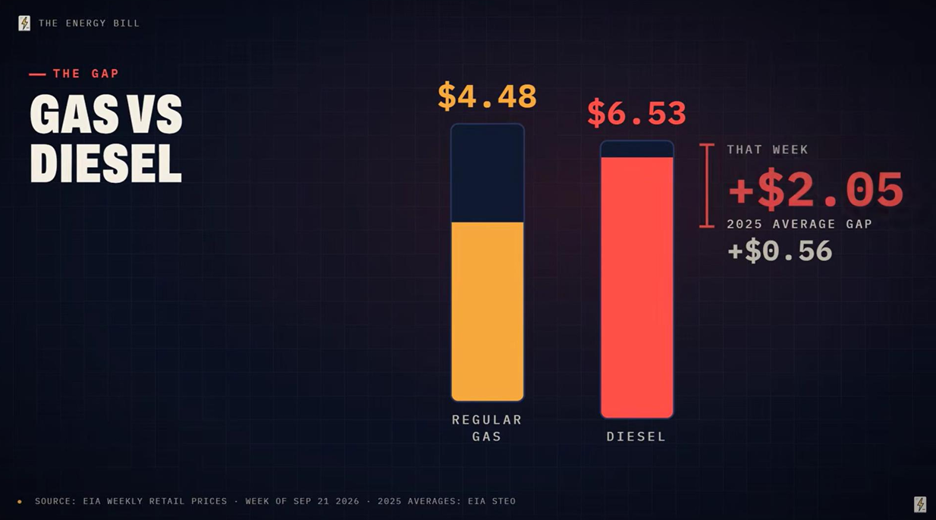
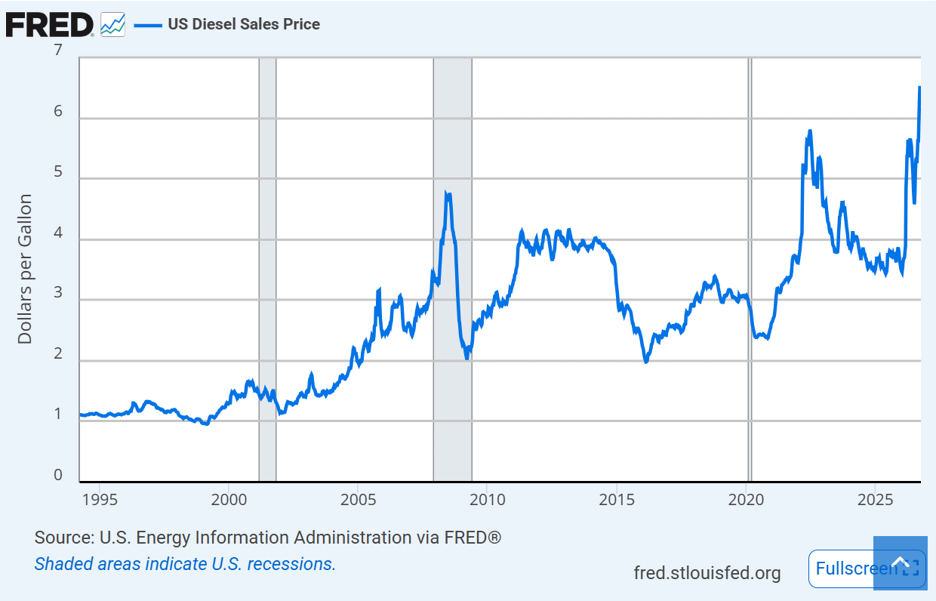
This directly impacts the price of diesel fuel. As we are all aware, diesel has skyrocketed and is now in the $6.38 range. And in my humble opinion, is likely to go much higher.
Source: The Energy Bill
I remember when we would go on vacations from West Texas to Aberdeen, Mississippi. My mother would stop about 2 miles from the Louisiana border so she could buy gasoline at $0.17 a gallon. Gasoline and diesel were relatively cheap. The price jumped up when we crossed the Louisiana border. You can see in the chart below from FRED the price of diesel since 1995, basically up six times. That’s a lot more than inflation.
Source: Federal Reserve Bank of St. Louis
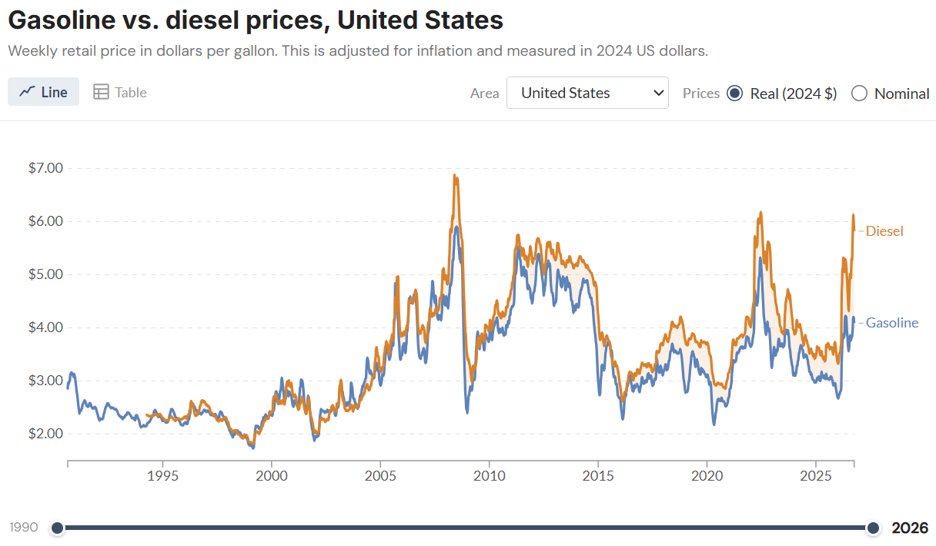
Interestingly, the price of gasoline versus diesel normally moves in tandem. The last two decades, the price of diesel has been modestly above that of gasoline. But this year, the move has been exaggerated because of the problem with refineries around the world going off-line either because they were destroyed (Russia, some of the Middle East) or because of getting refined products out of the Middle East.
Source: US Energy Data
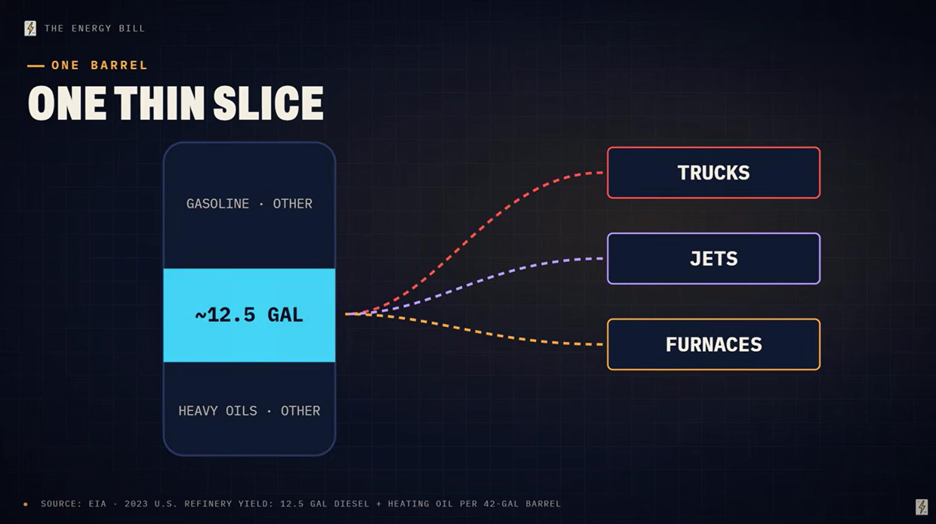
Quick lesson: a barrel of crude oil is “cracked” into various usable components: gasoline, diesel, jet fuel, home heating oil, bunker fuel and so on. Just 25% of that barrel of oil is available to make diesel, jet fuel and home heating oil for furnaces. All of which are necessary. If you reduce the amount of jet fuel being produced in order to create diesel, you create another set of issues for the airline industry. Or for homeowners using heating oil. No good choices.
Source: The Energy Bill
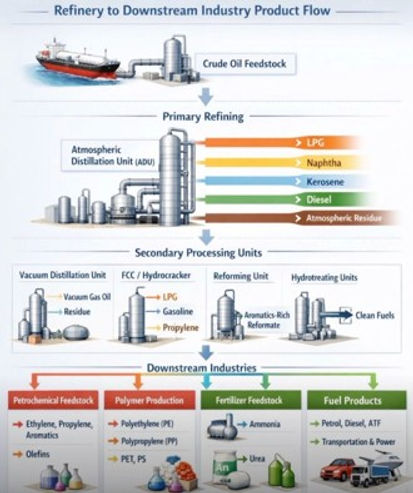
And that barrel of oil doesn’t just make diesel, gasoline or jet fuel. There are literally hundreds of products that we use every day that come from that barrel of oil. Plastics, fertilizer and so on. Just look at this chart and get a small idea of all the products that are made from that barrel of oil. This whole process, and especially the refinery complex, is weighing on everything we buy and use.
Source: Adam Tooze
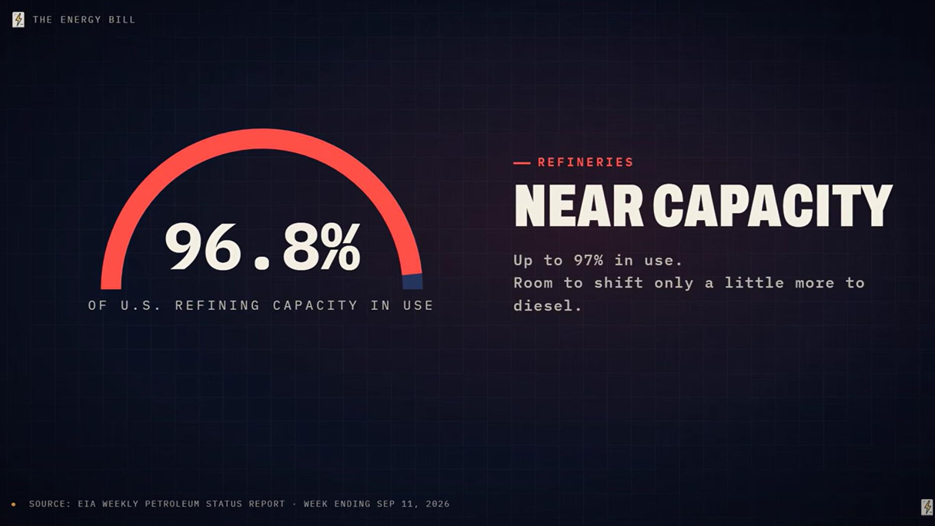
US refiners always had some extra room in their production schedules. Right now, they are running flat out at almost 97% capacity utilization. As is the rest of the world that can manufacture and produce products. We have utilized pretty much every bit of the available production capacity. There is no more. We are going to start having to allocate more of the products by price, which will be inflationary, and increase cost problems for buyers. Governments can come in and try to control things, but that always ends up meaning more shortages in other products and places. I wish I had better news.
Source: The Energy Bill
Interest Rates Spike Everywhere
The second biggest problem? Interest rates in the US 10-year jumped 15 basis points this week in one day. That caused a little whiplash among a few hedge funds and investors. The question was asked to my friends at the Bahnsen Group: "When was the last time that the 10-year Treasury yield increased 15 bps in a single day? That seems dramatic in what should be a very deep market."
Brian Szytel answered with some very interesting facts:
“It happens far more often than you may think. Also, 15bps on a 5% 10YR yield is roughly a 3% move in the rate. To put that in context, the same move in percentage terms would have been just 6bps when the 10YR was at 2% back in early 2022. It's the same idea as a 1,000-point move in the Dow (DIA) being a much bigger deal when the index was at 10K than at 50K.
“For most people, there is a certain 'sticker shock' to the larger absolute number in either case. To give you some numbers, the 10YR has moved by 15bps or more in a single day 34 times in the past 5 years, 14 of them to the upside. To your point, though, a 15bp (or roughly 3%) daily move is still large, about double the average daily move of roughly 1.4% (about 5bps) over that same period.”
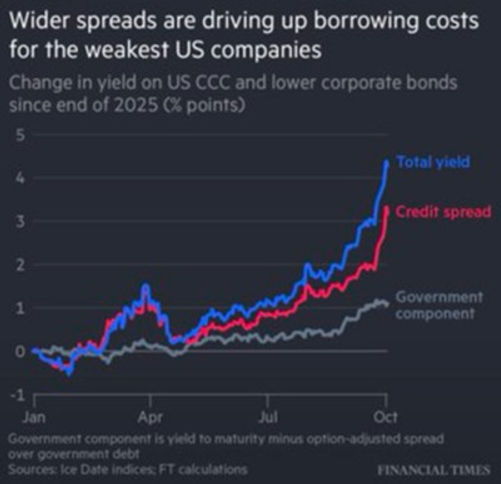
Even more dramatically, credit spreads are widening, which means that companies with more constrained balance sheets or economics are having to pay more for borrowing money. The total yields for triple-C debt are now running around 4% higher than at the beginning of the year. This is having an effect all the way down the curve.
Source: Financial Times
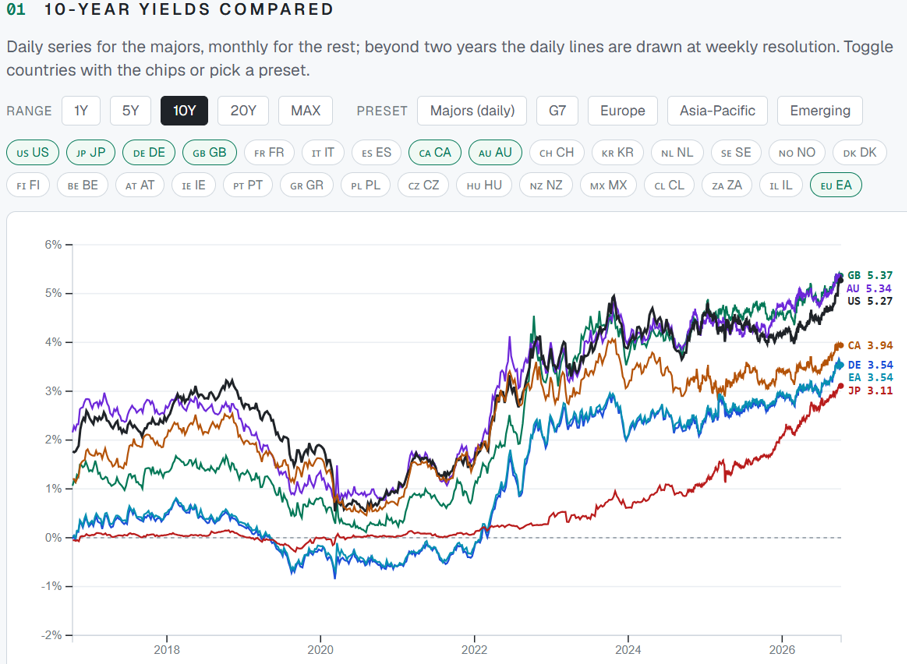
It is not just corporate debt. Government debt has exploded all over the world. The chart below shows the interest rates on 10-year bonds in various countries. They are all rising in tandem. I wrote last week pointing out that some of this can be explained by the slow demise of the Japanese carry trade, as the benefit to investing in, say, French bonds, is not as obvious to the Japanese investor as it was two years ago.
Source: The Trading Tools
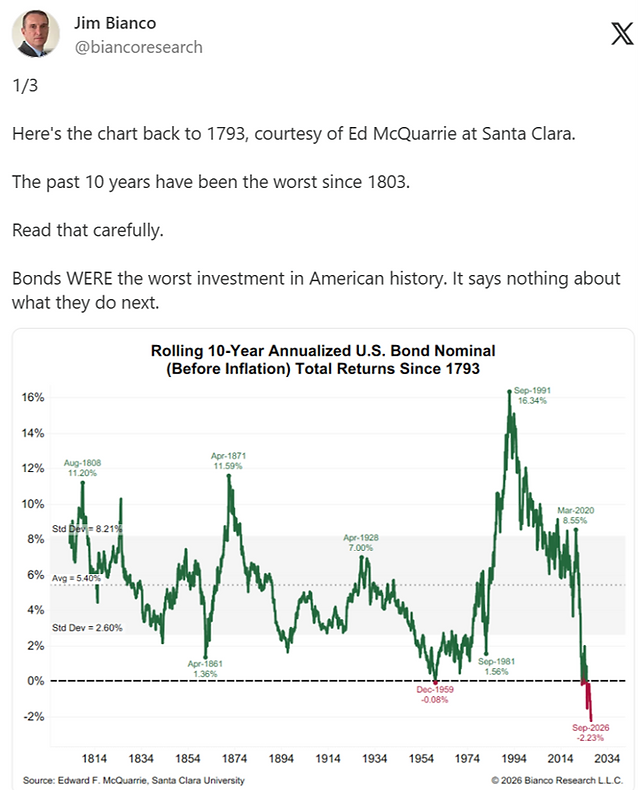
Finally, let’s look quickly at one chart from my friend Jim Bianco. This has been the worst 10-year rolling period for US bonds in history. He was responding to a comment that bond investing is likely to get worse because of the historically negative period that we have just been through.
Source: Jim Bianco
Comments
Log in or sign up to join the conversation.