Nucor and Steel Dynamics both expect stronger quarterly earnings, yet guidance disappointed investors; the outlook covers the mini mill margin squeeze.
The basic model for a steel producer is usually simple. If finished steel prices rise and shipment volumes hold steady, profits should follow. But growing profits and meeting Wall Street’s expectations are two different things. Nucor and Steel Dynamics both expect stronger quarterly earnings, yet their latest forecasts still disappointed investors. The question is not whether the steel business has suddenly stopped working. It is whether investors were expecting more improvement than these companies can deliver, and how much of that improvement was already reflected in their share prices.
Main Note
The Margin Squeeze For Mini Mills
Verdict: Better earnings are not always enough to satisfy investors. The latest steel guidance points to growth, but less than Wall Street expected.
What happened
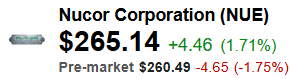
Nucor issued third quarter earnings guidance between $5.55 and $5.65 per share. That fell short of the $5.99 FactSet consensus estimate, but it would still represent growth from the $5.04 reported last quarter. Shares were down about 3.7% during Thursday’s after hours trading as investors reacted to the shortfall against expectations.
The outlook is mixed across the business. Nucor expects its steel mills and steel products divisions to earn more, while its raw materials business earns less because of weaker pricing and shipments. Higher production costs are an offset, but management is not forecasting a companywide earnings decline.
The important distinction is between an earnings miss and an earnings decline. A company can make more money and still disappoint investors who expected an even stronger quarter. Steel Dynamics actually expects its steelmaking margins to widen as selling prices rise and scrap costs fall. Weakness in recycling should not be treated as proof that the mills themselves are losing pricing power.
What changed in the thesis
The near term earnings outlook is weaker than Wall Street expected, but that does not settle the longer term investment case. The questions are whether pricing and demand hold up, what profits look like in a more normal year, and whether the current share price leaves enough room for disappointment.
What the market may be missing
Last quarter had two boosts that are not expected to repeat: $130 million in raw material procurement refunds and a $61 million pretax, non cash gain on Nucor’s Helion investment. Yet the new guidance still points to higher earnings. Those benefits make the comparison tougher, not easier. One detail worth keeping straight: Nucor’s $4.84 adjusted earnings per share removes the Helion gain, but not the raw material refunds.
Valuation and expectations
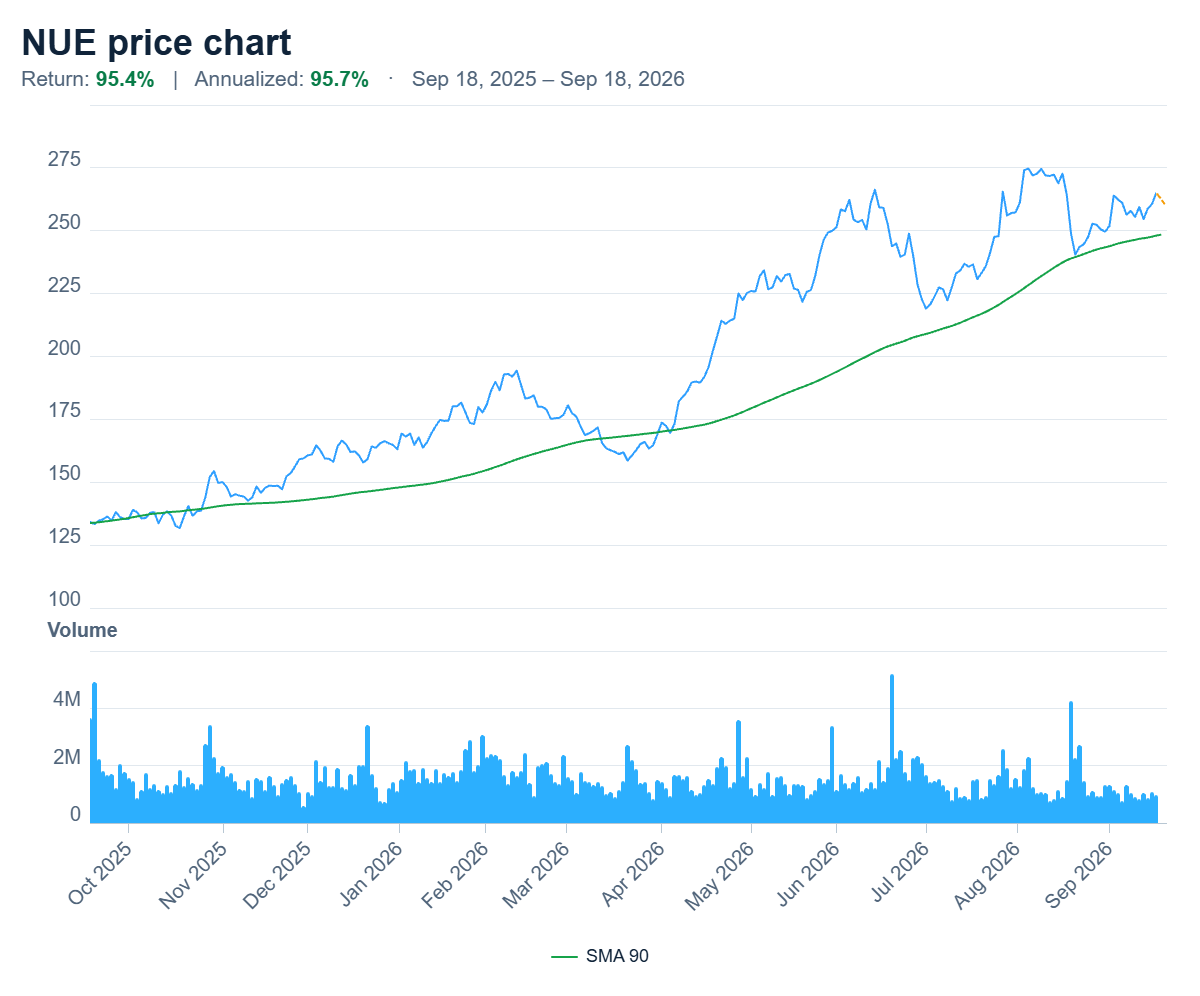
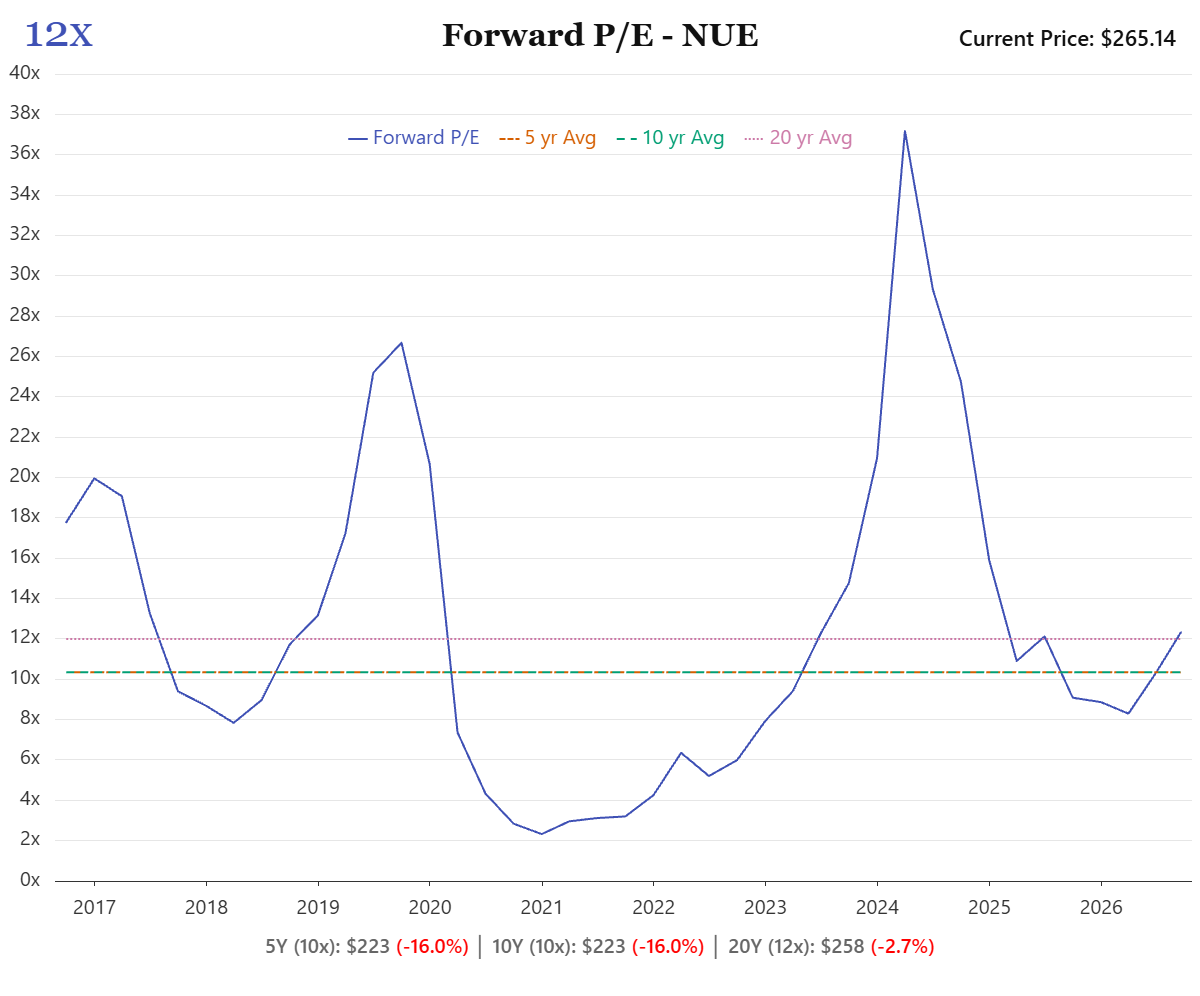
For valuation, the question is what Nucor can earn through a full steel cycle, not whether one quarter beats estimates. The company has bought back roughly 2 million shares this quarter at an average price of $247.04. Repurchases can help earnings per share when the business is profitable, but they cannot stop profits from falling. Whether those purchases create lasting value depends on the price paid and the earnings the business can sustain.
Nucor (NUE) Forward PE Ratio
Bottom line
The immediate problem is the gap between improving earnings and higher expectations. The longer term question is whether the shares already assume too much of the good news.
Pre Market Pulse
US stock futures were higher early Friday. At 4:50 AM ET, S&P 500 (SPY) futures were up about 0.3% and Nasdaq 100 (QQQ) futures were up about 0.6%, as falling oil prices helped ease inflation concerns.
The yield on the 10 year Treasury note eased to around 4.93% on Thursday.
Why it matters this morning
A stronger market can still leave individual stocks behind. For steelmakers, the immediate issue is whether profit growth is keeping up with investor expectations, rather than whether the whole industry has stopped benefiting from higher prices.
Thursday’s earnings forecast of $5.34 to $5.38 per share missed the $5.60 FactSet consensus estimate. But steelmaking margins are expected to improve, while recycling earnings weaken. Its separate fabrication business, which makes products used in construction, has a backlog extending through the first quarter of 2027.
In its July 23 earnings release, Cliffs forecast roughly $575 million of third quarter adjusted EBITDA, versus $286 million in the second quarter. That measure excludes interest, taxes, depreciation, amortization and selected adjustments. Management pointed to stronger pricing, automotive volumes and improving costs. It is useful background, but not a fresh Thursday announcement.
Nippon Steel (NPSCY) completed its acquisition on June 18, 2025, and U.S. Steel is no longer a standalone publicly traded stock. It remains an important industry competitor, but the relevant comparison is its operating performance and investment plans.
Group takeaway
These updates show different pressures across steelmaking, recycling and finished products, not a clear divide between winning and losing production models. Investors should compare each company’s customers, costs and balance sheet before drawing a conclusion about the whole group.
What to Watch
Management commentary on 2027 cost expectations during the full third quarter earnings call in late October.
Monthly scrap and hot rolled coil pricing indices to see if shredded scrap export demand stabilizes.
Updates on major capital expenditure projects where execution risks are highest.
Bottom line
Better quarterly profits are encouraging, but they do not automatically make a steel stock cheap. The investment case still comes down to sustainable earnings, sensible capital spending and the price paid for the shares.
Disclosure:
At the time of publication, the author has no long or short position in any securities mentioned and does not plan to initiate a position within 72 hours of publication. The author was not compensated by any company mentioned in this article.
Disclaimer:
InvestorsGrow and the Morning Note are published for informational and educational purposes only. Nothing in this email or on InvestorsGrow.com should be considered personalized investment, financial, legal, tax, or accounting advice, or a recommendation to buy, sell, or hold any security. The content is general in nature and does not take into account your investment objectives, financial situation, risk tolerance, or individual needs. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results. Opinions are as of the publication date and may change without notice. Data and information are believed to be reliable but are not guaranteed. The author, InvestorsGrow, affiliates, and/or contributors may hold, buy, or sell securities discussed. Article-specific positions, compensation, or conflicts are disclosed where applicable. You are solely responsible for your own investment decisions and should conduct your own research and consult a qualified professional before making financial decisions.


Comments
Log in or sign up to join the conversation.