Geopolitical shifts and controversial energy policies add volatility to a strange bull market ahead of Tuesday's earnings kickoff.
Derivative financing - (access to capital) is what 'seems' to worry managers; but of course it's a fear of a 'chair leg breaking' as some pundits call it; and I'll just say it's impossible to time something like that; which can matter for the big hyper-scalers. But it's barely meaningful for the new-era tickers, because lots of them are selling near 52-week lows (unfortunately) and are post-purge.
The players that do 'not' need to use dilutive financing, and are already solid, are generally pressured along with those that do rely on offerings and lending. In the meantime, with midterms and Oil prices plus the war; the beat goes on.
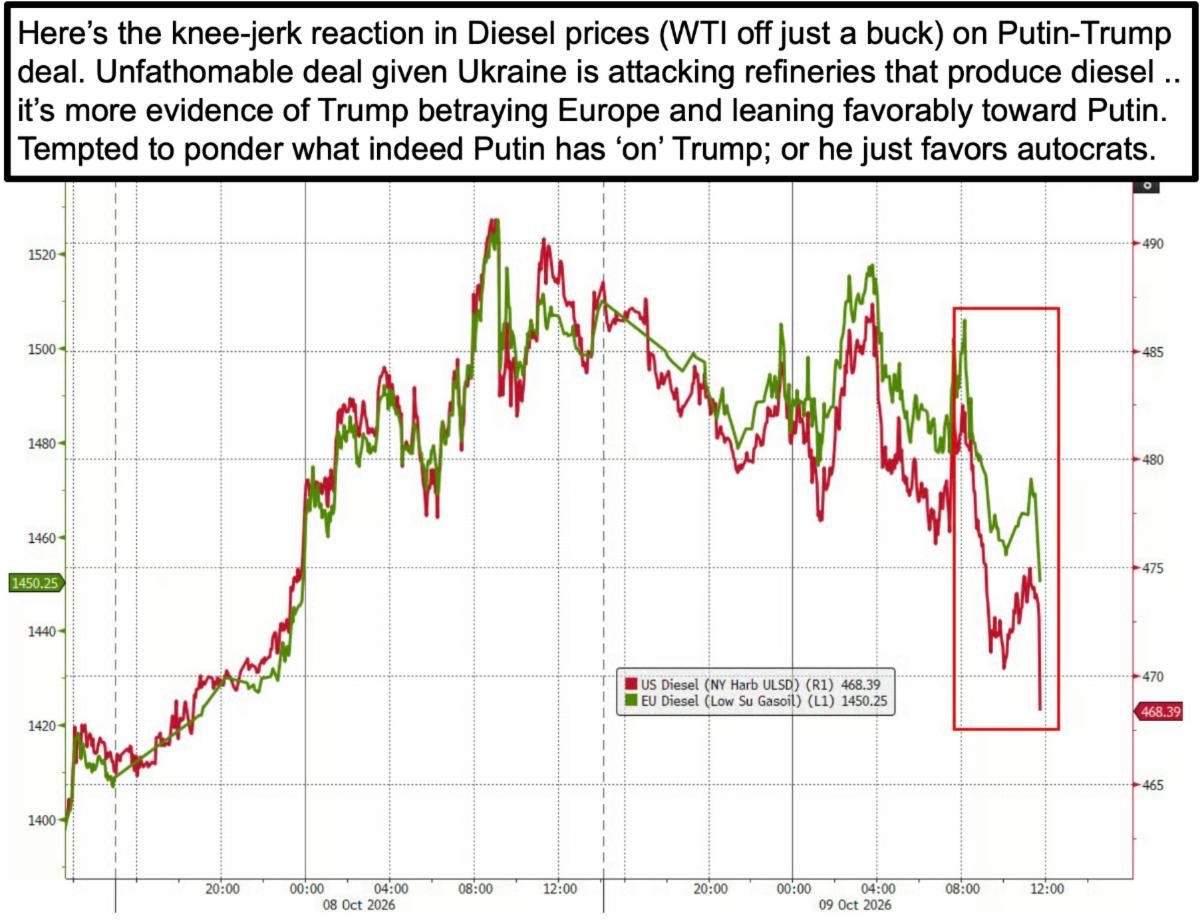
There is no change to the consumer picture; the market picture; nor even the geopolitical picture today; except for the (insane?) deal to import Russian Oil; or more precisely diesel fuel. It's purely political; purely not thought through at all (I doubt State had involvement); as panders not only to Putin but to voters.
I don't usually take positions on such issues but this one is dumb. It obviously is intended to appear to truckers and farmers who normally vote Republican; at the same time recognizing they are pressed by high fuel prices. But given the actual quantities Russia can deliver (and not very quickly), it's a proverbial 'drop in the bucket'; relative to average daily U.S. diesel consumption; much less weekly or longer. Plus it undermines U.S. foreign policy and that of NATO as well; hence either this was impulsive (per the Trump/Putin phone call), or a slap in the face not only (obviously) of Ukraine, who is trying to put those very refineries in Russia out of business; but think about it as a slap on freedom.
That's as it's also a big slap to the United States; since our policy is staunchly pro-Ukraine (supposedly anyway and also bipartisan); but masked by the halt in military aid that also should not have been the case. Sorry; I disdain certain policies on both sides now, and I'm not particularly leaning 'libertarian' (maybe as of now?).
Last evening I had a bite with an old NY trading friend, who's actually Russian (lived in the US for a few decades) and played hockey there and trains boxers here. Before this diesel fuel news hit; he lamented the Ukraine war; agreeing that any victory by Putin would be Pyrrhic since Ukrainians will never forgive Russia all this for at least a couple 'generations'. I asked him last night 'what does Putin have on Trump'.. and he said 'must be something heavy'. No idea; but he's a guy that hobnobbed with the MAGA bigwigs for a few years... this has a canine aroma. When you get right-leaning ex-Russian-hockey players furious with Trump 'and' Putin, you ponder who is running the asylum. It's not Rubio (because he's actually smart); nor Bessent (he just implemented new sanctions on Russia and smart; so how could he endorse this nonsense).
I think NATO will be angry; and there ought to be a domestic upheaval about this; including from Republicans... most of whom welcomed Zelenski and sure don't support the idea of helping the devil, which defines what Putin sure is. I digress but thinking a bit on this story is upsetting; trying to buy a few votes in November with lower fuel prices? And you won't even get much of that so fast especially with recovery from today's hurricane, and if the Iran war persists. In fact it may be that Trump's goal is to temporarily restrain fuel costs while they prepare for a post-midterm attack on Iran should no success precede that. Oh well, at least we didn't focus on the non-democratic radical leftists today.
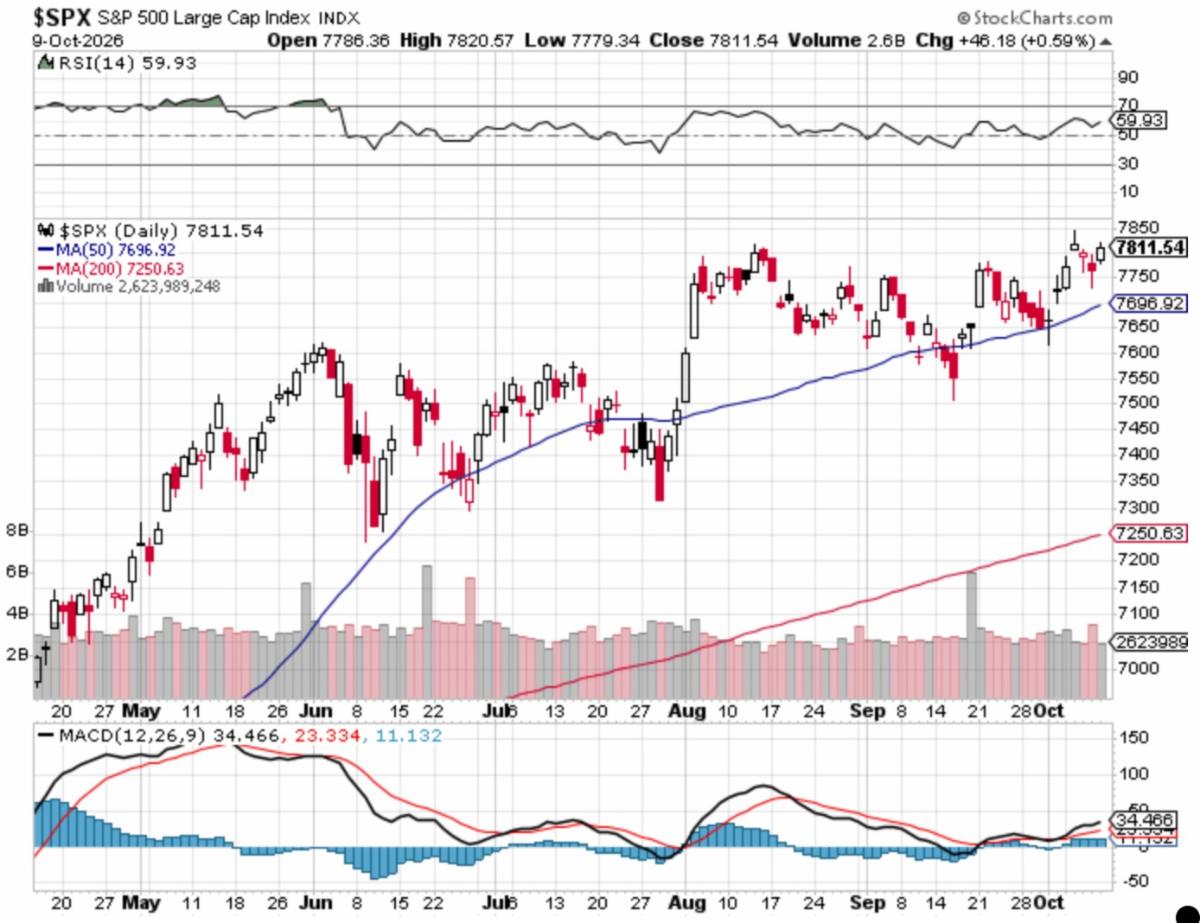
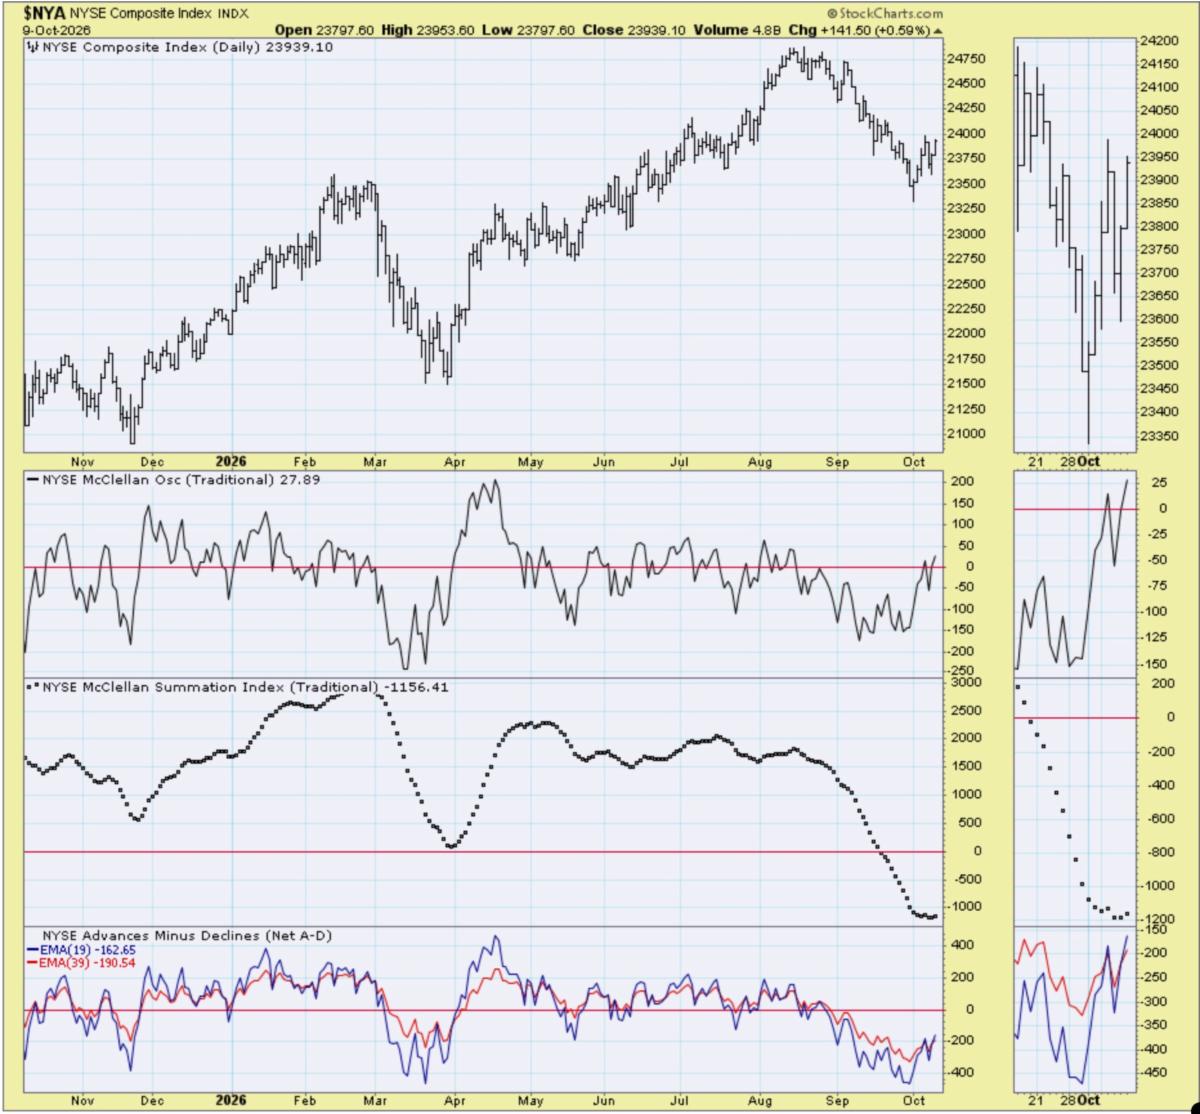
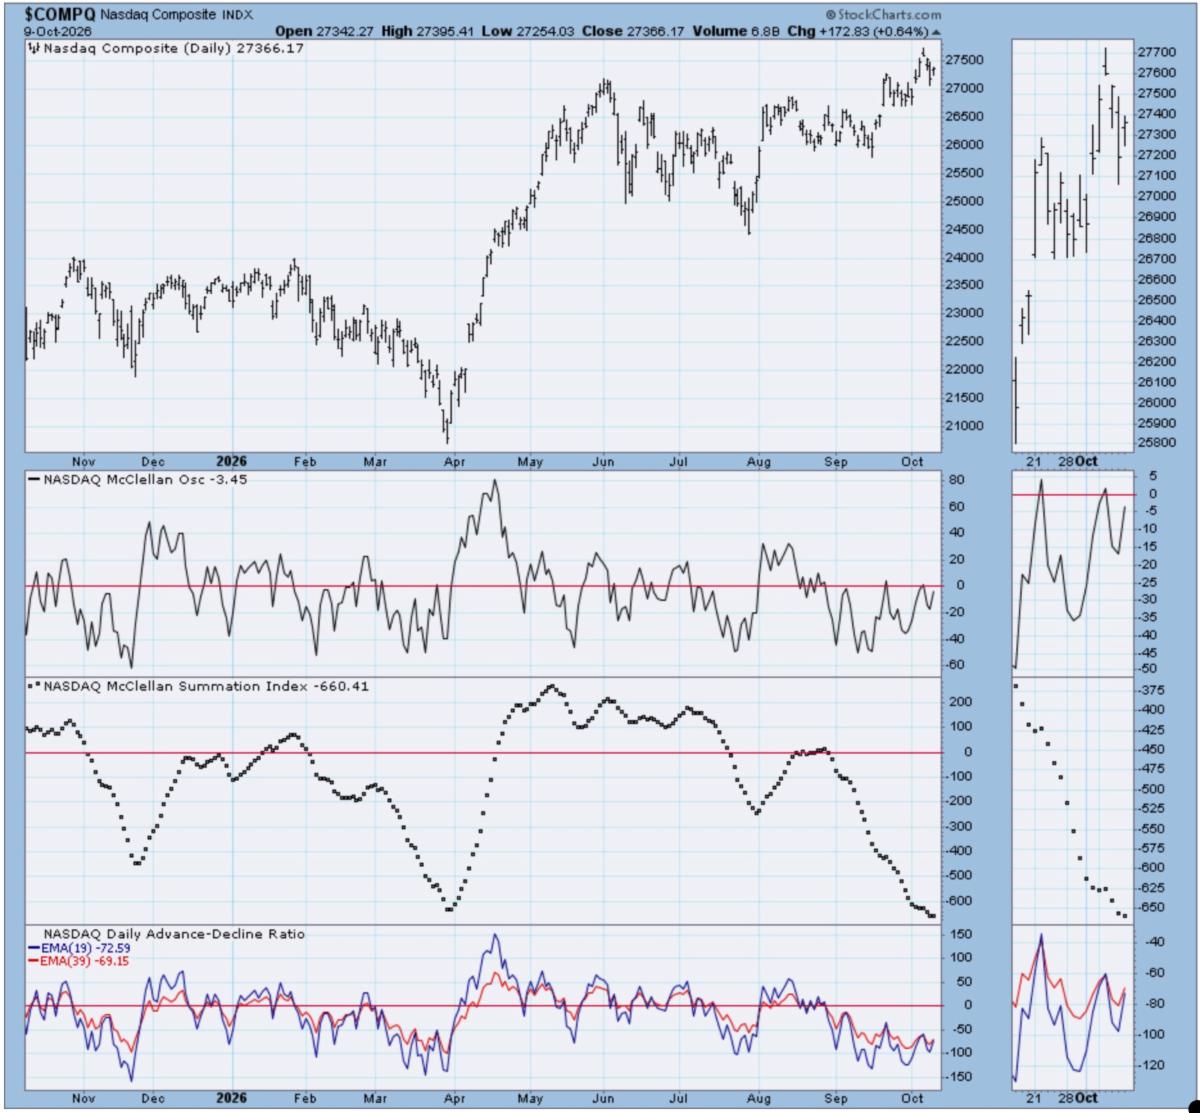
Market X-ray: this has been and remains one of the 'strangest' Bull Markets ever. Internal corrections have been significant in big-cap and small-cap alike; with a half-dozen stocks sustaining the S&P index, since it's 'capitalization-weighted' (not price-weighted) so they can do it.
That's why I've repeated pointed-out days where more 52-week new lows were reached than 52-week new highs; a set-up that technically requires either a catch-down by the leadership (the Generals taking 'point' as we used to say); or a catch-up by the hunkered-down majority (the Troops). So far this time of year, and scorned like an old romance, several times over, the Troops are reticent to emerge from their trenches; although they should later in the year and/or into next year, if not sooner. But it is all unusual and not attributed so much to Yields, as to the war and Oil; which if that resolves, changes it up.
Also, regardless how you interpret the FT story about OpenAi slower and lower revenues; any data-center opening later or delayed by community pressure or whatever, makes it harder to finance, as well as delays revenue.
We get into Earnings starting Tuesday (action truncated by a partial holiday with only stocks trading on Monday). I think I've expressed the rest that I wanted to highlights; and suspect certain new-era tech-tickers if they haven't bottomed daily-basis, will do so any any time; as some of the pricing is ridiculous; unless you assume the United States somehow wants to let Russia, China and Iran dominate the drone business. Of course not (so we should see more .. especially in the growing commercial ..as well as military.. counter-drone aspects).
Disclosure:
This is an excerpt from Gene's Daily Briefing (distributed nightly), which typically includes videos as well as more charts and analysis.

Comments
Log in or sign up to join the conversation.