
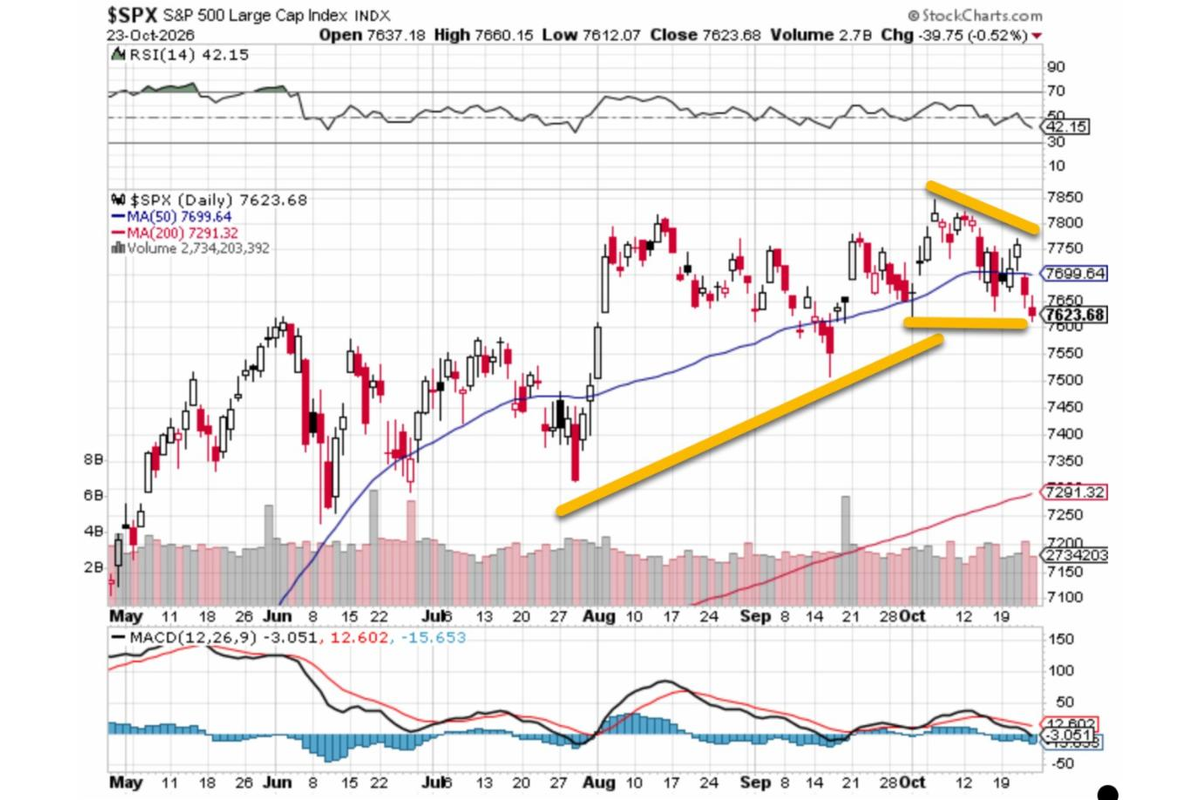
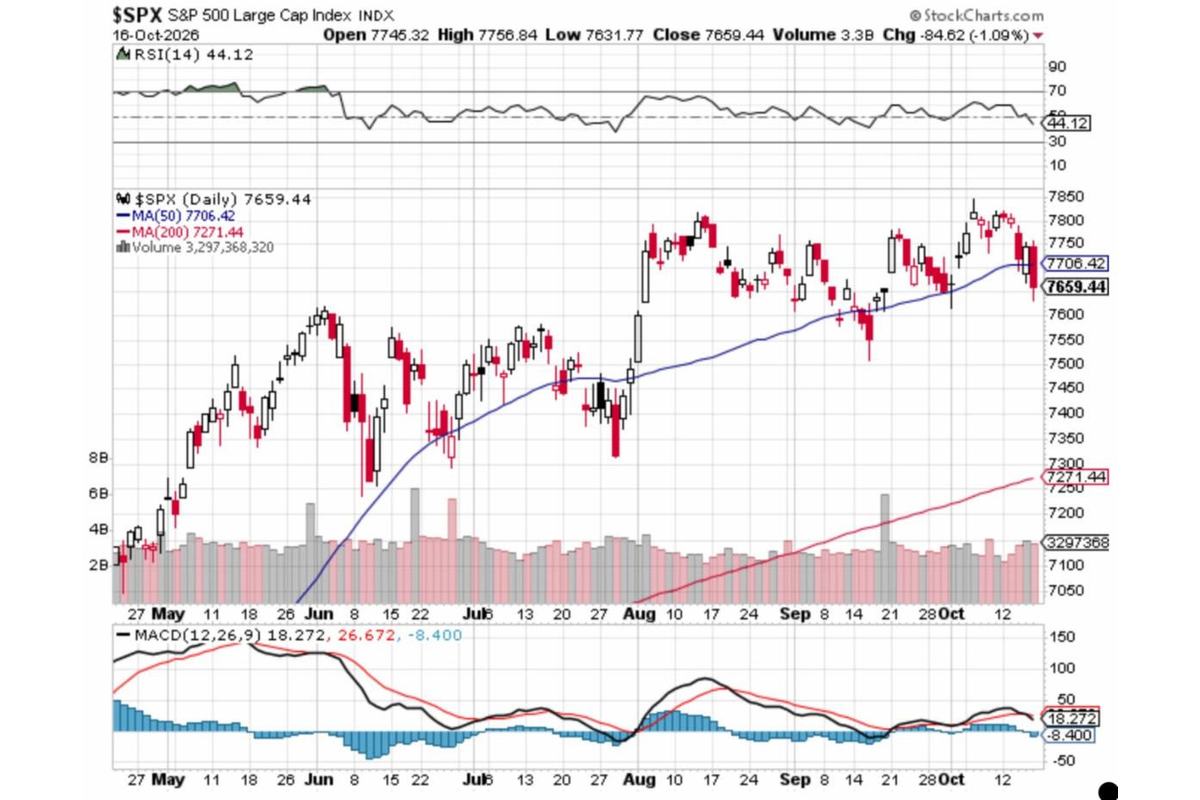
 4-D Chess about describes what's ongoing in this troubled world; including beyond the stock market, but with direct or indirect implications for so much. It is a worn-out battlefield; but still feasible to have booby-traps sprung anytime. Heading into next week, traders do face a minefield of binary headlines rather than a clean macro runway (especially with both APEC on-tap and the NVDA saga continuing), leaving markets caught between believing seasonal and/or resilient underlying fundamentals offset elevated political risk. But uncertain. |
|
Fairly-hot producer inflation data late this week served as a reminder to those who don't believe it's primarily about Oil prices related to an ongoing war; that they think the Federal Reserve still has work to do, keeping macro backdrops sensitive to any fresh shocks. And we will probably get one or more.. Certainly the centerpiece on the global stage is next week’s APEC Summit in Shenzhen (Nov. 18–19), where Donald Trump, Xi Jinping, and Vladimir Putin are set to share the spotlight in China’s hardware and tech capital (oddly that in a time of controversy over chip sales, they meet right in the heart of China tech). Hard to say how it evolves. So while markets aren't pricing-in sweeping new trade breakthroughs ahead of December's G20 follow-up in Florida, any trilateral optics around Ukraine, rare earths, or extending the U.S.- China tariff truce past January will keep headlines twitchy. Or of course if linkage to Nvidia chip transshipments comes into play (anything confirmed other than current suspicions ... well who knows). |
|
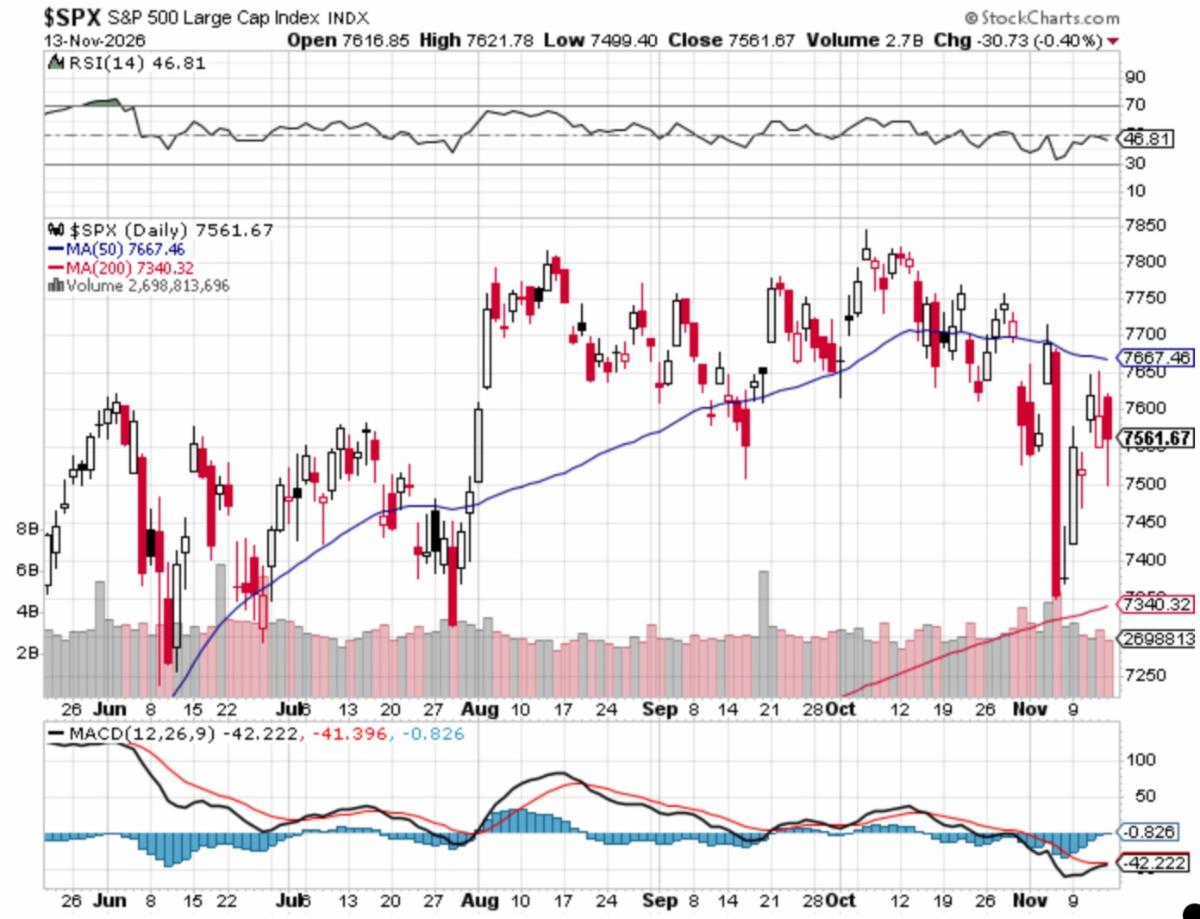
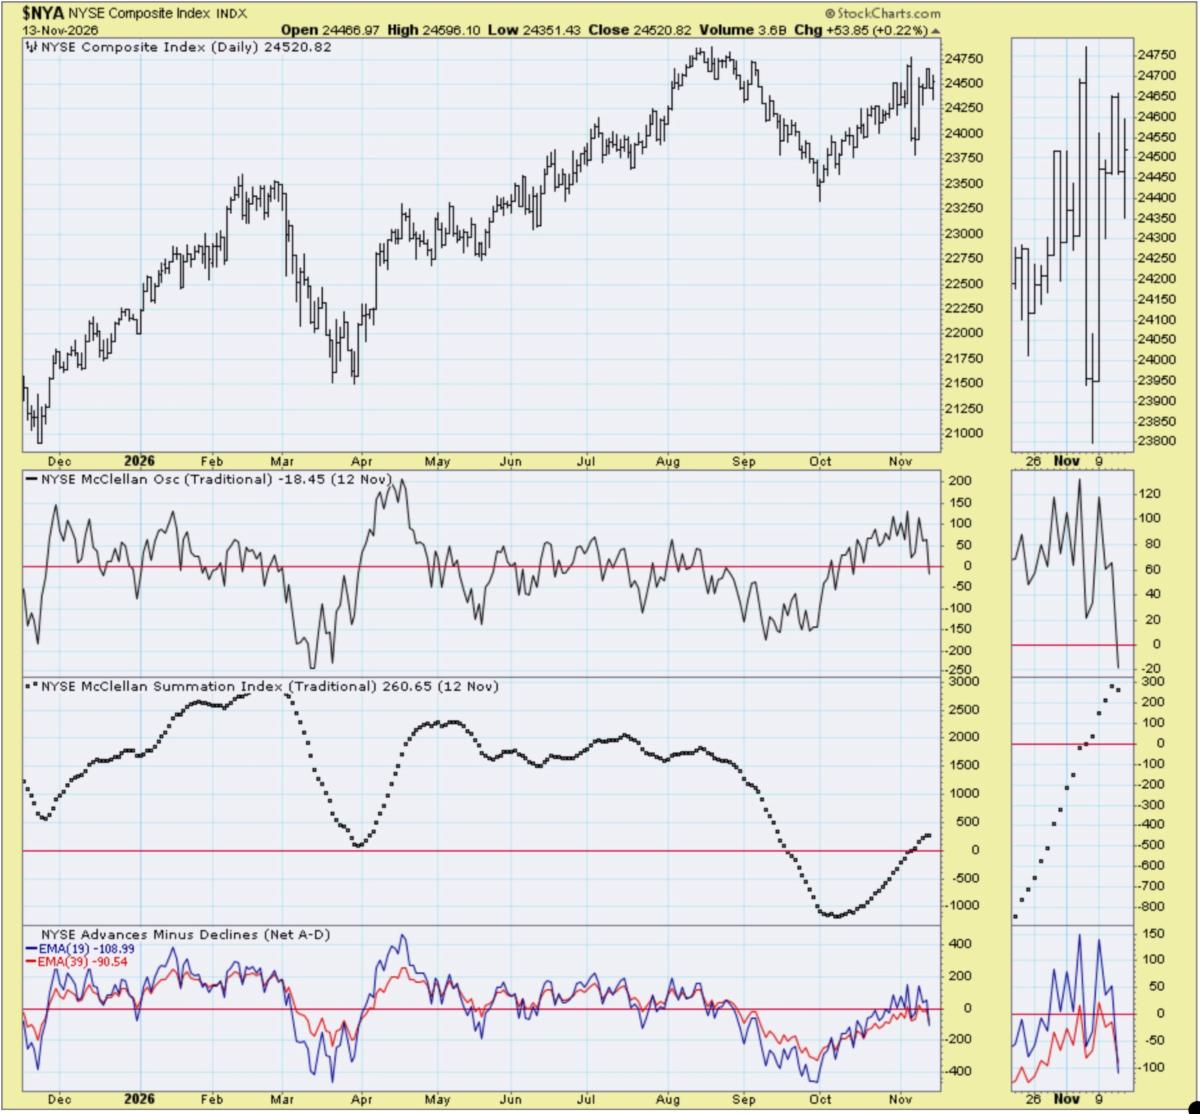
Market X-ray: based on reflections from a few members; let me say this for any or all who got a bit too leveraged into high beta (which we avoided; but at the same time the series of 'Bordello Raids' clearing the deck so to speak. So it sucks to be here but take it as a learning opportunity for new or levered members, to keep dry powder on the sidelines for when prices get lower than what anyone ever expected; although they are not lower in mega-tech; just in a variety of others that you'd think would bottom in October but still pending or a work in progress. I guess the lesson is leverage less than you think and for sure don’t revenge trade on emotions. In my opinion most new-era tickers will do well in the long run; although there are political (and funding) elements that to a degree have intruded, and that's what historically can be a peril of dealing with Federal spending (today there was a push to expedite programs; but now you have a reticent Congress and an Nvidia scandal sure hasn't helped matters in, not because of chip sales or AI as such; but gamesmanship or favoritism, that complicate some aspects of this ought-to-be Tom Clancy novel. How it sorts out is in coming chapters. |
|
|
Closer to home, Middle East risk remains a wild card after Treasury Secretary Scott Bessent joined other senior officials in (apparently compelled) relocating to D.C.-area military housing, amid heightened Iranian assassination threats. While Washington insists the move is a reasonable defensive precaution, tied to its economic blockade and intelligence warnings, rather than any prelude to new U.S. strikes (for which we would also disperse our leadership a bit), any escalation in the Strait of Hormuz could immediately jolt crude oil which more recently has been easing overall. Plus there are several alternative tactics as might occur from Riyadh in response to Houthi attacks (some say close to an overrun of a key Saudi position) ... and Saudi threats to flow the world with Oil; although I don't think that strategy is going to work for them now (that's what they did decades ago to damage the U.S. oil industry and might now want to now, considering the memory is still there among some of us impacted then). |
|
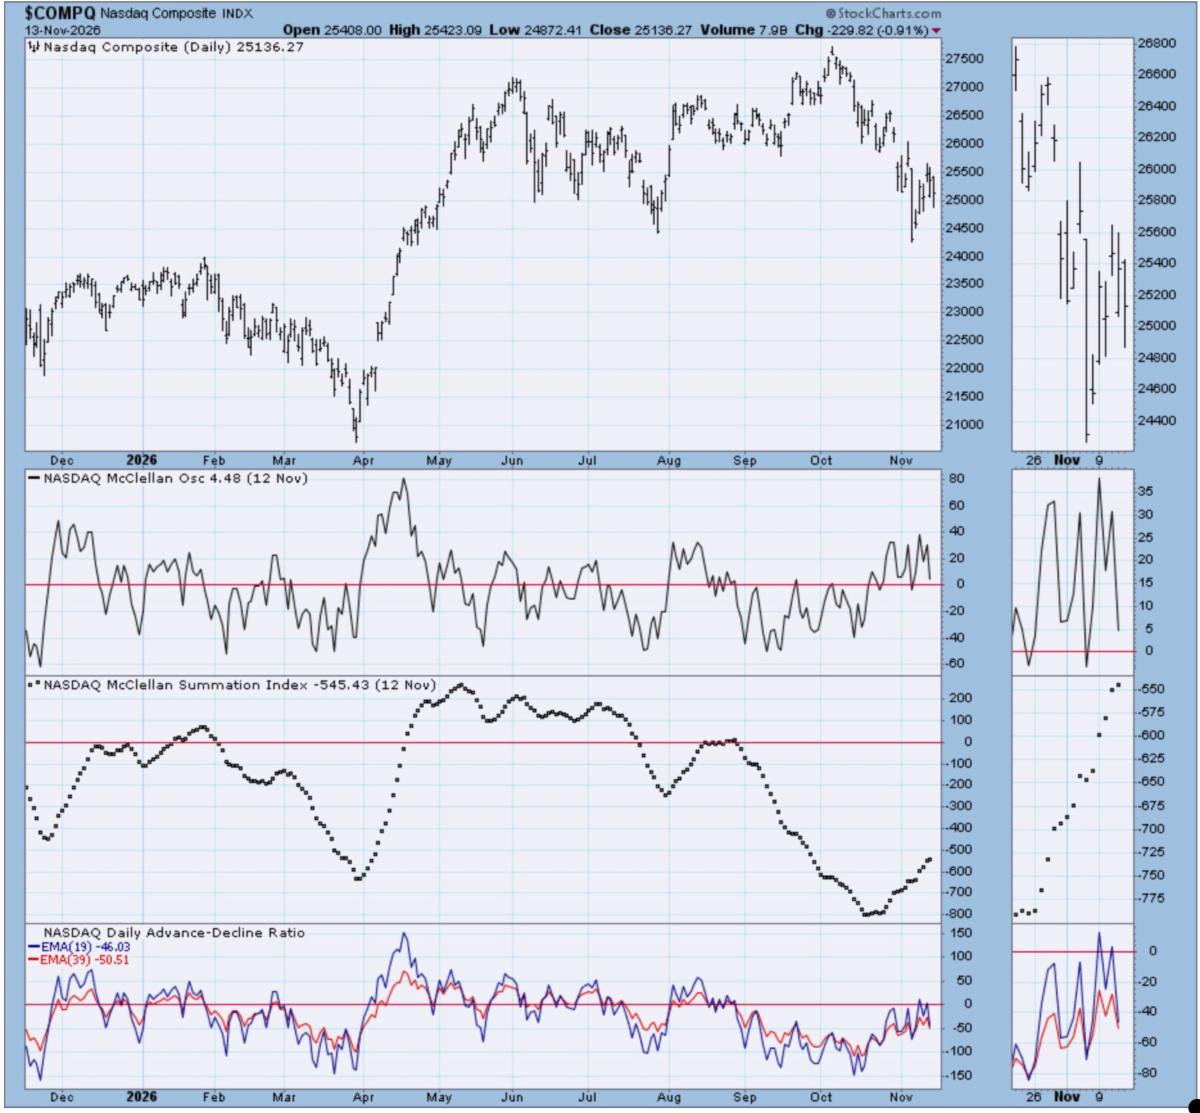
Finally, technology faces a pivotal coming week on multiple fronts beyond the confusion following Jensen Huang’s resignation as Nvidia CEO and interim chief Colette Kress stepping in. Kress faces her first major Wall Street test when Nvidia reports Q3 earnings on Tuesday, right as Huang prepares to testify before House committees on Capitol Hill regarding ties to an alleged Chinese intelligence operative ... while Commerce Sec'y. Lutnick has agreed to appear to the Banking Committee; but not until December 5th I believe. Certainly Thursday’s expected Anthropic IPO will be a real-time barometer of institutional appetite for AI infrastructure. Personally I'd avoid playing into any strength; just as we thought at other recent IPO's including SpaceX. (If there is interest, we'll consider it typically only after lockup restrictions expire.) Meanwhile, beneath the mega-cap noise (which we warned forthcoming over a period of months), domestic/global new-era defense, drone and photonics new-era tickers continue defensive despite strong operational momentum, in most cases. That's highlighted by Ondas' record $835 million backlog and raised multi-year revenue outlook even as the market digests lower near-term profit-margin tradeoffs (revenue almost doubled but margins nearly halved; so not too worried neverthelss as that should perk-up in the next Quarter or two). In fact on Friday Wainwright reiterated ONDS as a buy at these levels. I'm not aware of other updates from covering analysts. |
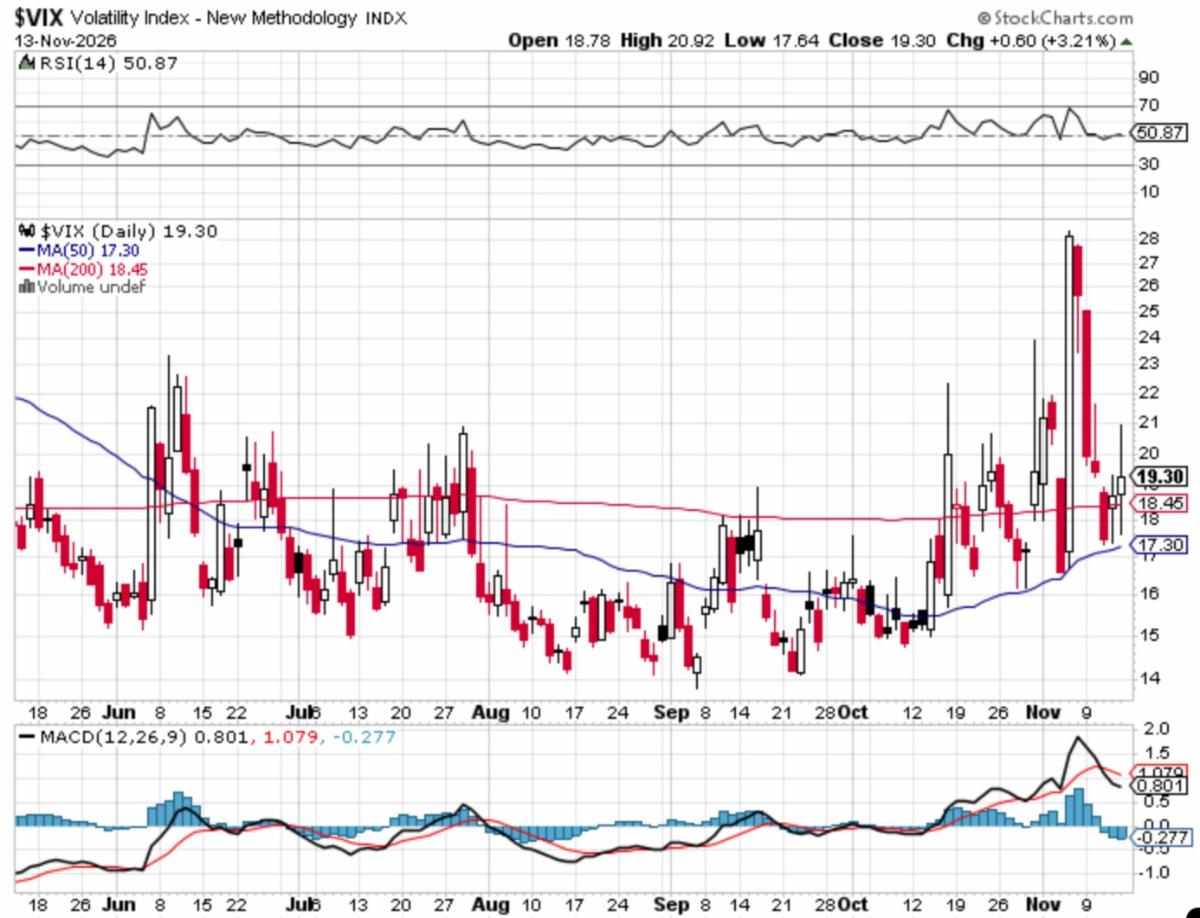
Bottom-line: stock sectors trade in trends and narratives. Currently the drone and defense sectors are defensive and bearish for a few months. Has nothing (or little) to do with fundamentals of a single company. Pick any of them, and for the most part you will notice each has declined by 50% or more since their top. By the high-beta metrics we're in line with the trend; presumed near lows. In reality, this scenario isn’t exclusive to the drone sector, actually it's a wider trend against all high beta stocks in a larger risk-off sentiment since typically a high roughly in July. And seasonally we ought to be bottoming but look what's appeared to spook markets, or at least delay enthusiastic new position taking. Some tickers are faring better than others but alone that doesn't defeat macro market sentiment. And there is risk as noted earlier (perhaps both ways) over the days just ahead; depending what happens with Iran war, and in Shenzhen for that matter. As to the brouhaha involving the Administration; that's not the vote of confidence in leadership one might like to see and it muddles along. Relax over the weekend and we'll tackle this again next week. |
|
Comments
Log in or sign up to join the conversation.