
|
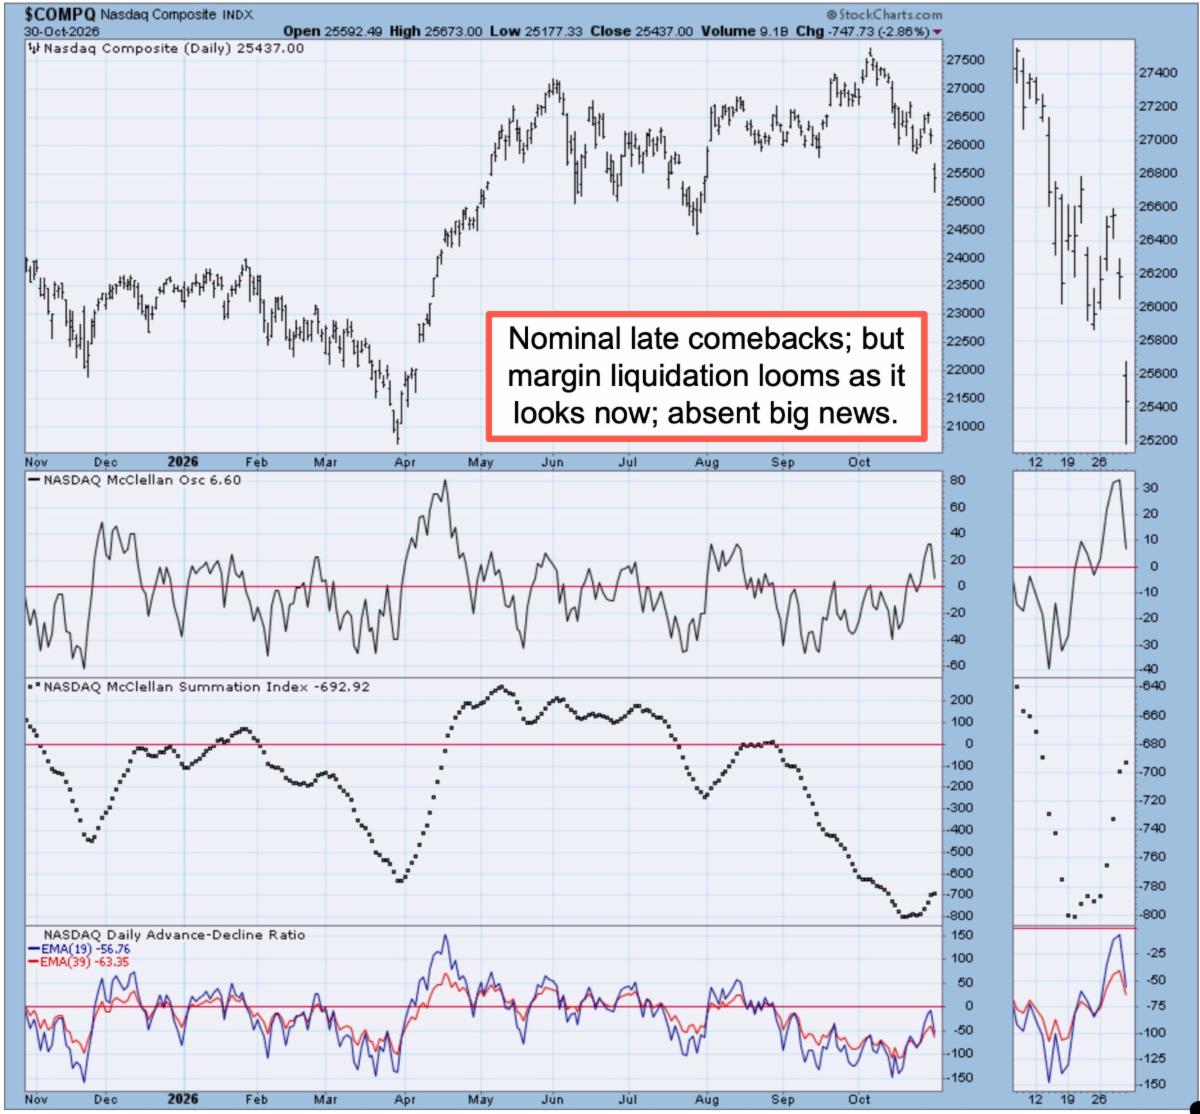
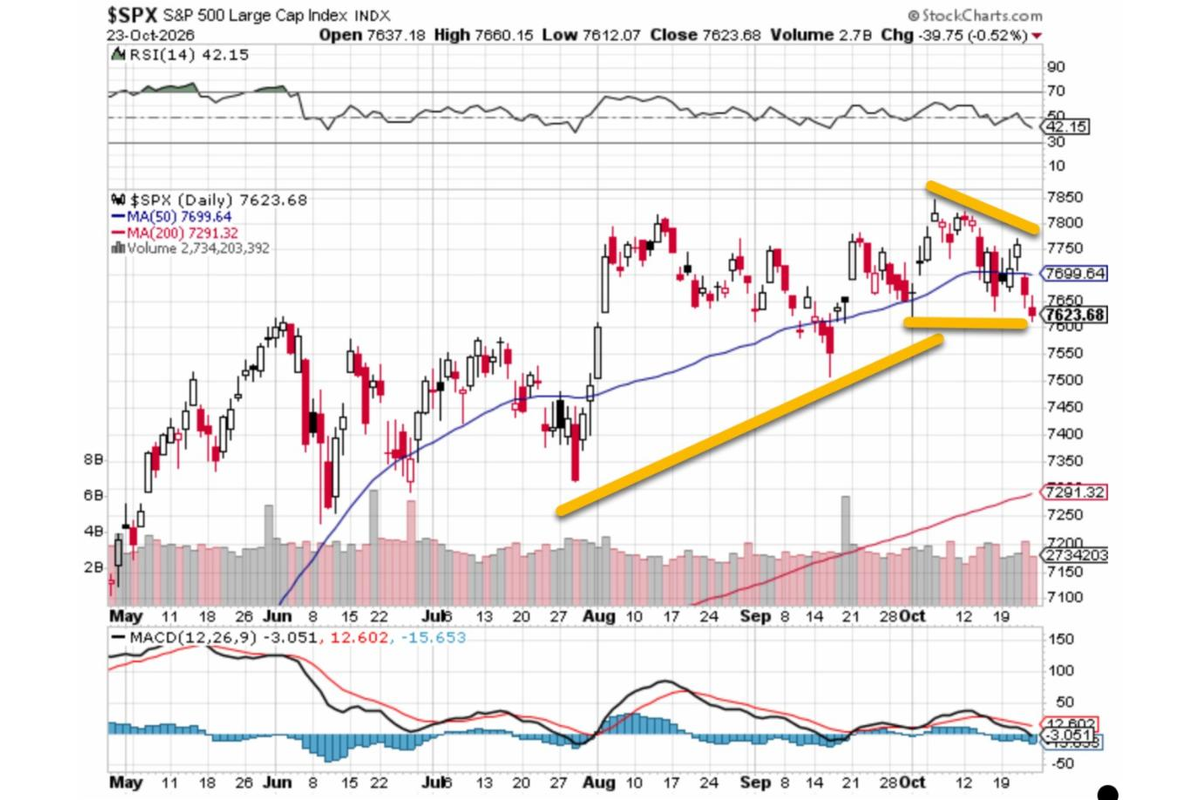
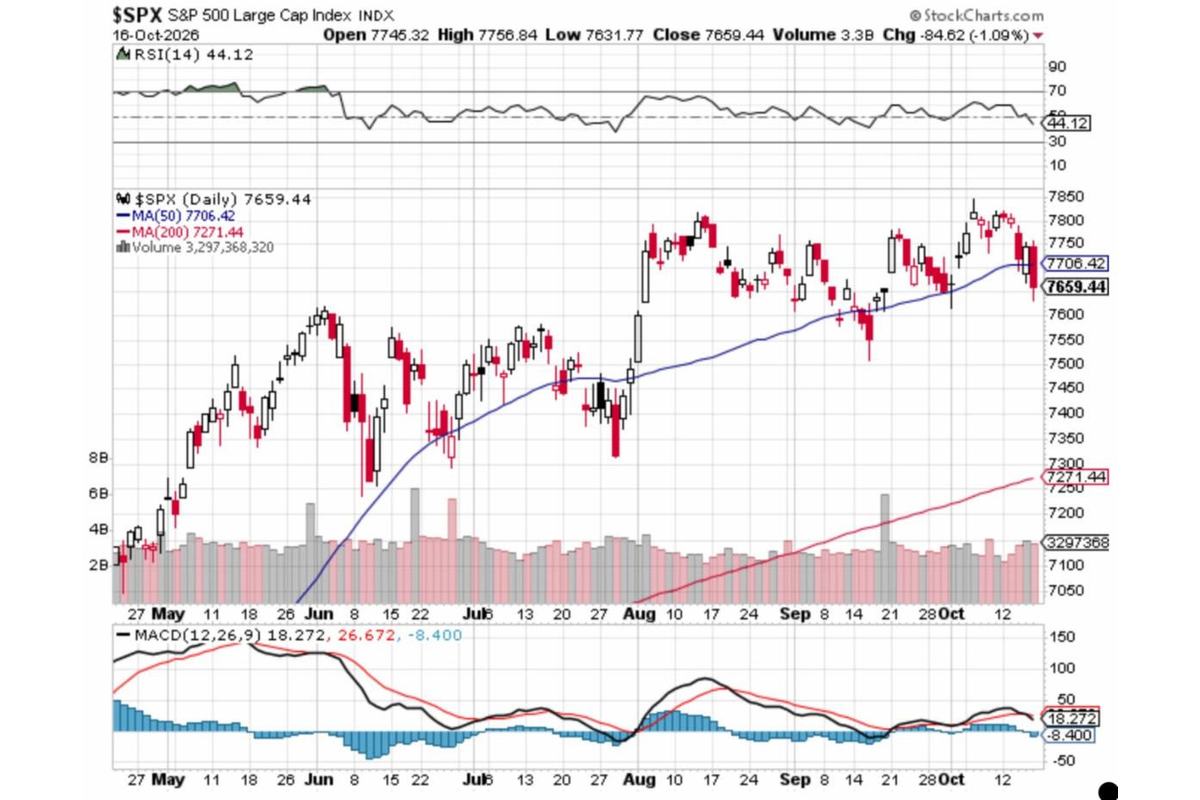
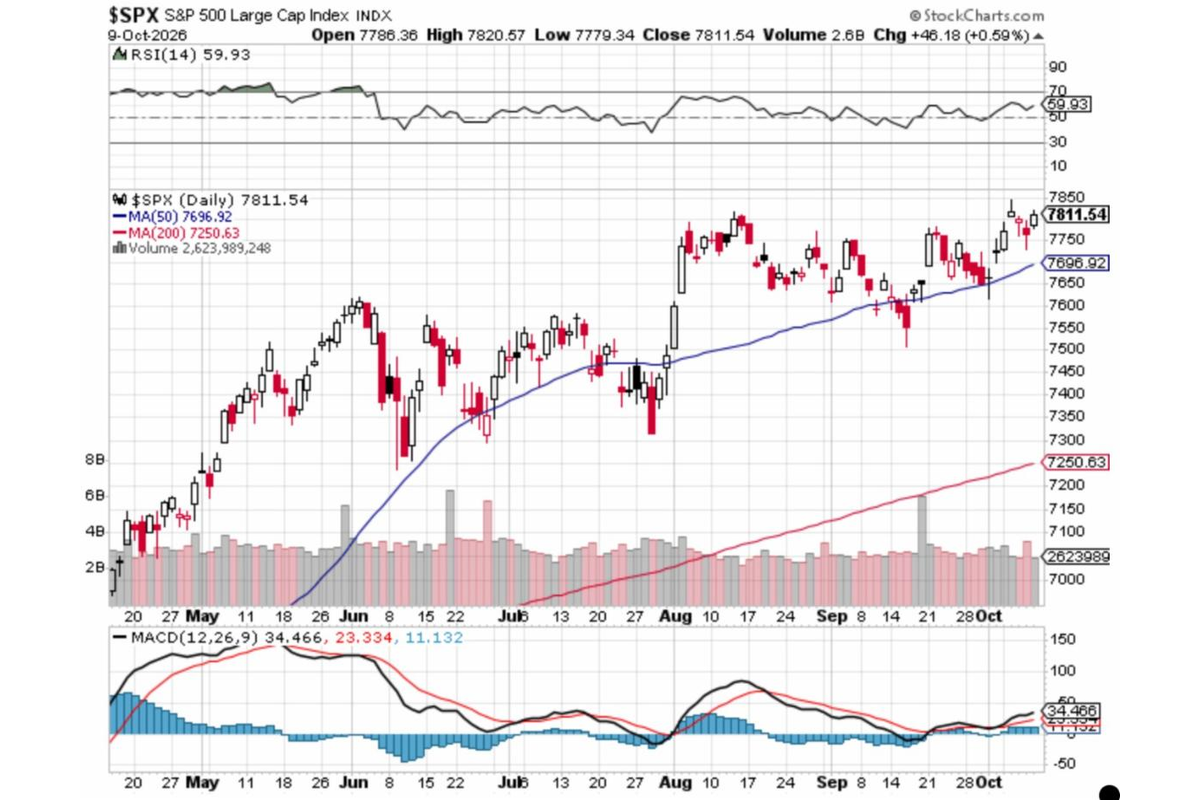
Wall Street closed out a brutal 'Roctober - with a textbook "growth scare" on Friday, as tech-heavy Nasdaq plunged 2.84% in its worst single-day rout since June. The S&P 500 shed 1.82% and the Dow surrendered over 570 points, wiping out billions in market value as investors aggressively rotated out of high-flying tech names and into defensive safe havens a bit too late. I discussed this all week and really even before the September-October rough patch that is traditionally difficult anyway. Earlier in the year we had a rally; we thought the mega-caps needed to be 'risk-off' with the forecast rally into July a culmination of the trend. Of course almost 'all' major money managers stayed loaded to the gills with the mega-caps; and a couple media pundits (I'm being nice and didn't say 'carnival barker types') kept encouraging high-priced buys. For sure we're not feeling heroic because the macro overall backdrop got so bad it didn't favor small-caps either (which typically are difficult when rates are climbing; part of why the few we picked generally have low debt profiles and are not anticipated to dilute by offerings or borrowings; as acquisitions making money are not the same because they are generally accretive). |
|
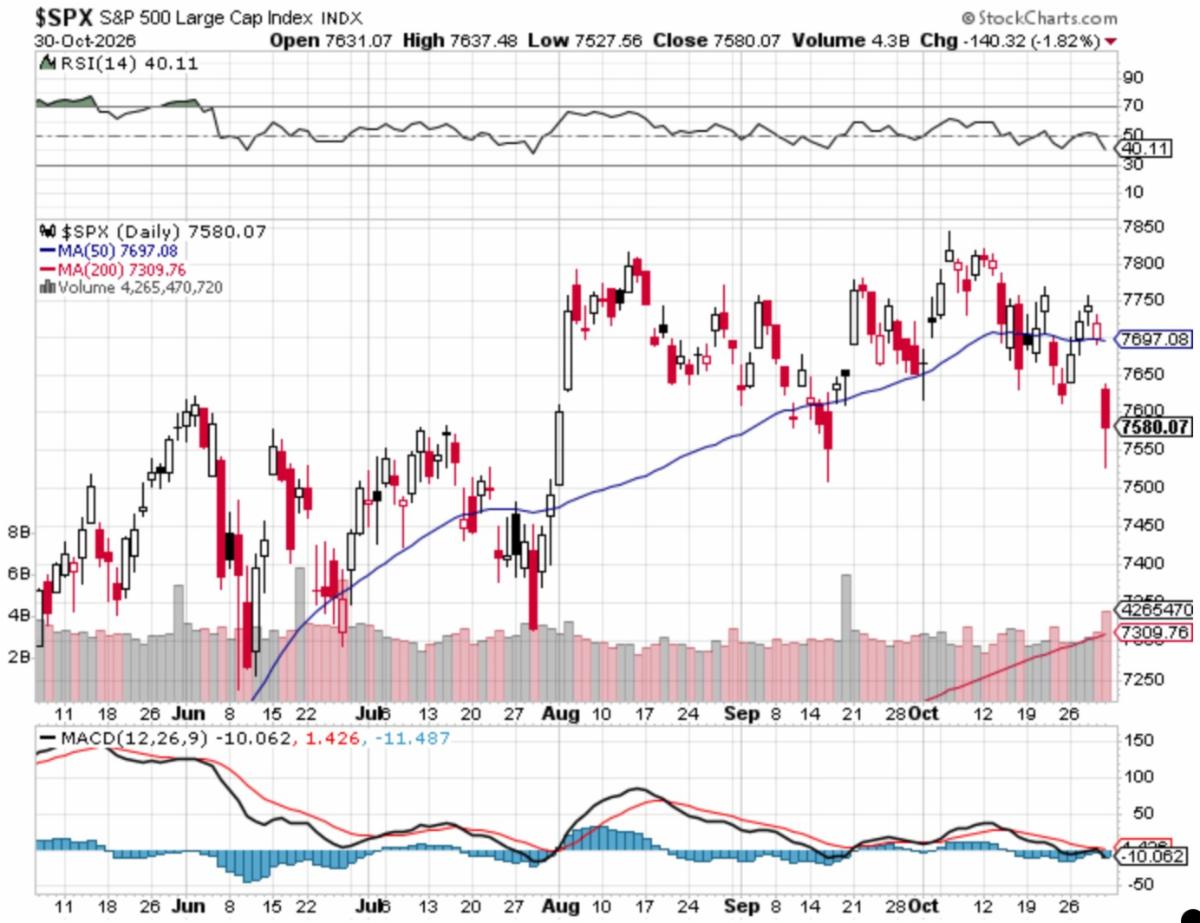
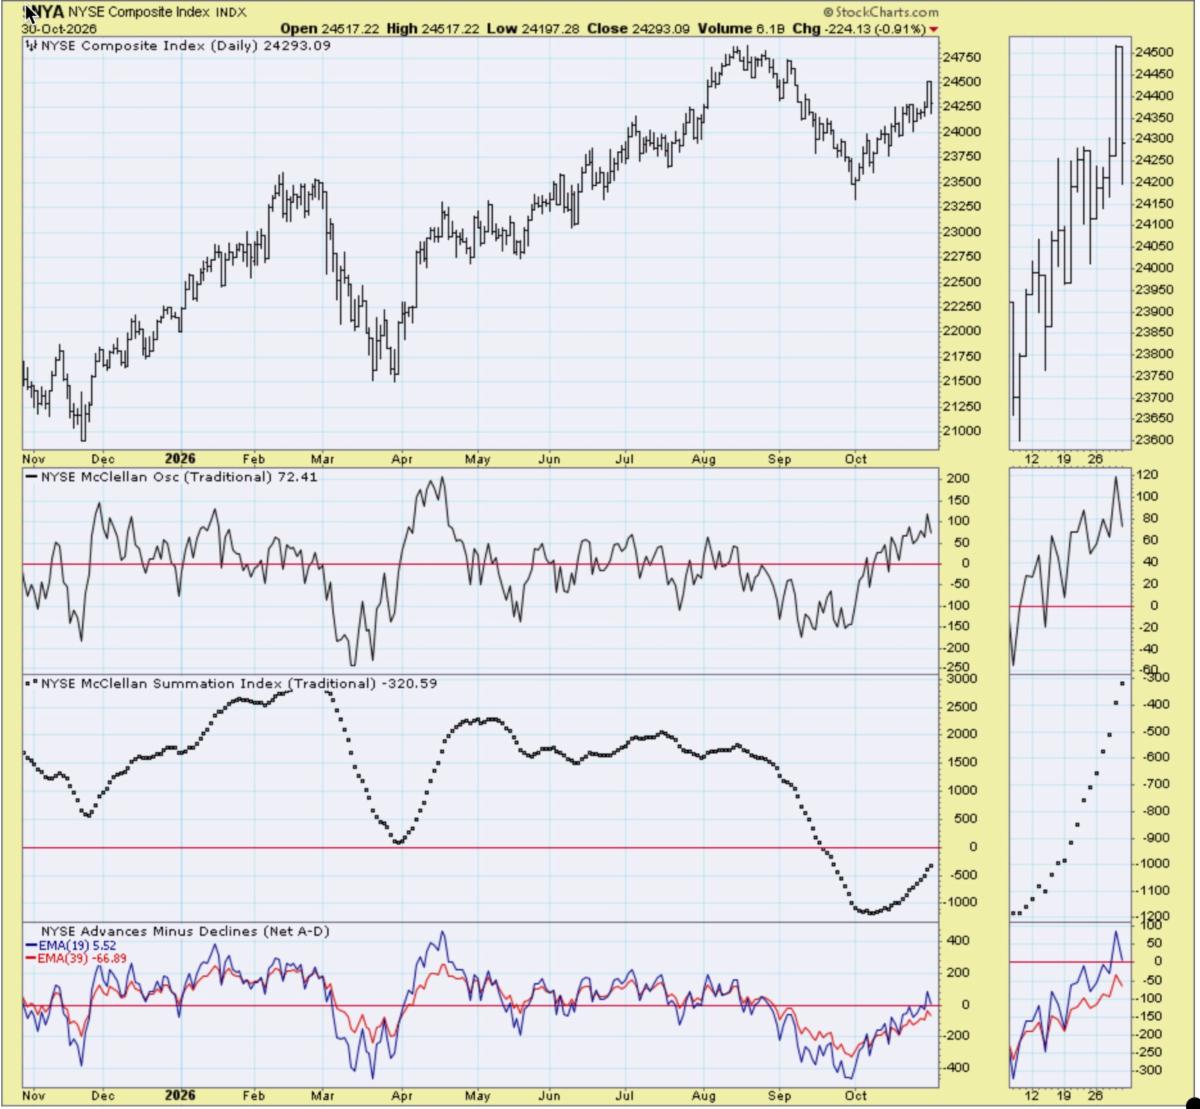
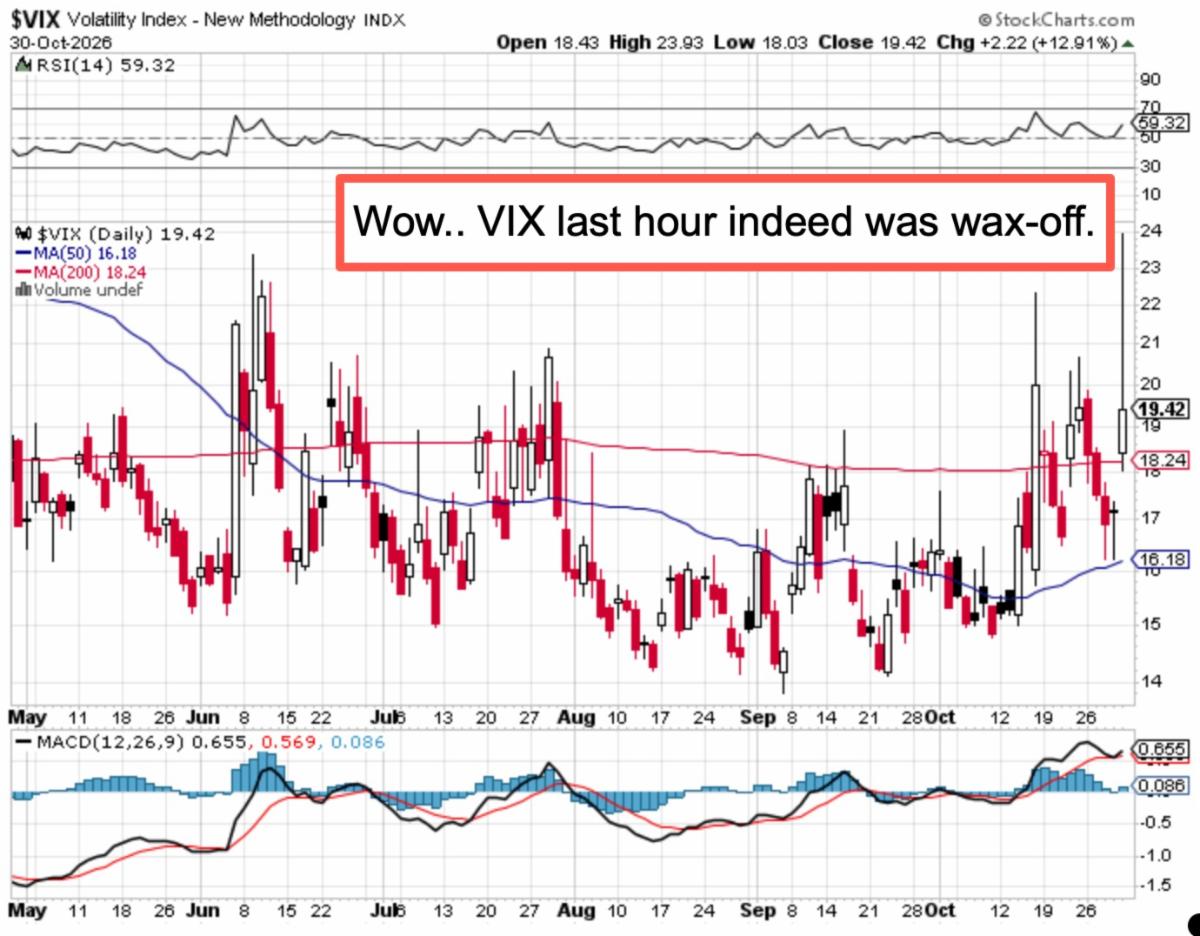
In a last hour 'X' comment (below) I mentioned some nibbling in the throes of harsh selling ; because we were in a 'buyer's strike and I thought perhaps this was not necessarily a low for S&P (with residual fund sales and margin calls likely coming Monday); but rather just in-case something favorable happened I thought these prices will look good weeks or months from now. I think so; of course a problem with the future is it's 'history's not yet known' so we'll see. The primary catalyst this week was what I've warned of for months regarding the humongous data-centers; and insane CapEx that I've believe isn't even a necessity because the combination of Quantum and optical will bring massive improvements in 'compute per dollar' basically with less power and heat too. This calamitous end to the month was catalyzed by a harsh reality check in Big Tech earnings, where hyperscalers like Alphabet (GOOGL) and Amazon (AMZN) revealed staggering increases in capital expenditures. Investors, growing increasingly impatient for tangible returns, severely penalized these nosebleed valuations. Alphabet suffered its worst single-day drop on record, Amazon reported negative free cash flow due to heavy AI infrastructure spending; Intel (INTC) plunged nearly 29% following a dismal outlook, fueling widespread panic the massive, debt-fueled AI CapEx boom is becoming unsustainable (as we've foreseen). Meanwhile new-era tickers are just down with the outgoing tide; no problems per se; and probably more attractive is my take for now. Market X-ray: finally wrapped-Roctober with harsh reality check surrounding Big Tech AI capital expenditures. Tech giants Alphabet and Amazon reported staggering increases in AI infrastructure spending, but not positive cash flow. Investors are growing deeply impatient for tangible revenue returns on these massive investments; unlike our small (also struggling but not over-valued we must note) cap growth speculations . Intel and Alphabet suffered essentially unprecedented single-day collapses. The consensus on Wall Street for sure rapidly shifted; and the Street 'acts as if' this was new; which it's not. Actually not fun, but has been my theme here for some time now about debt-fueled AI CapEx craziness is facing intense scrutiny, while nosebleed valuations really are getting penalized (often in stocks we once owned but at lower levels and sold for gains too soon but in almost all cases for gains).
|
Comments
Log in or sign up to join the conversation.