Markets face a "macro trifecta" of surging yields, Q3 earnings, and a looming Fed meeting. With mega-cap tech under pressure, investors are pivoting toward energy and niche security plays like Kopin Corp. as oil prices climb.
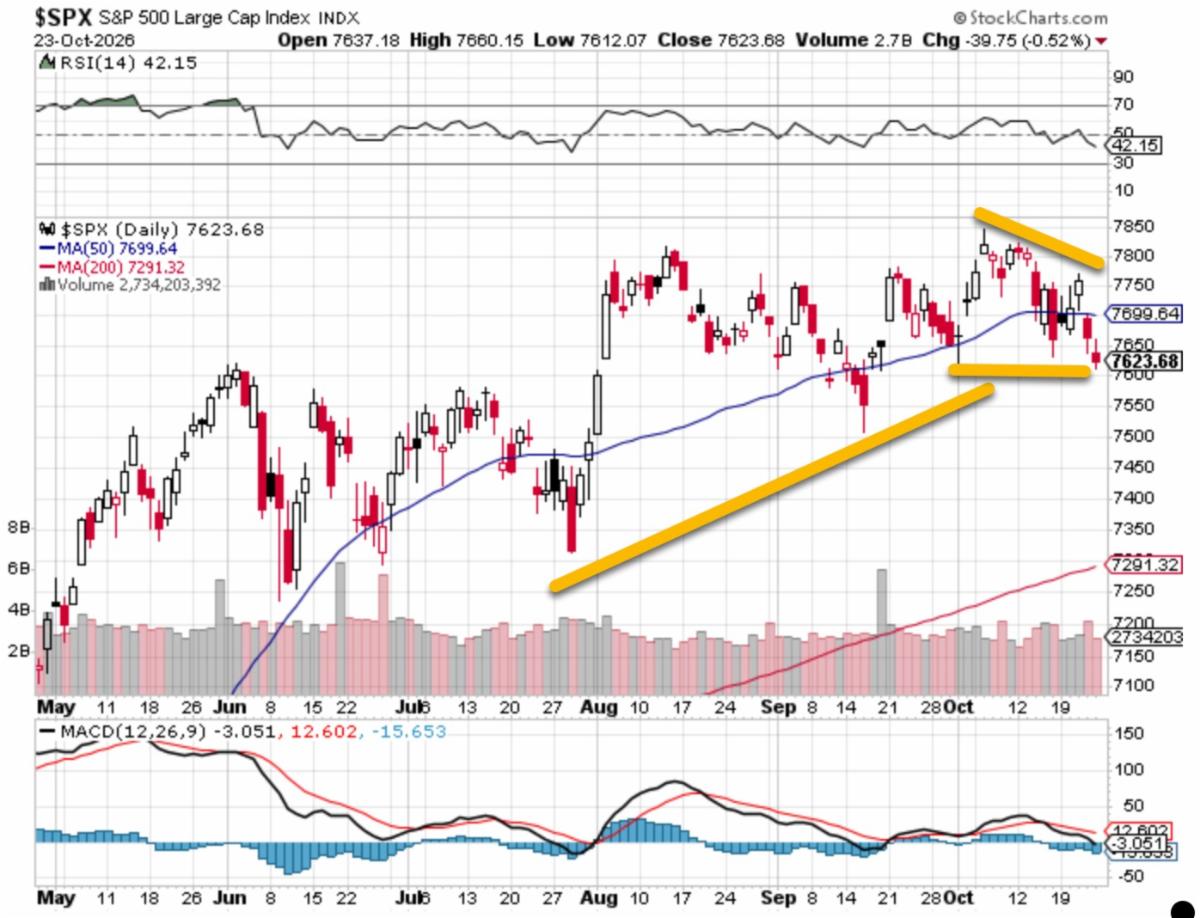
Sort of a gauntlet looms this weekend and maybe for markets; but suspect we'll transit that ok. We're entering next week in a high-strung holding pattern; for the S&P index. It's facing a brutal macro trifecta: surging 10-year Treasury yields flirting heavily with 4.99%, the meat of Q3 corporate earnings season hitting the tapes, and a high-stakes Federal Reserve policy meeting on deck; although I do not expect the Fed to dare to anything now. Some volatility and even violent intraday swings remain feasible, as markets digest Oil prices for sure, combined with geopolitical friction -or action- out of the Middle East.
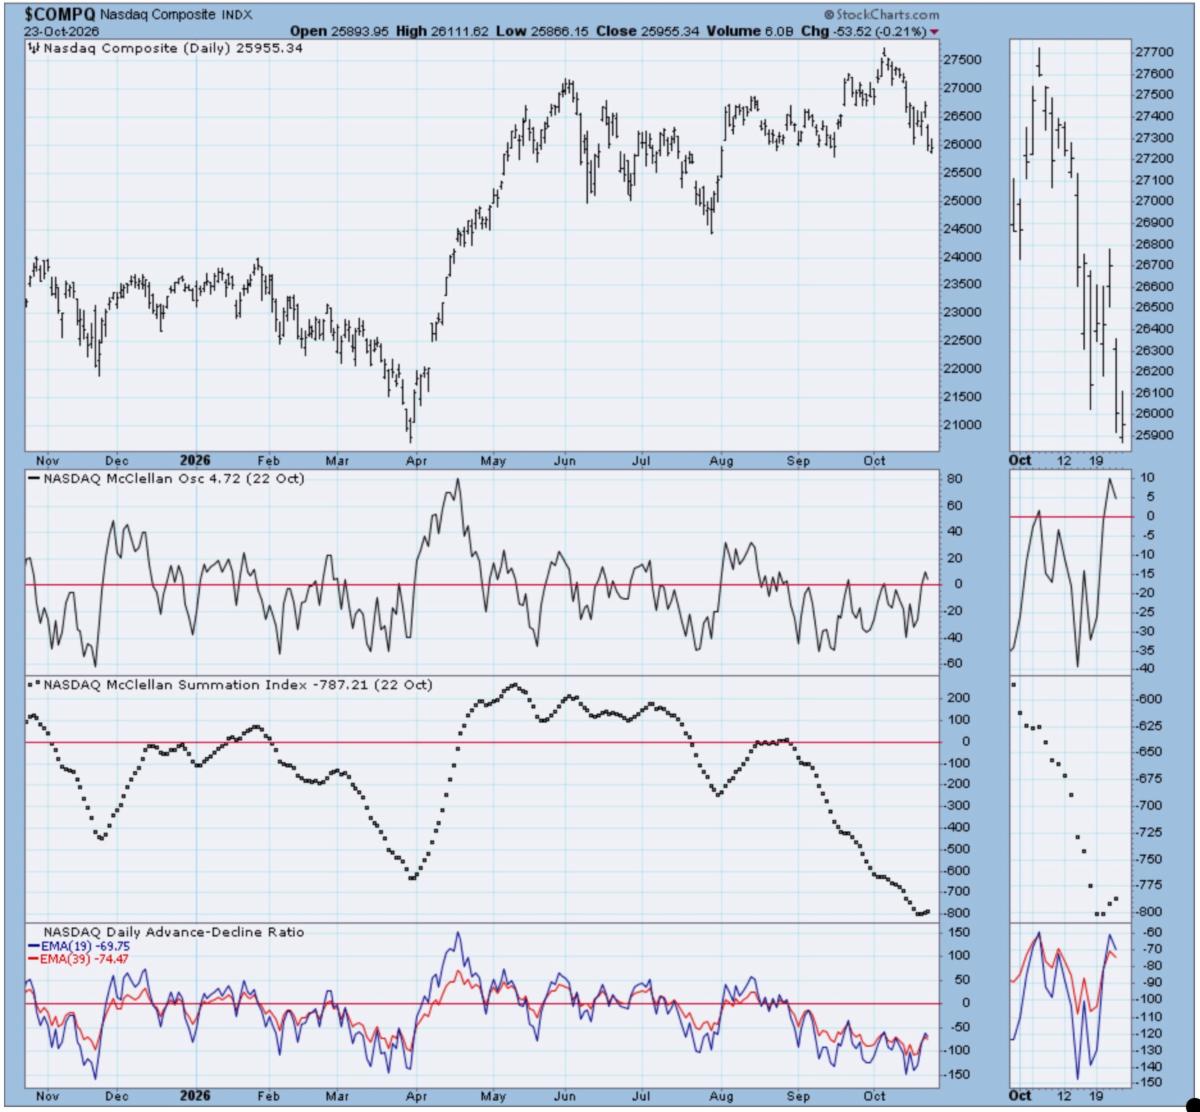
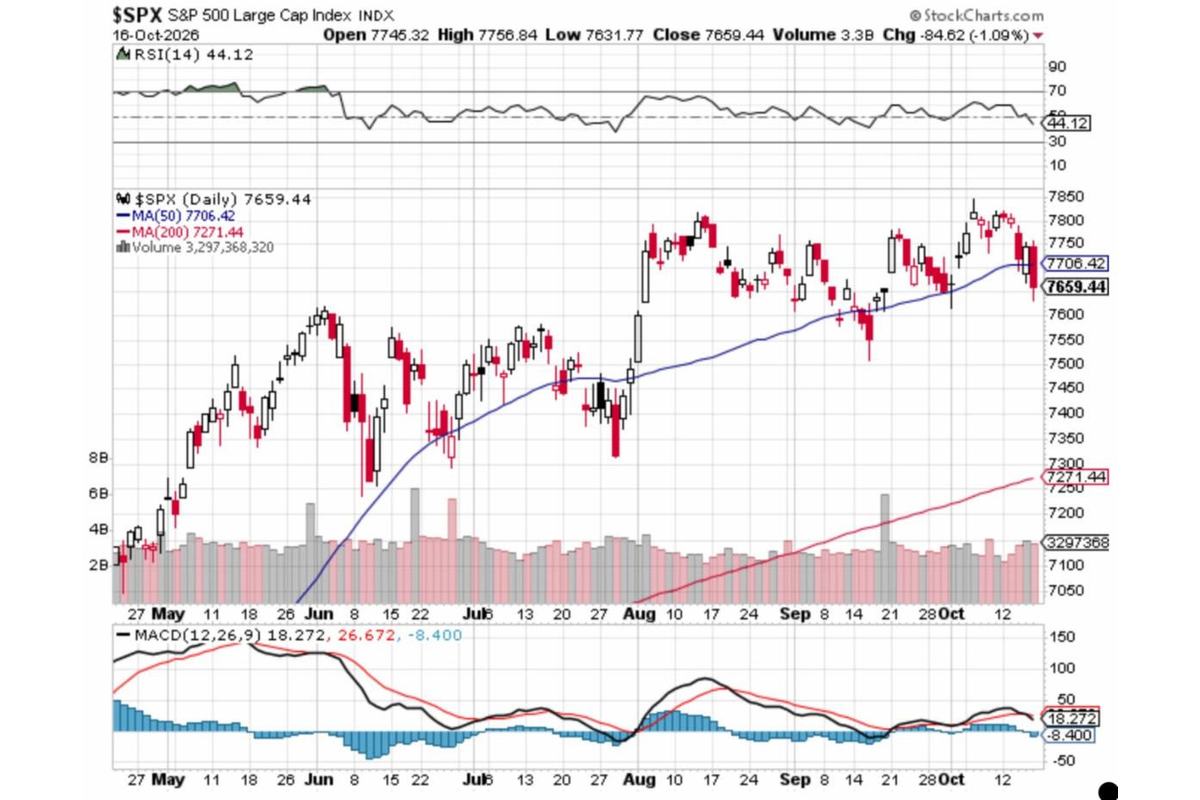
For S&P, it saw a second consecutive week of losses. While mega-cap tech hyper-scalers managed to stabilize after the unsurprising AI-driven bloodbath, the pain broadened significantly; leaving most S&P components in the red. A defensive rotation saw staples and financials taking a hit; Energy caught a bid on the back of Brent Crude charging past 116 a barrel; WTI around 103/bbl.
The European Front: besides the Middle East (where 2 Israeli soldiers were killed by Palestinians Friday), global markets will focus close attention on France this weekend. Paris finally is mounting a massive security presence to protect commercial infrastructure and businesses from widely-anticipated further rounds of intense riots, which again were cost-of-living riots hijacked by rabble and radicals.
So Paris is deploying 70,000 police alongside full military detachments to lock down critical zones (I spoke about city's no-go sections the other evening). If this show of state force successfully contains weekend disruption, we could see immediate stabilization in European sentiment after Monday's opening. It probably would still face some shuffling; but that would be the idea.
Market X-ray: looking through the volatility we retained conviction is primarily security and military autonomous systems; as a distinct focus during the year 'because' I was seriously worried about humongous CapEx hyper-scaler plays that were so expensive and ignoring the coming 'optical/quantum' horizon.
That's still the case... and quietly we have continued accumulating the 'group' of tickers I favor for potential gains in 2027; rather than lamenting the mega or expensive stocks that roared into the hundreds before mostly tanking. And by the way it might help others as some capital diverts to other than the 'megas'.
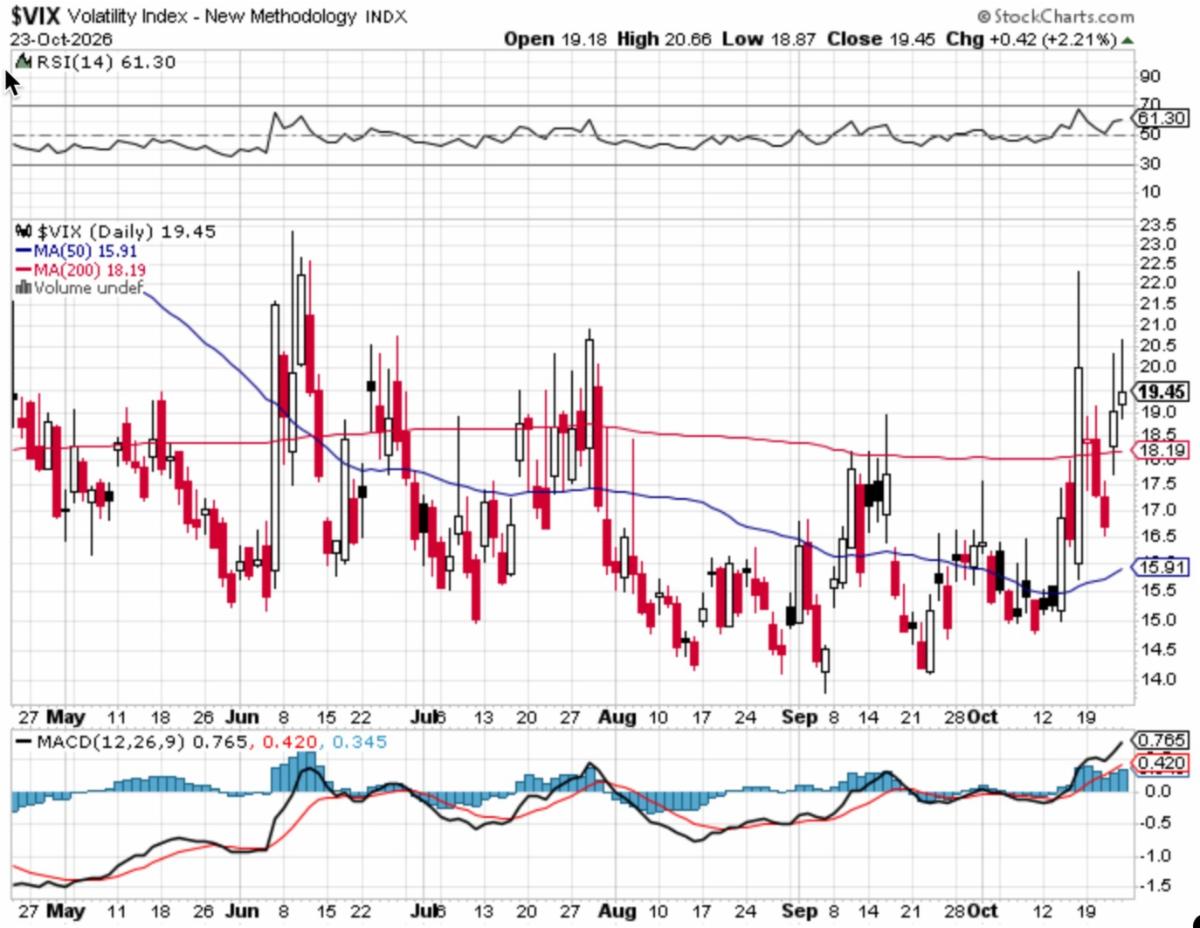
Expect elevated volatility (VIX expansion) and violent intraday swings as the market digests geopolitical friction points out of the Middle East. Hopefully we'll at least get through the weekend with France not falling apart anew, and resiliance from more European leaders who are increasingly recognizing the actual threat (probably did privately, before). Overall shuffling rotation persists.
Meanwhile, macro pressures aren't fun; they created the 'rektober' cliff-diving; but also created ideal entry windows to quietly accumulate additional or niche (optimistically) alpha generators: Syntec Optics (OPTX) for very recent Space Force reconnaissance positioning deal; Palladyne AI (PDYN) for industrial robotics software infrastructure (and its deal with ISI.. Israel Aircraft Industries; to license and build certain drones in the USA), and Kopin Corp. (KOPN) for both helmet or FPV next-generation micro-displays and of course the microLED interconnect that will be shown in Las Vegas at CES. It's easy to say 'sit tight, ignore broad index noise, or war reports' and assemble possible gems for 2027; but that is basically where things are at for the moment; barring complete calamity...um.. yeah I know, the mid-terms are not far away now (early voting already began).
Bottom-line: 'the market' pricing-in 'peak earnings' for the mega-caps clearly in the realm of what I've had to say for months; but I'm not relishing it since for sure it turned into a 'Bordello raid' that stripped good affordable tickers along for the slide, after an earlier year nice ride. Notably most we're in do not have a debt problem or known need for capital (never know for sure of course); so a sprinkling of them persists as well as expectation to continue accumulating in periods of weakness, providing of course there's not a global meltdown.
The macro has many variables (known unknowns that you all know by now ya know) but for this weekend, with France (finally) deploying counter-terrorist as well as conventional military and National Police (who shouldn't have been let alone to confront the rabble last week) into Paris and other major metro cities; well it should be effective containing new chaos irrespective of political views.
As an aside, I hear people talking of 'stagflation'...well that's probably a thing again; but it doesn't apply generally ... you'd need Oil declining as cost-push or Oil-based inflation is the core issue; and you can avoid a recession if the war comes to an end; and nothing will be solved by the Fed hiking rates. Markets are already worse than they likely would have been given the prior hike; credit market ease and access matter; Fed attitudes against that change dynamics in a significant way (for people and companies 'needing' to borrow); so hence the governance supposed to contain price levels, actually fed the flames a bit.
I'm tired; quite a week just past; let's leave it at that.. enjoy the weekend!
Gene
Disclosure:
This is an excerpt from Gene's Daily Briefing (distributed nightly), which typically includes videos as well as more charts and analysis.

Comments
Log in or sign up to join the conversation.