
The dollar has eased modestly lower against certain currencies, while extending gains vs. others. Overall, the greenback holds firm with long-dated bonds under pressure. This should keep the pressure on major FX pairs like the EUR/USD and AUD/USD, gold and potentially indices despite short term data-driven volatility.
Dollar supported by yields as markets await US data
Yesterday’s disappointing consumer confidence and JOLTS figures weighed on the greenback, although the resulting decline in front-end yields was relatively modest. Today’s US economic calendar highlights include ADP employment report and PCE inflation data, which should provide further clues on the Fed’s next move, with nonfarm payrolls to come on Friday.
Meanwhile, the sharp sell-off in longer-dated US Treasuries continues to weigh on global risk appetite, offering underlying support to the dollar. This is likely to limit the scope for a meaningful correction in the greenback, even if incoming data disappoints.
Attention now turns to September ADP employment and August personal spending and PCE inflation. Core PCE inflation is expected to accelerate from 0.2% to 0.3% month-on-month. Although PCE is the Fed’s preferred inflation gauge, markets may place greater emphasis on the September CPI report due in a couple of weeks. Nevertheless, a stronger-than-expected core PCE reading could push October rate hike pricing higher again.
Eurozone data reinforce stagflation concerns
The EUR USD exchange rate broke below its summer lows yesterday before recovering some ground this morning. While dovish-leaning remarks from ECB President Christine Lagarde have added to the euro’s woes, the recent decline has been undoubtedly driven predominantly by dollar strength rather than any fundamental deterioration in the single currency.
However, this morning’s economic releases from the eurozone have done little to improve the outlook, with a combination of rising inflation and weakening sentiment reinforcing concerns about stagflation. The renewed recovery in oil prices, amid a lack of progress in US-Iran negotiations, adds another complication for the region’s economic outlook.
French inflation accelerated sharply to 3.0% in September, well above expectations, largely reflecting higher energy prices. The renewed inflationary pressure threatens to erode household purchasing power just as consumption is weakening, while higher borrowing costs are adding to the country’s fiscal challenges.
Germany offered a somewhat more encouraging labour market picture, with unemployment falling by 67,000 in September, taking the number of unemployed to just below 3 million for the first time since June. However, regional inflation readings suggest that German CPI is also picking up, with the national rate potentially returning to around 3.1–3.2%.
Italy’s figures were more concerning. Consumer inflation surged to 4.2% year-on-year in September, up from 3.3% in August and significantly above the 3.8% consensus forecast. At the same time, consumer confidence deteriorated sharply, while business sentiment weakened as renewed caution in the services and construction sectors outweighed a modest improvement in manufacturing.
Taken together, the latest figures highlight the eurozone’s increasingly difficult trade-off between containing inflation and supporting an economy already showing signs of strain.
EUR/USD technical analysis
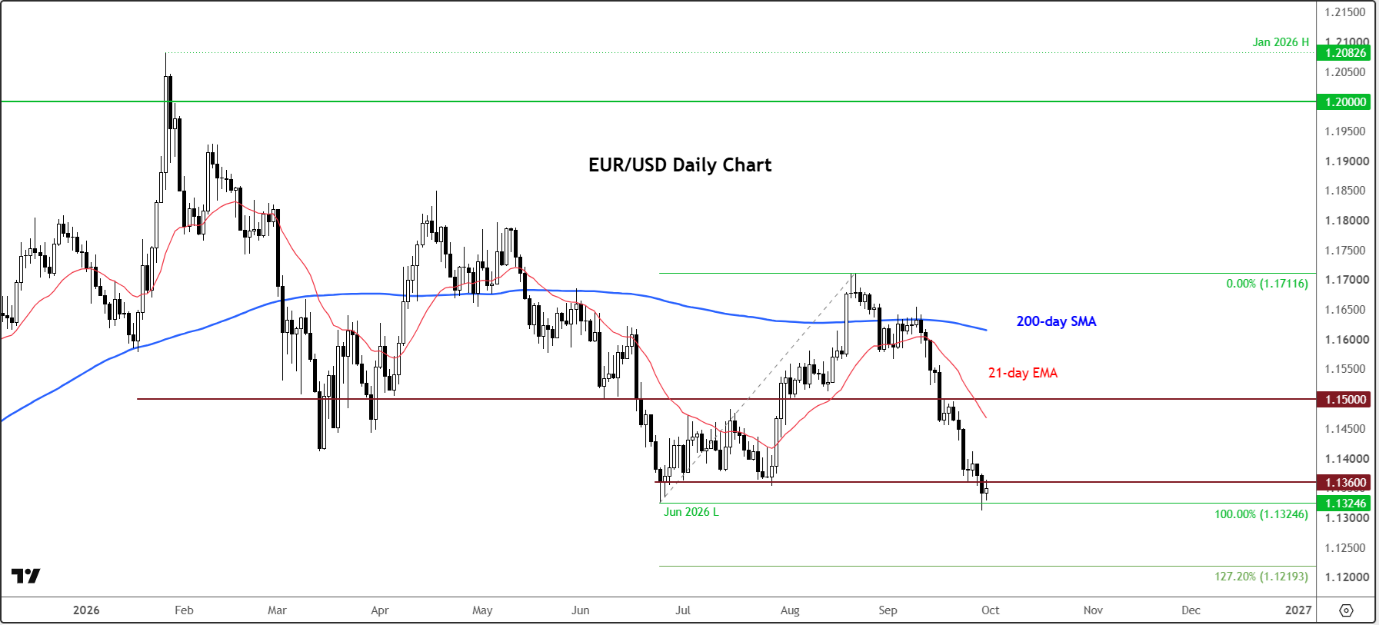
The EUR/USD has met its main downside target i.e., liquidity below the summer lows of around 1.1325. Will it decline further remains to be seen and will depend pretty much on the bond markets. From a technical perspective, a potential closing break below 1.1325 could see the pair start its next leg lower towards the 127.2% Fibonacci extension level of the last upswing that begun in June, at 1.1220. Resistance is now seen at 1.1360ish and then 1.1410 area, followed by 1.1500.
Comments
Log in or sign up to join the conversation.