
Markets got run over on Thursday after a nice lift on Wednesday as we all try to sort out how the election results might impact AI, the war, energy prices, and anything else you think is relevant. Since the market got shellacked, it might be worth looking at how some of the alts and niches we review did in the face of a brief (?) market panic.
First, autocallable funds.
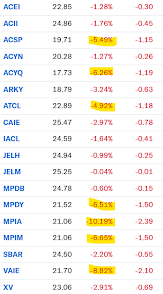
A good starting point for understanding is that the higher the yield, the more volatile the fund is likely to be. If the S&P 500 had food poisoning on Thursday, some of the autocallable funds had flesh-eating disease. The way they have high yields is by referencing leveraged-up versions of the S&P 500 or Nasdaq, depending on the fund.
Managed futures certainly held up better on Thursday; it was generally down on Wednesday too. There was a sharp decline in energy prices after the election, and managed futures was likely long coming into the election.
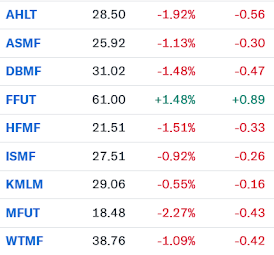
Managed futures builds positions based on longer-term trends than just a couple of days. The Covid Crash is an example where, as a matter of luck, many of the funds were positioned the "right way" going into that event, but that's more the exception than the rule.
Next up, the multi-asset funds we looked at earlier this week.
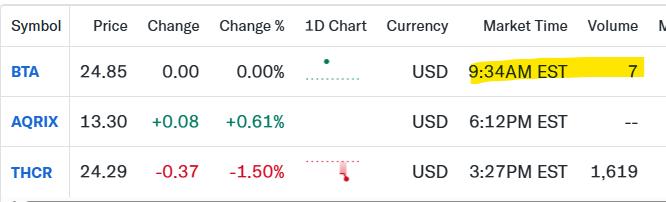
BTA didn't trade, and the fund's website hadn't updated the NAV for November 5 when I looked. Impressive from AQRIX and a solid showing from THCR, maybe better than solid.
This chart could be instructive for whenever the next bear market starts if it hasn't already.
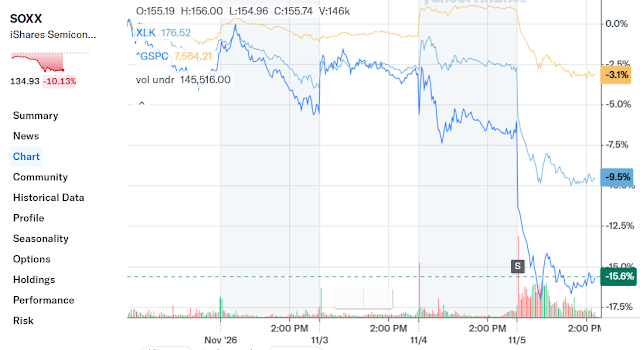
We've talked frequently about not wanting anywhere near the 40-50% tech and tech-adjacent exposure that is currently in the S&P 500. Semiconductors have had a phenomenal run, and while no exposure would have been a bad idea, so too would a market-weight. Bloomberg reported that semis' weight in the S&P 500 has gone from 20% down to 14% with this decline.
There's clearly been an excess in tech and semiconductors; we talked about that many times. There's no way to know when or if there will be a consequence for that excess, but we can observe it and decide not to take on that full exposure. Having just 20-30% in broad tech is still a lot and can provide a lot of growth without feeling every basis point on the way down. The last few days in the chart are a useful microcosm for what a tech-driven true bear market might look like.
I can't stress this enough. No tech is a bad idea. Anyone investing narrower than the broad indexes can easily be underweight; just own less tech. For someone only using broad indexes, there are factors with less tech; there are hedges like BTAL to dial down exposure. It is valid to not believe in any of this too. Whatever happens, all bear markets end, recover, and make new highs. Holding on for all of that is difficult, but it is valid.
Comments
Log in or sign up to join the conversation.