

It's been a rough month for Adobe (ADBE), down 19.6% so far in September, and it's been a tough year for the company too. ADBE has dropped 32.7% in 2026 and appears to be very cheap at a PE ratio that is slightly under 9X. I downgraded it on TalkMarkets on August 26th, and I am upgrading it today.
A Look at the Chart
Over the past year, ADBE has dropped a massive 34.7%, while Invesco QQQ Trust (QQQ) has increased in price by almost 25%. With a market cap of $91.6 billion, ADBE is in the Nasdaq-100, but a better comparison might be to the S&P 500 Technology sector. Technology Select Sector SPDR (XLK) has soared almost 41%. Interestingly, though, software has been weak, with iShares S&P GSTI Software Index Fund of iShares Trust (IGV) down 7.8%.
Looking at the action over the past three years, ADBE has been even weaker relative to these ETFs:
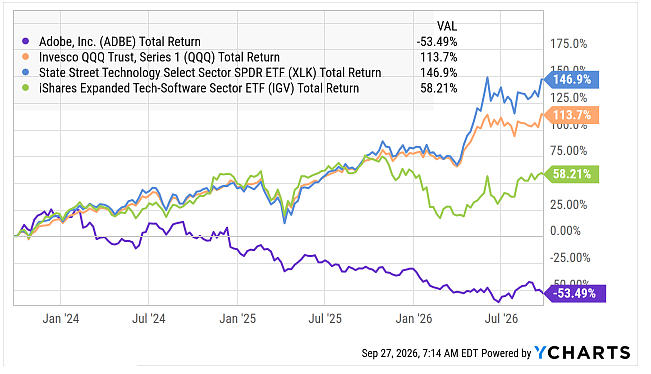
Yes, software has been weak recently, but it has rallied recently. ADBE is now down 32.7% from its 2026 high, while IGV is only 3.9% below its very recent 2026 high.
Looking at the chart of Adobe over the past year, it looks like it may have posted a low in mid-June:
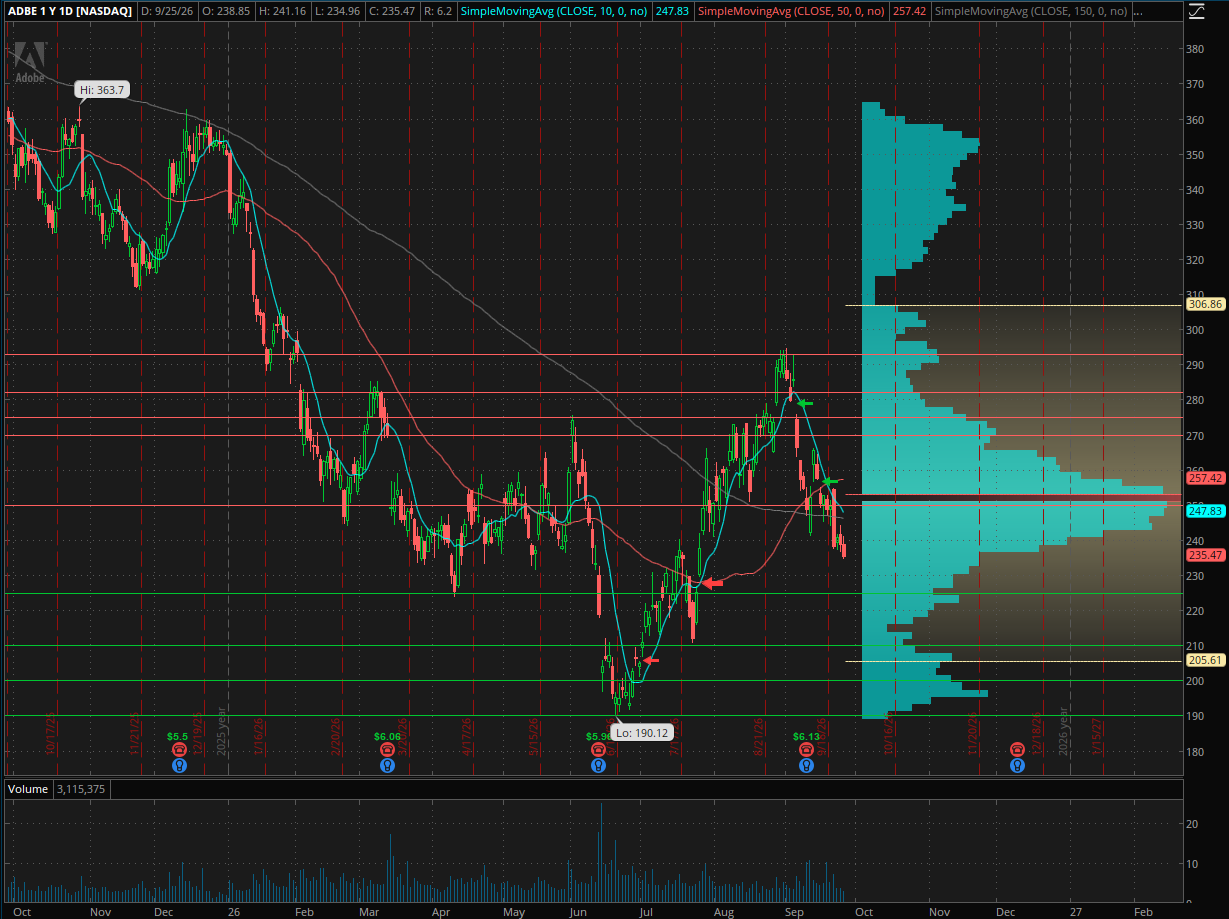
The low near $190 was set on June 18th, which was right after my original Buy article and after fiscal Q2 financial reporting. The recent peak in early September filled the open gap from early February. There are still open gaps below near $225 and near $206, and there are open gaps above near $257, where the 50-day moving average is, and near $284. Both of these levels would represent solid gains but still be below the year-end price level I projected in June. I see support at $225, which would match the low from April and would also fill that first open gap below the current price.
The Valuation Is Too Low
The company will report its fiscal Q4 in December (on the 9th). Its fiscal year ends in October, and the current EPS projection according to Koyfin is $24.48, which would be up 17% from FY25 and in line with the guidance announced on the Q3 call. The outlook for FY27 is for 13% growth to $27.67. and the outlook for FY28 is another gain of 13% to $31.38. Based on the current outlook, the PE for FY26 is 9.6X.
Looking at revenue, it too is growing currently and is projected to grow. The company's enterprise value is similar to its market cap, and the Price to Sales for ADBE works out to be 3.4X. This is the lowest of the top 10 holdings in IGV currently by far. These 10 stocks, which include ADBE, have a median of 13.6X enterprise value to trailing sales.
Many investors use EBITDA for calculating valuation, and the analysts are projecting growth in EBITDA too, though EBITDA growth is lower than EPS growth or revenue growth. Using the adjusted EBITDA forecast for FY26, the company trades at just 7.3X.
One of my checks for valuation is price to tangible book value, which is not helpful here due to the low book value of Adobe due to aggressive share repurchases in the past. With $14 billion in goodwill due to M&A, the tangible book value is negative. The company is not alone among the large 10 software companies in IGV, as five others have negative tangible book value as well. This metric is helpful to project downside risk. Given the company's very low valuation and strong balance sheet, investors should focus on potentially lower earnings to gauge downside risk.
Why I Am Upgrading Adobe
I first pointed here to Adobe in mid-June, suggesting that it should do a magic trick of implementing a dividend. It has not done so, or I would be a lot more optimistic. It has done a few things, though, since then:
Named a new CEO
Reported fiscal Q3 results
Announced 2 acquisitions
It was a bit of a surprise to investors when Shantanu Narayen announced in March that he was intending to resign the CEO position he has held for over 18 years. The company announced on September 3rd that Anil Chakravarthy will become CEO on December 1st, with Narayen becoming Executive Chair. The pending CEO has been president of Adobe's Customer Experience Orchestration business for over six years. Before Adobe, he was CEO of Informatica and has worked at several other software companies. He participated extensively in the fiscal Q3 call on September 10th. This seems like a normal transition to me, and hopefully the CFO transition will go as well. When I wrote the buy recommendation, I pointed out that the CFO had resigned, and there is still an interim CFO.
Fiscal Q3 results were strong, with revenue and earnings growing. The company called out growth of AI-first ARR of $650 million, up 150% year-over-year. It reported monthly active users in excess of 1 billion., and a doubling of Acrobat AI assistant usage. The company did repurchase a lot of stock again, buying 9.5 million shares:
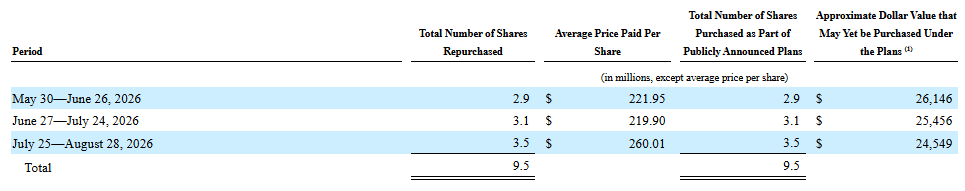
Some of these shares were purchased below the recent close, but, again, I would rather see the company begin to pay a dividend like many of its peers. For the first three quarters of FY26, it spent $6.8 billion on share repurchases, which is down from the first three quarters of FY25 and also less than the operating cash flow of $7.6 billion.
M&A is nothing new for Adobe, and it purchased start-up Rilo just ahead of the fiscal Q3 report. Rilo, based in India, is an AI workflow automation company. It also just announced the closure of the purchase of Topaz Labs, which was announced in late June. It explained then that the acquisition would help with its strong demand for AI products. I don't see either of these as creating big risks or large opportunities.
While the price may drop a bit more, the chart looks like a bottoming process. Perhaps the market was disappointed by the naming of Chakravarthy as CEO, but it seems to make sense and Narayen will transition to Executive Chair. AI, seen as a threat to ADBE by some and as an opportunity for it by others, hasn't yet seen a company visibly attacking the business of it.
The valuation seems very low. My outlook for a year out suggests substantial potential appreciation, and the strong balance sheet and low valuation should provide limited risk to the downside. On June 15th, I shared a target for year-end of $301 based on attaining a PE of 11X based on the FY27 projected EPS. Updating this today, the target for year-end would be $304 due to the higher EPS projection. Year-end is just three months away, and I am not confident in forecasting a 29% gain, though it could happen.
Today, I want to share a one-year outlook. Using 12X the FY28 projected EPS, I get a price of $376, which would be a gain of 60%. Not bad for a stock that qualifies for Magic Formula Investing! With a new CEO, there could be an adjustment lower in projected EPS if the company wants to reset the bar, so investors should be cautious on this next earnings report, which takes place a few days after the new CEO assumes the position. My target, though, does not include the potential implementation of a dividend, though I continue to believe that this could boost the stock. $376 would be 10.7X enterprise value to projected FY27 EBITDA, which is reasonable for a growing company like Adobe.
Comments
Log in or sign up to join the conversation.