
It’s not the primarily the deficit, nor is it just oil.
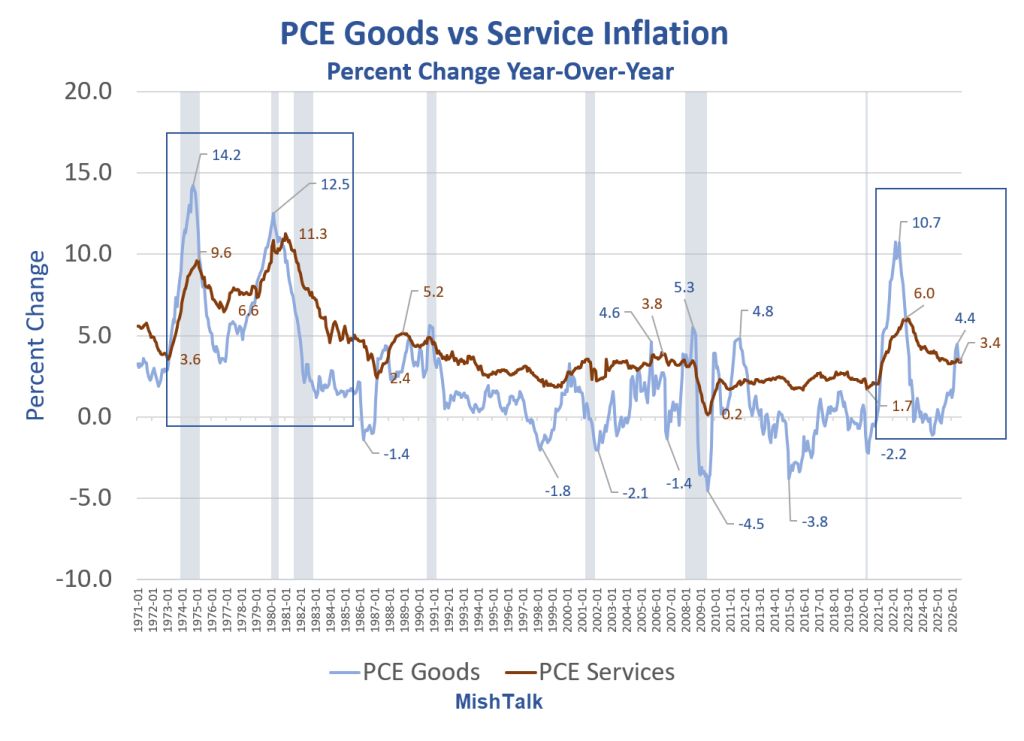
We are witnessing something we haven’t seen since the stagflationary 1970s and 1980s.
Hat tip to Jim Bianco for inspiring this post.
Let’s hone in on the period between 1992 and 2026.
PCE Goods vs Services Inflation Detail
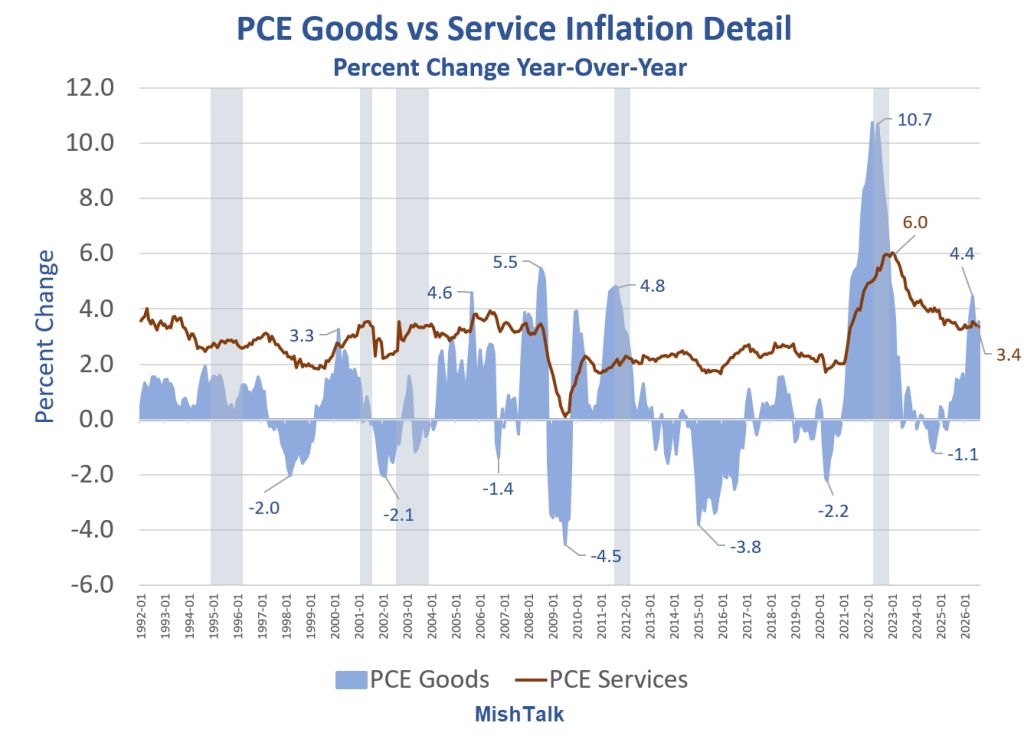
From 1992 through 2020 goods were a moderating factor on overall PCE as the next chart shows.
PCE Goods and Services 1992-Present
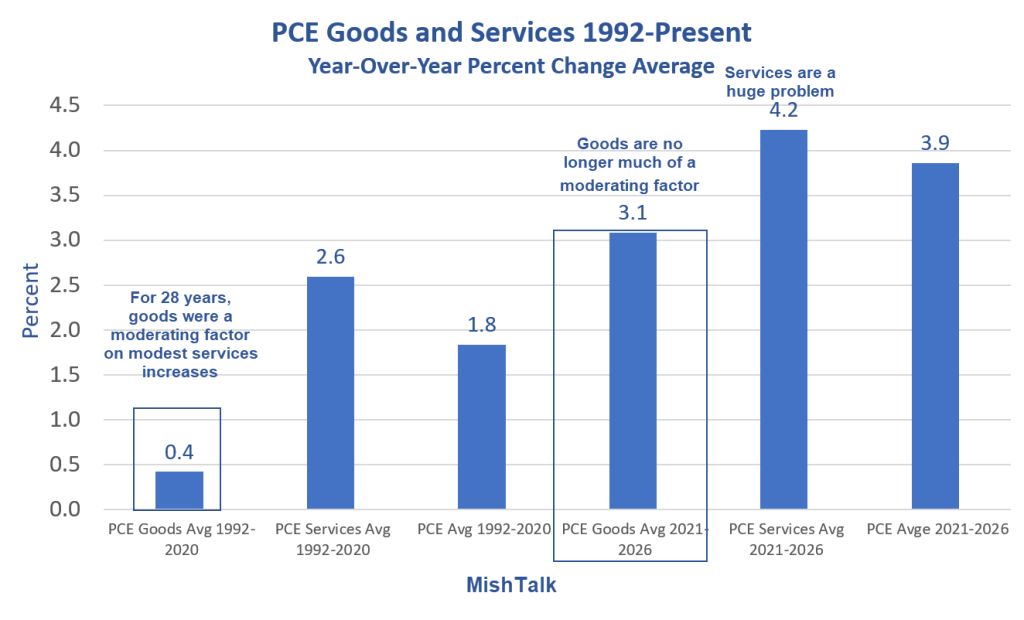
1992-2020 PCE Goods and Services Key Points
From 1992 through 2020 the average year-over-year for PCE goods was 0.4 percent.
The average PCE services 2.6 percent.
The net PCE was 1.8 percent, slightly under the Fed target of 2.0 percent.
2021-2026 PCE Goods and Services Key Points
The average year-over-year for PCE goods from January 2021 to present is 3.1 percent.
The average PCE services is 4.2 percent.
The average net PCE is 3.9 percent, well over the Fed target of 2.0 percent.
Annual PCE Goods vs Services Share of PCE
Year | Goods share of PCE | Services share of PCE |
|---|---|---|
1992 | 37.2% | 62.8% |
2000 | 36.3% | 63.7% |
2010 | 32.3% | 67.7% |
2019 | 31.4% | 68.6% |
2025 | 31.1% | 68.9% |
Even if year-over-year PCE goods falls back to the 1992-2000 average (it won’t), PCE services rate to make the Fed miserable.
Six Structural Issues
Just-in-time manufacturing has ended
Outsourcing to China is no longer in vogue
Trump’s tariffs raise the price of imports
Manufacturing in the US is more expensive
Deportations have led to a shortage of skilled trades, especially construction and housing, but also leisure and hospitality, and agriculture.
Aging boomers need more services, especially healthcare
All of those are structural. Trump is responsible or partially responsible for the first five.
Add the deficit, military spending, and the war in Iran to that list.
Blame both parties for the deficit, but blame Trump for the war and the need for more defense spending.
So, even if oil comes down when the war ends, six structural issues will remain for at least two more years.
Related Posts
October 1, 2026: ISM Manufacturing Expanded in September for the Ninth Consecutive Month
Input prices up 24 months, increasing faster.
October 1, 2026: The War in Iran Is the Biggest Self-Inflicted Political Mistake in Decades
Iran is one of the least popular wars in history.
October 2, 2026: In Big Warning to the Fed, Bond Yields Rise Despite Weak Jobs
The bond market is telling the Fed it wants another interest rate hike.
October 2, 2026: Mortgage Rates Have Largest Weekly Gain in Four Years
Since February, mortgage rates have surged from 6.00 percent to 7.54 percent.
Comments
Log in or sign up to join the conversation.