

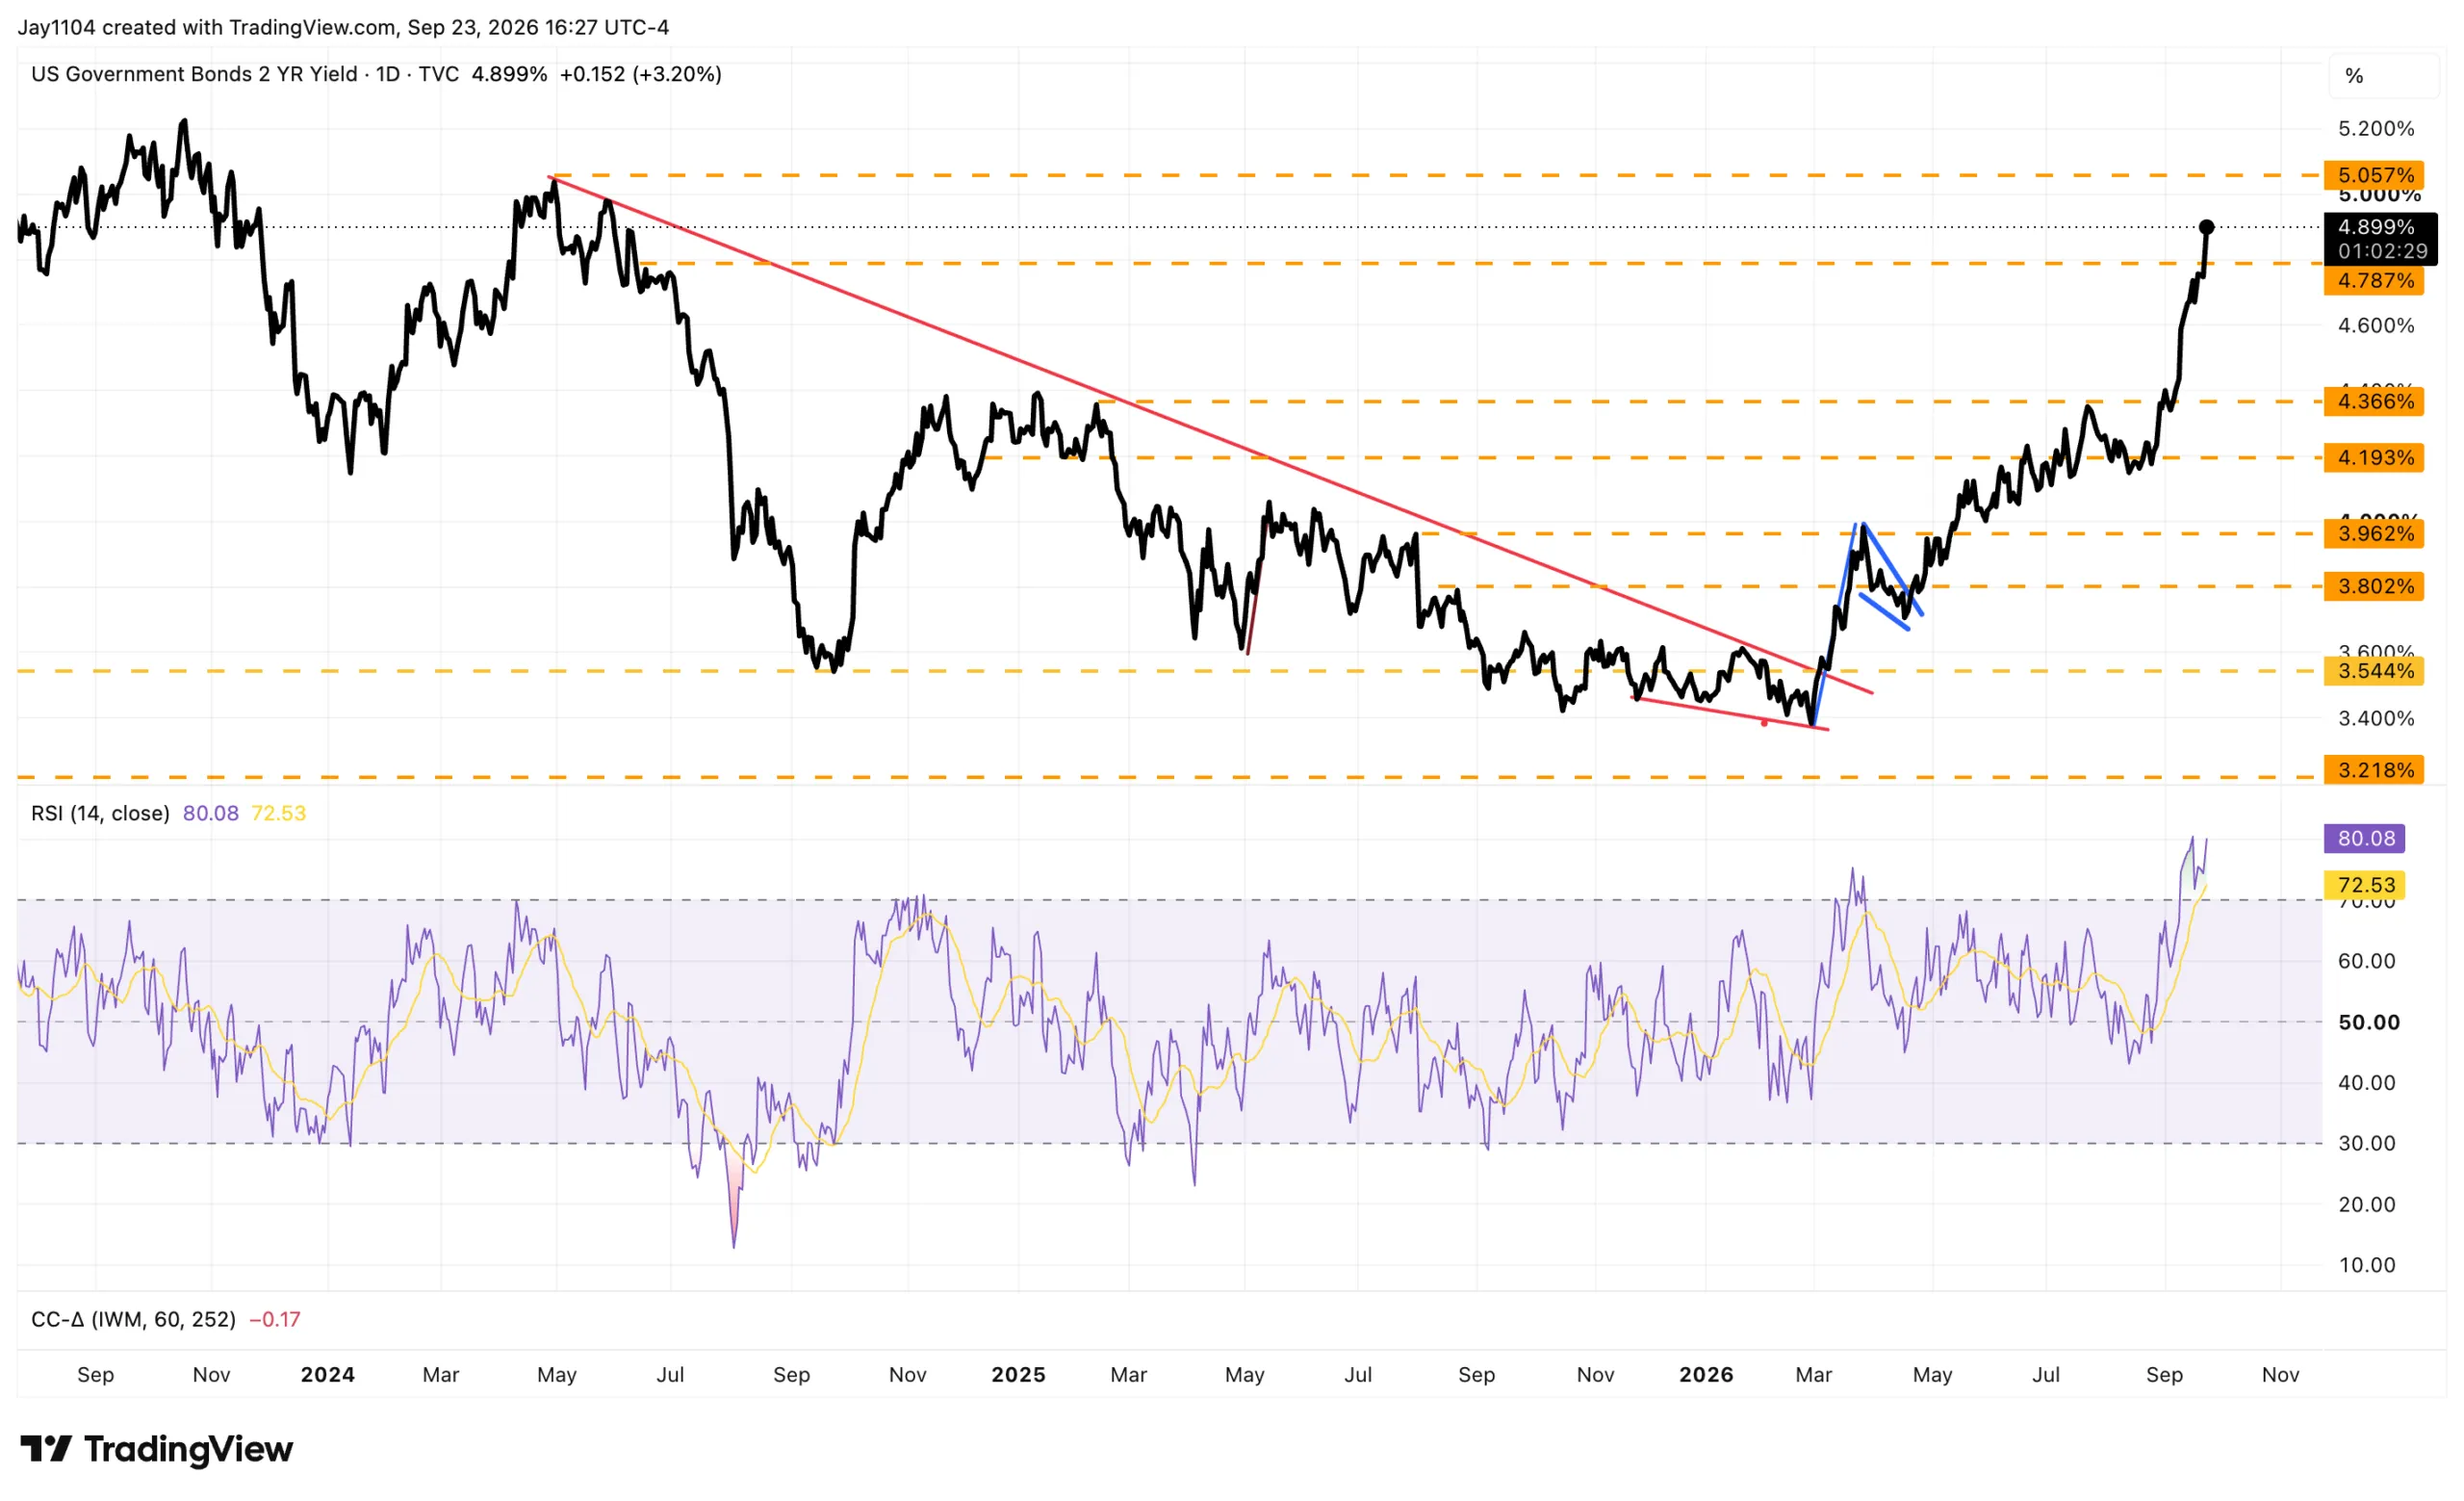
The S&P 500 fell by 75 bps as the 2-year Treasury yield rose 14 bps to 4.89% following a strong S&P Global PMI report. Treasury yields moved higher across the curve, with the 10-year yield rising about 10 bps to close at 5.1%.
The move in yields was significant but, in some ways, not entirely unexpected. What was surprising was seeing such a large repricing in a single day following economic data that does not ordinarily generate this kind of market reaction. At this point, a move in the 2-year Treasury yield to 5% would not seem particularly far-fetched, but then again, I have been talking about that possibility for several weeks now.
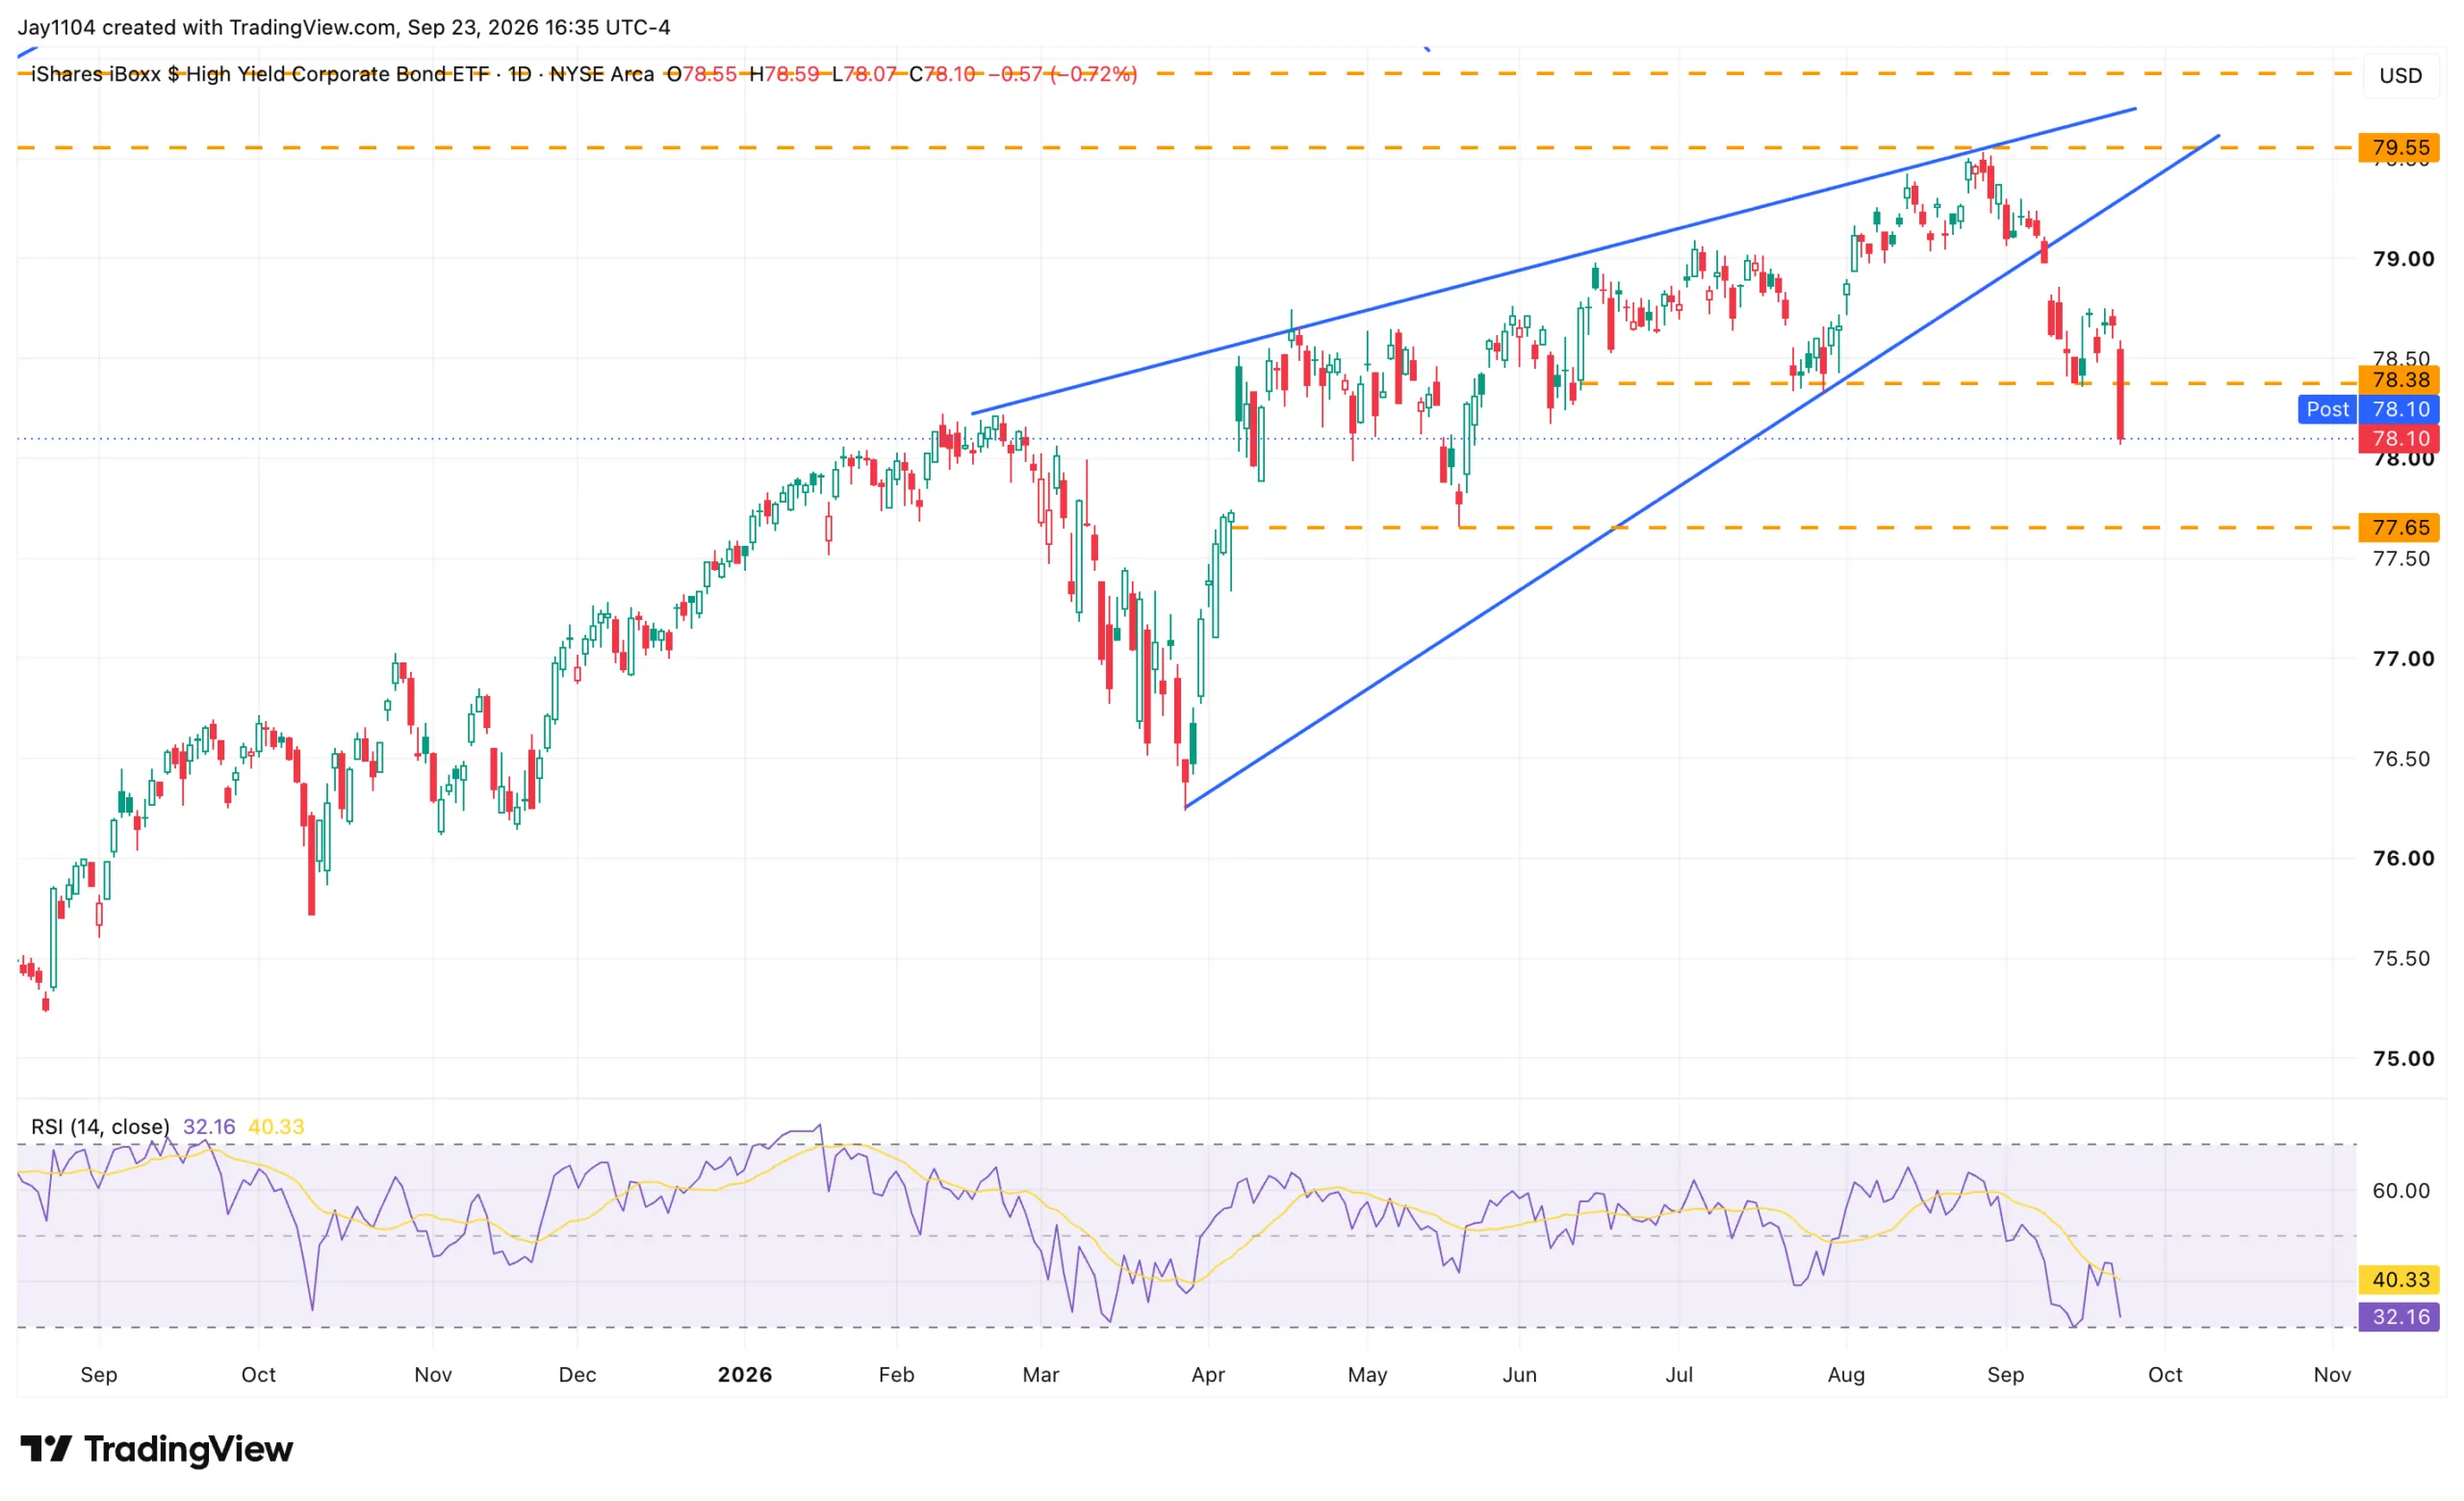
HYG broke below key support at $78.40 today, raising the risk that credit spreads are beginning to widen more meaningfully. This is based on HYG adjusted for its dividend yield.
The breakdown is worth watching because a further decline toward $77.65 could signal additional widening in credit spreads and growing stress in the credit market.
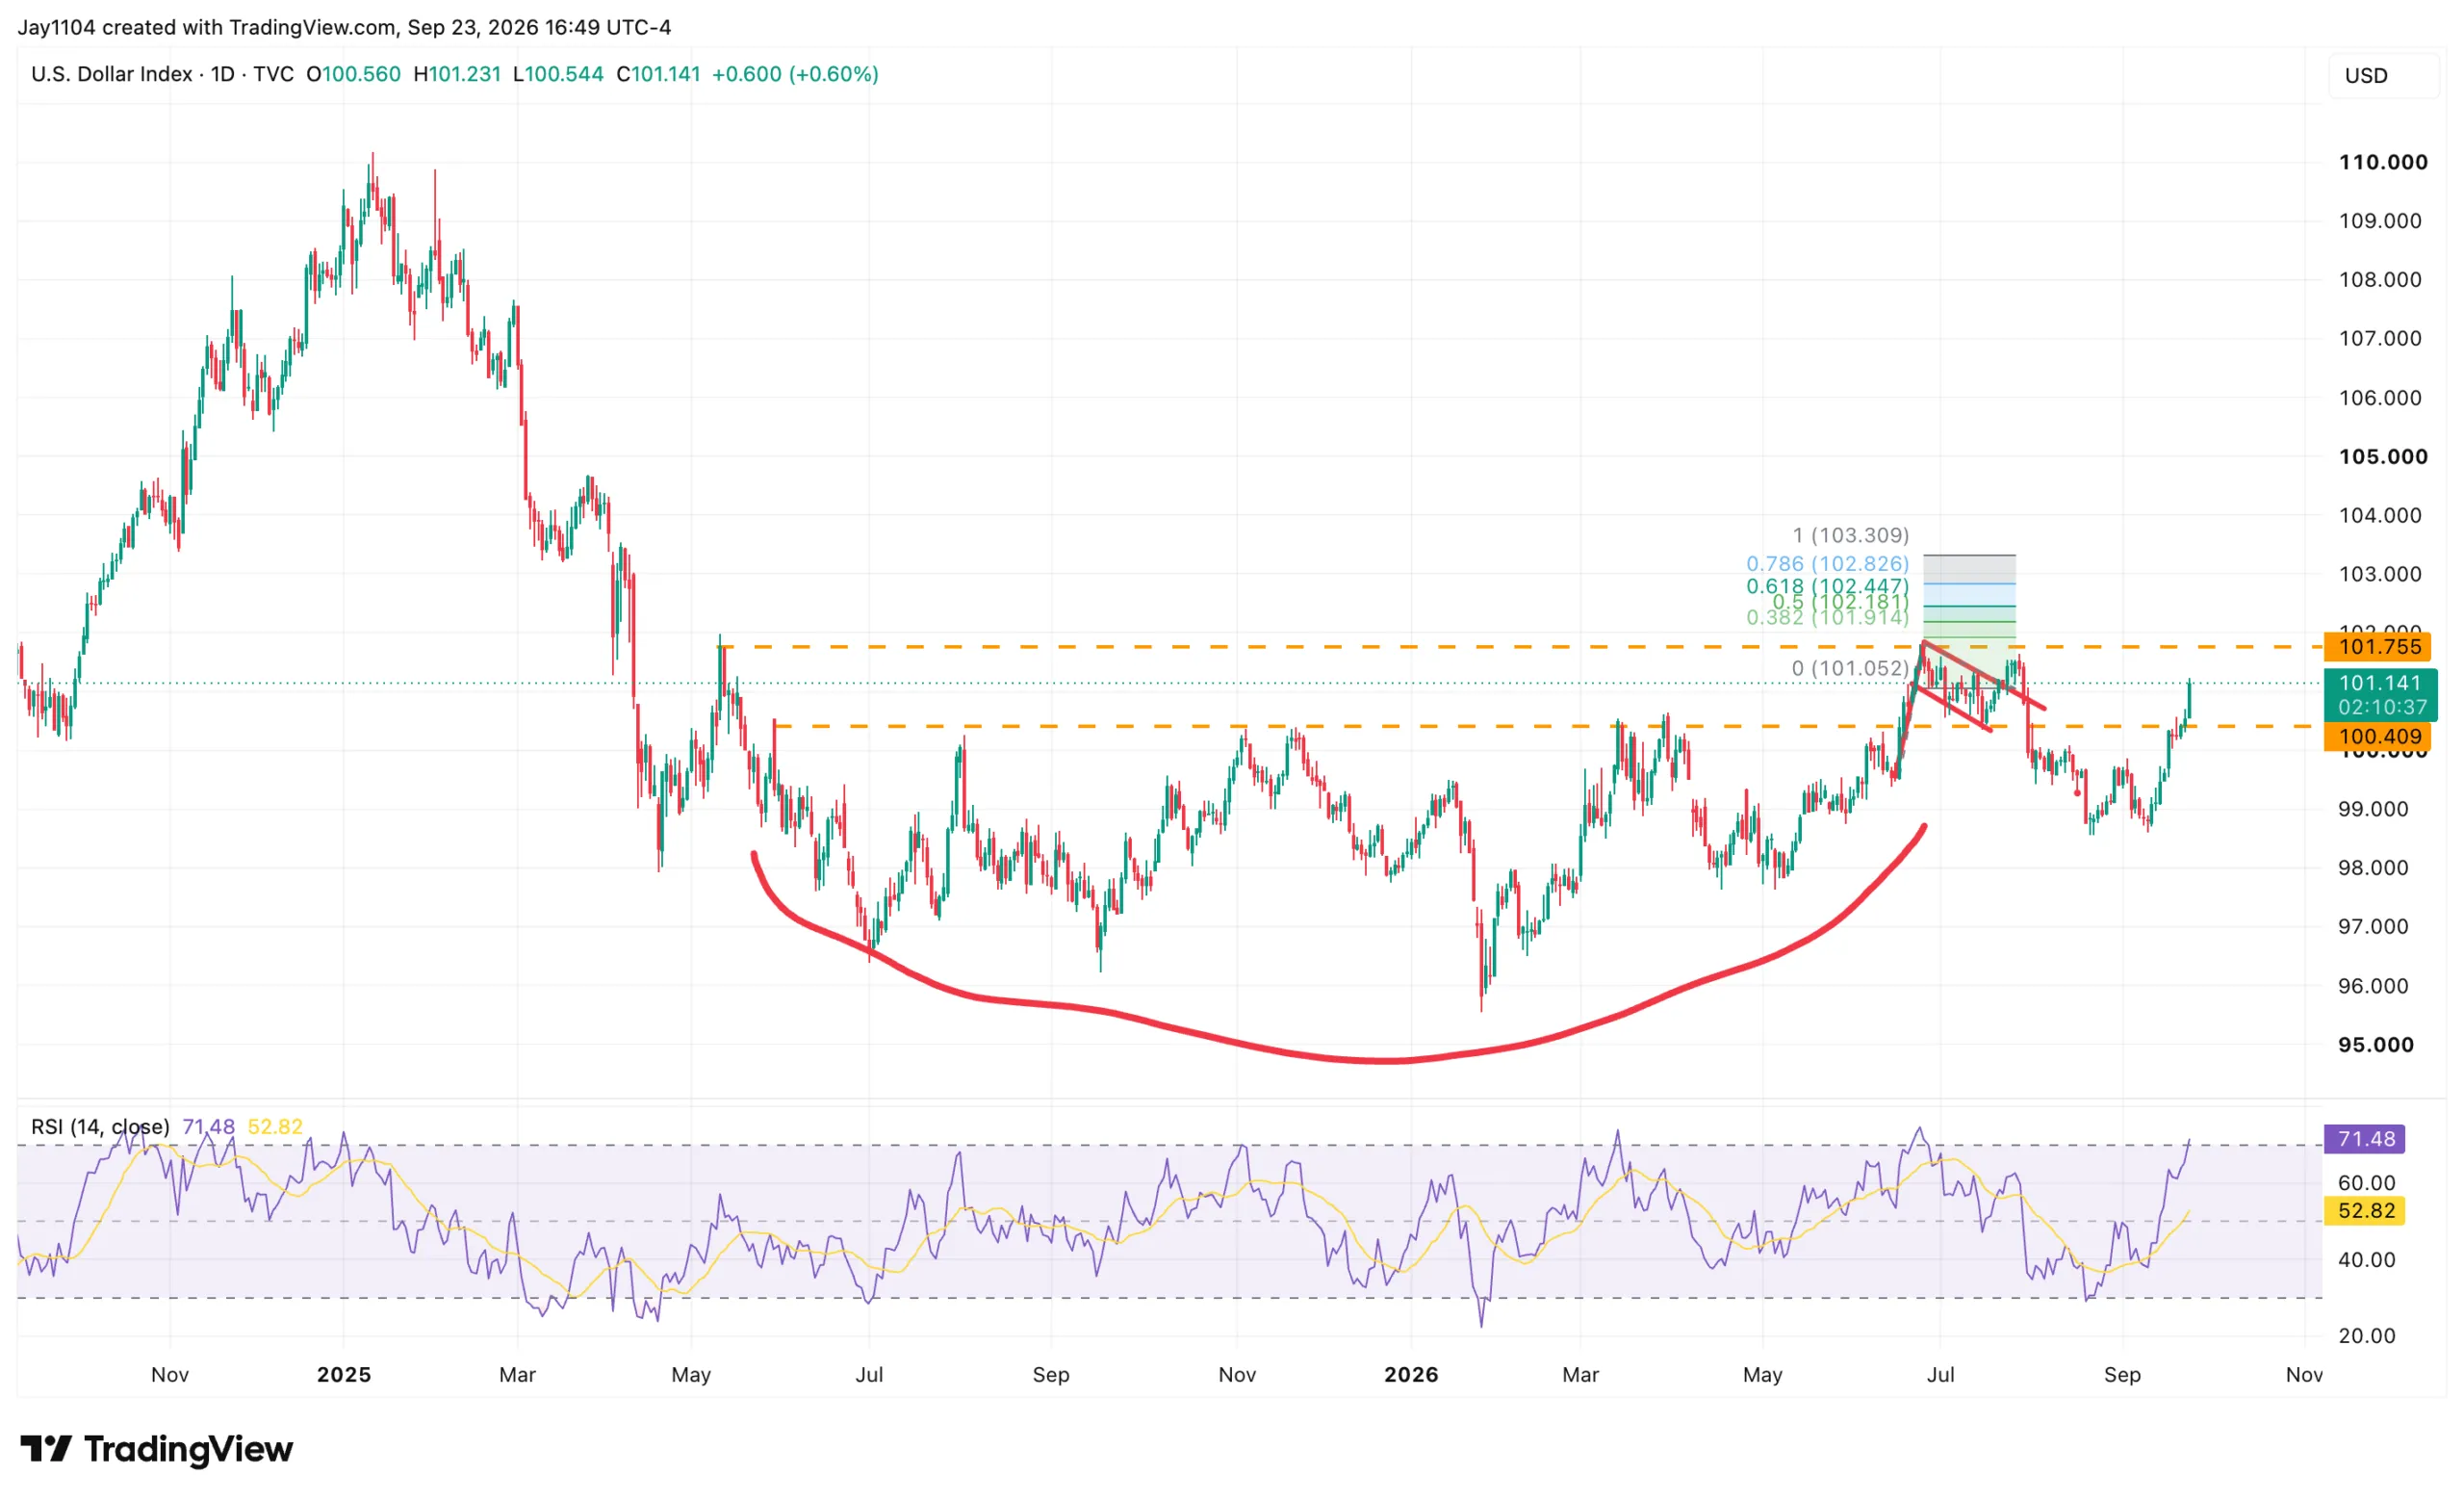
The dollar index also rose sharply today, breaking above resistance at 100.50 and potentially setting up a move toward the 101.80 to 102 region. The stronger dollar makes sense amid rising rates, stronger economic data, and markets increasingly pricing in the possibility of additional Fed rate hikes.
If the dollar continues to strengthen, it could become another important source of tightening in financial conditions, particularly alongside higher Treasury yields and widening credit spreads.
But whether a stronger dollar ultimately translates into tighter financial conditions will depend in part on what happens in cross-currency basis swaps. So far, we have not seen signs that the dollar’s recent strength is transmitting through the cross-currency basis, but that will be important to watch if financial conditions continue to tighten.
We care specifically about this transmission channel because of its implications for global dollar liquidity and, ultimately, the liquidity available to risk assets.
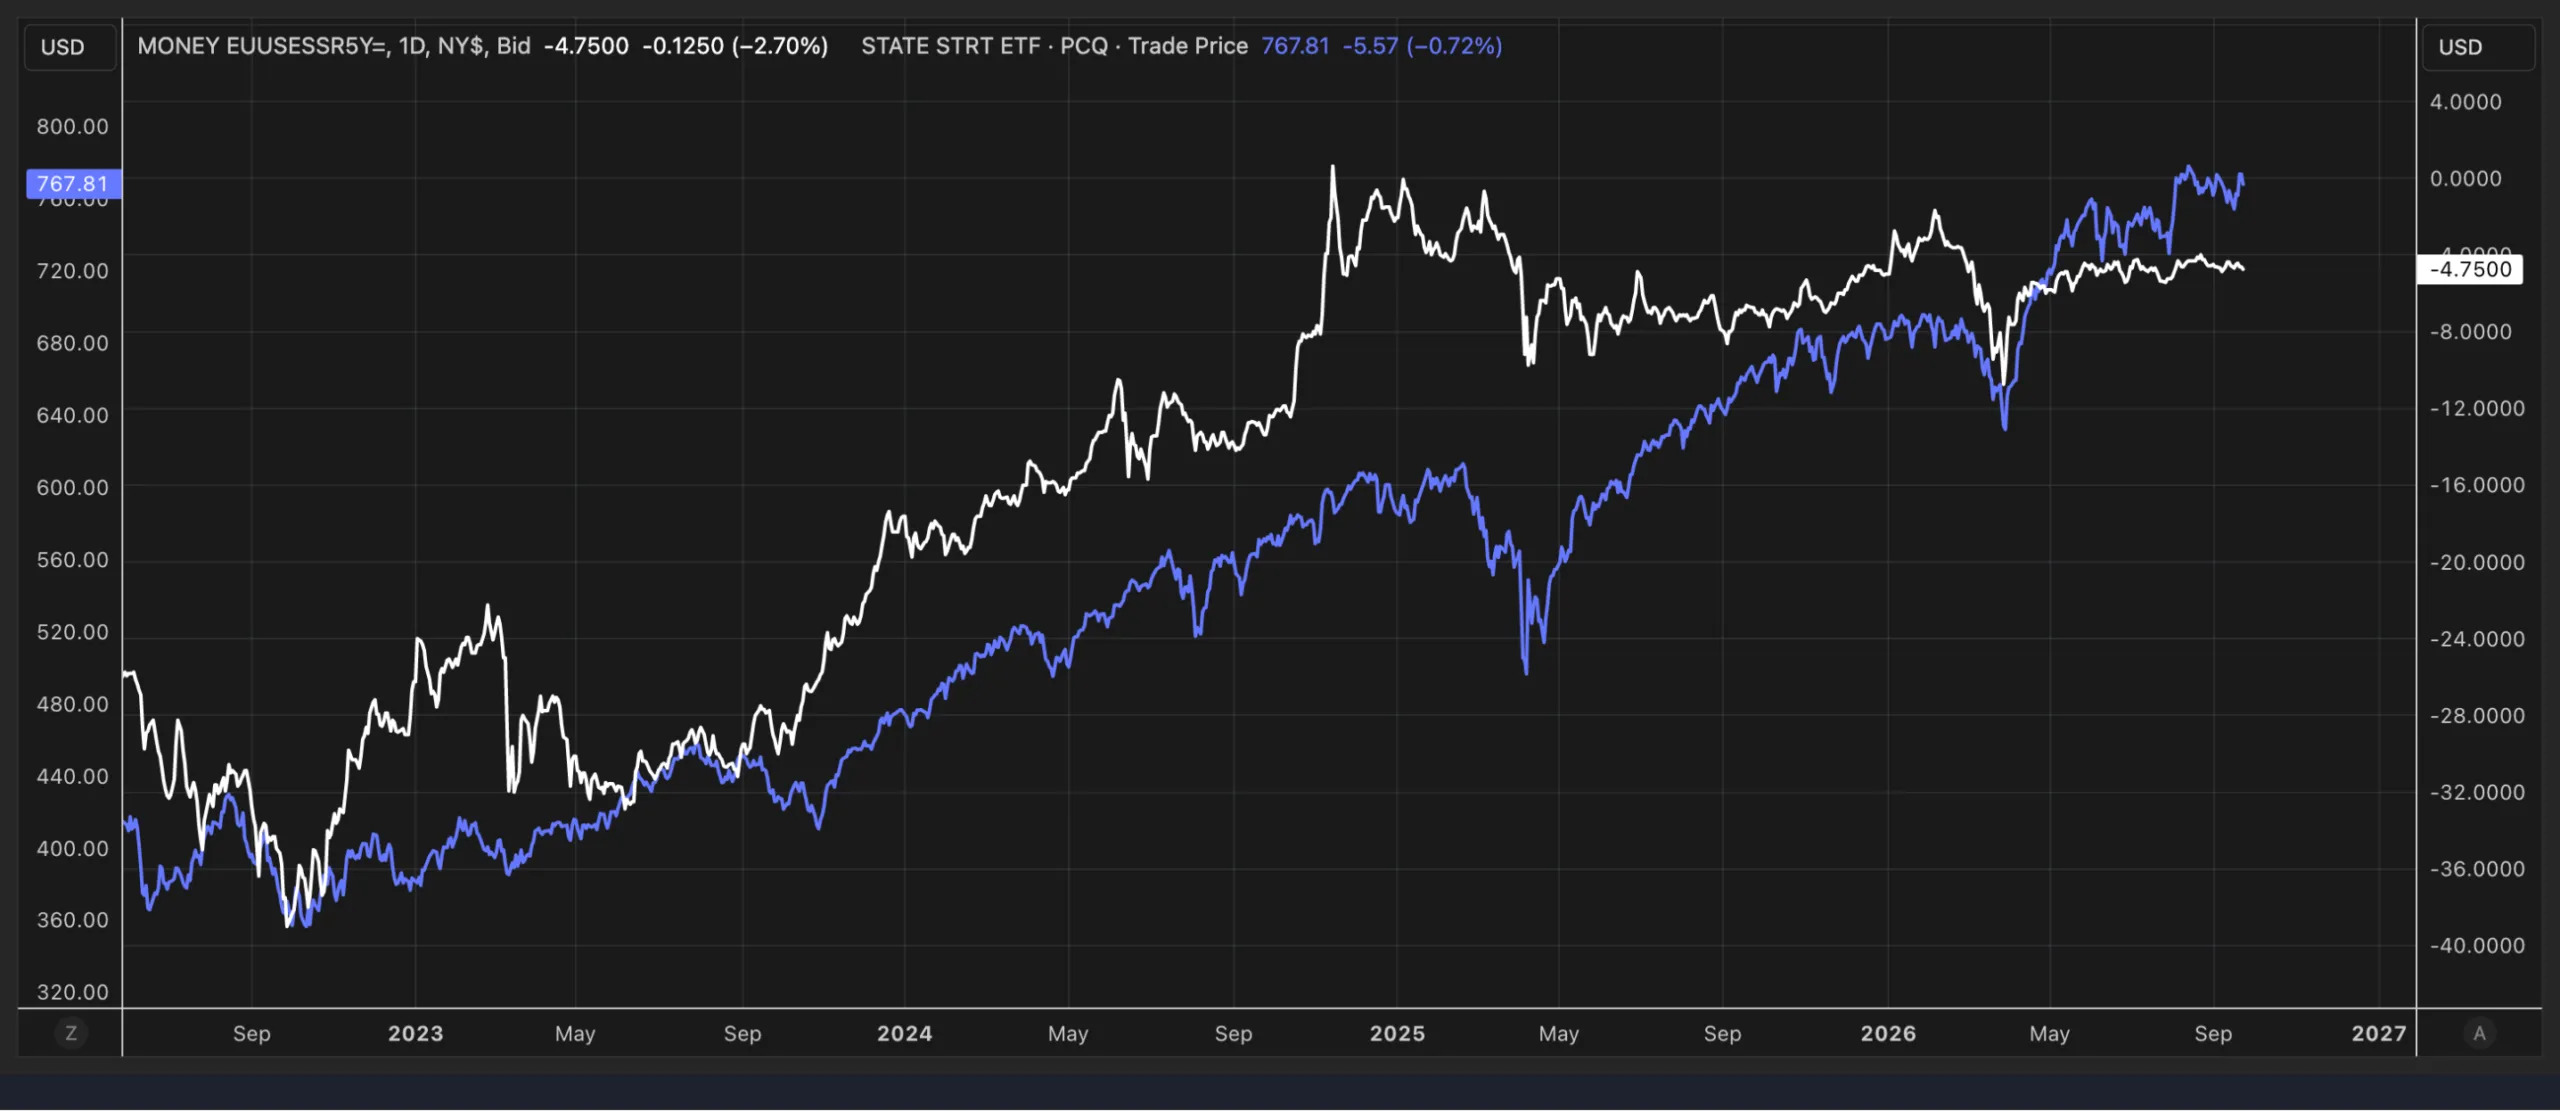
(LSEG)
Comments
Log in or sign up to join the conversation.