

Stocks fell again on November 2, despite the S&P 500 rallying by as much as 1% earlier in the session. By the end of the day, all of those gains had been erased, with the index finishing down around 25 basis points. Volatility also rose sharply following the morning crush, which saw the VIX 1-day fall from Friday’s close of 19.3 to 10.6 at the open, only to rebound to around 18 by the close.
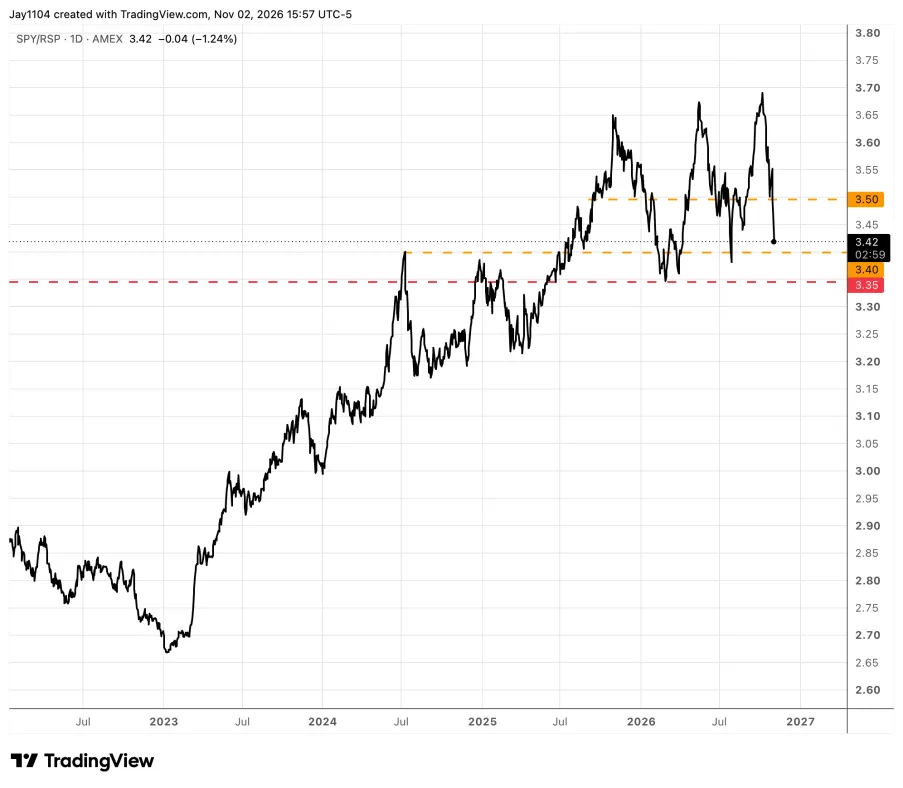
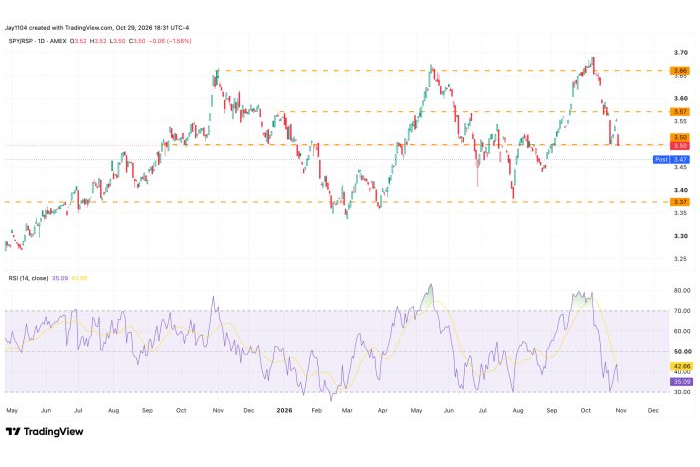
It’s difficult to say exactly what drove today’s price action, with the midterm elections tomorrow, a calendar packed with economic data, and earnings season still underway. However, what stands out is the continued decline in the SPY-to-RSP ratio, as weakness in semiconductors and technology continues to weigh on the headline index.
The big news today, I guess, was that the Treasury Department now expects the Treasury General Account (TGA) to finish the year at $850 billion before rising to $1 trillion by the end of March. The Treasury expects to borrow $800 billion in the January-to-March quarter. I don’t know how it plans to break down that borrowing, but wow, that could mean a lot of T-bill issuance if coupon auction sizes aren’t increased. That’s a significant jump from the $574 billion in borrowing during the same quarter a year ago.
Given the relationship we’ve observed over the past year, the projected increase in Treasury borrowing and the TGA balance could create additional headwinds for market liquidity.
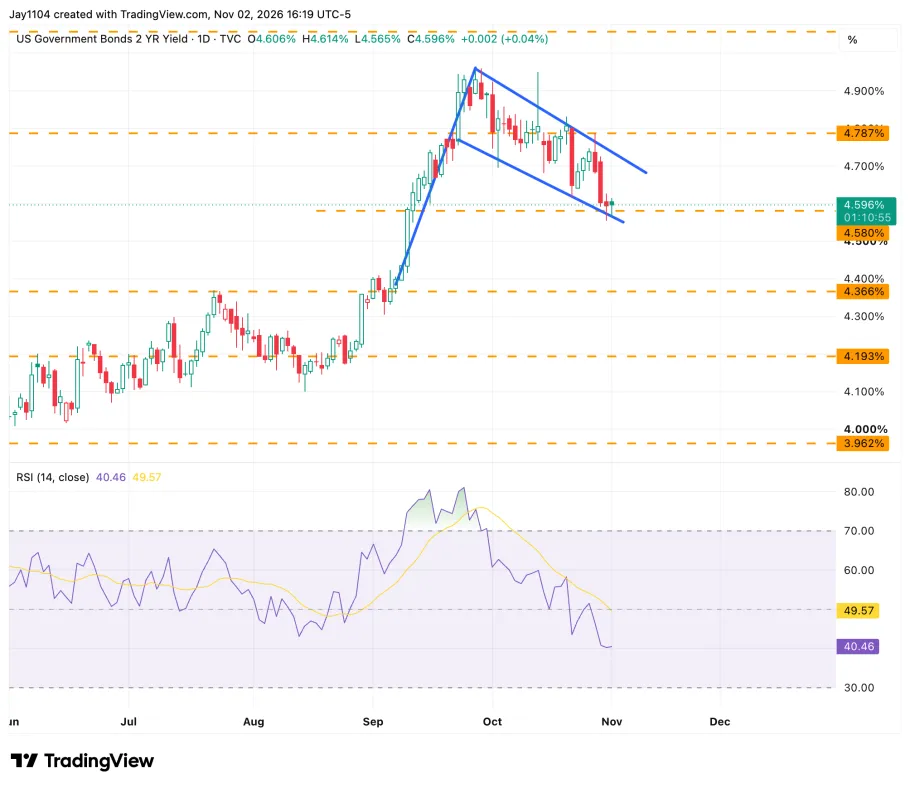
Meanwhile, the 2-year Treasury yield was essentially flat on the day, even as oil prices plunged. The 2-year yield still appears to be forming a bullish flag pattern, suggesting yields could move higher. It just can’t seem to break out.
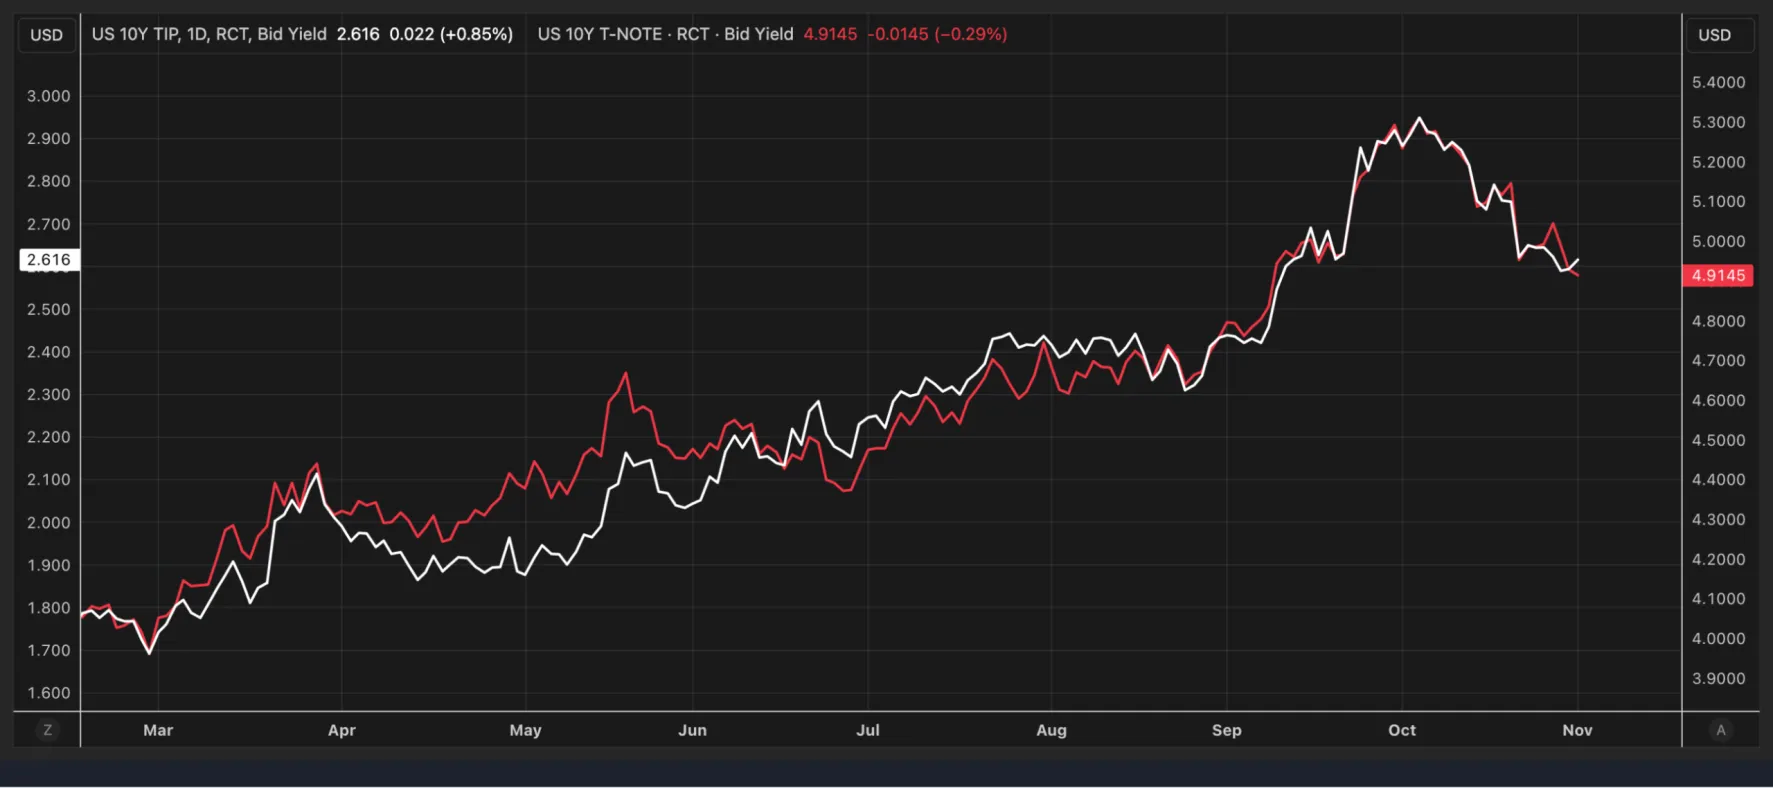
It is worth mentioning that the 10-year Treasury yield fell today, while the 10-year real yield rose. That means inflation expectations declined by more than nominal yields, causing the 10-year breakeven inflation rate to narrow. This could be an important development worth monitoring, particularly if the divergence continues.
Comments
Log in or sign up to join the conversation.