

The S&P 500 fell sharply following a hotter-than-expected CPI report, leaving markets nervous ahead of tomorrow’s PPI report. More interestingly, rates spiked following the release and then drifted lower for the rest of the day. I think much of that reversal likely came from the unwinding of positions following CPI, along with some potential repositioning ahead of PPI. Given some of the read-through from CPI, tomorrow’s PPI report could also come in hot.
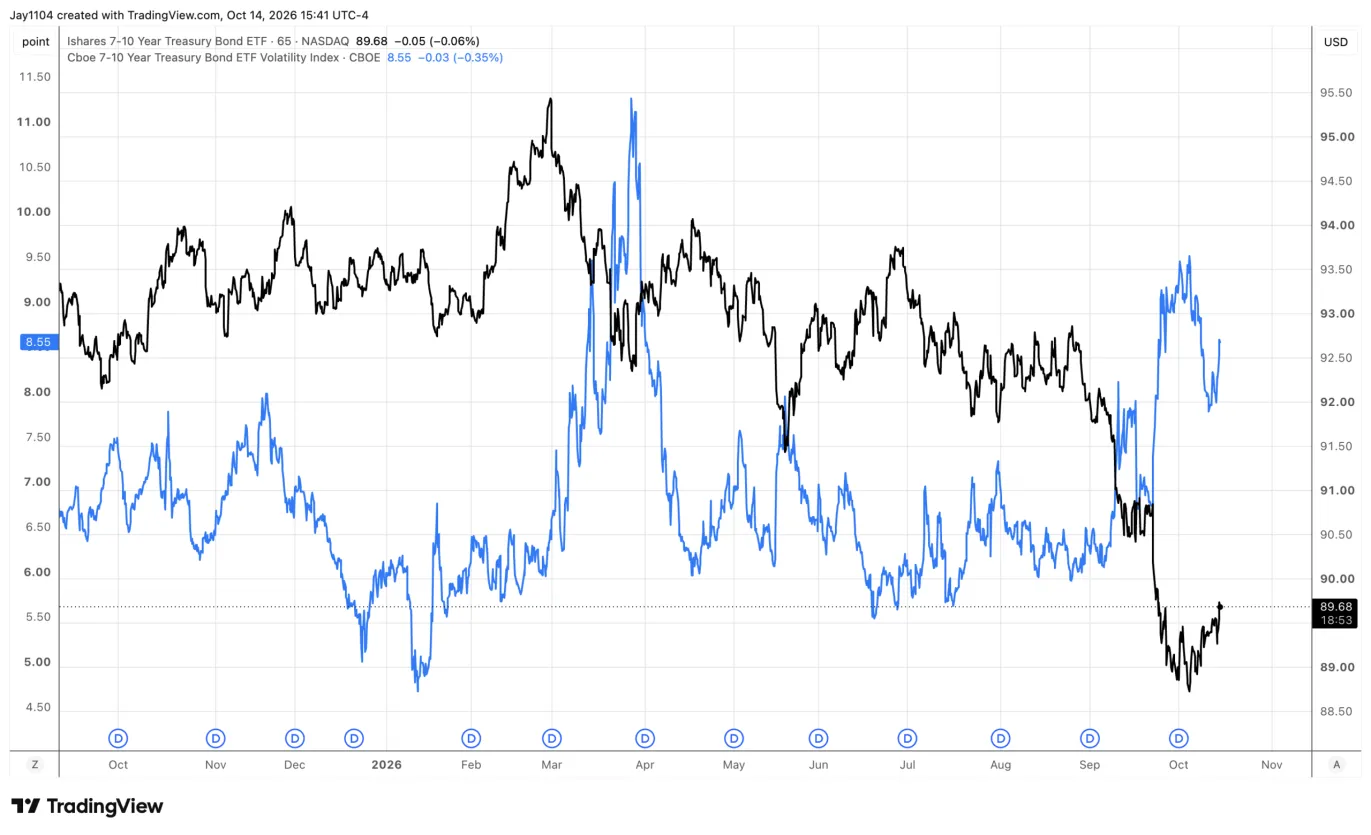
IEF implied volatility jumped to 8.5 today from yesterday’s close of 7.95, yet IEF also finished higher. That breaks the usual inverse relationship and resembles periods when the S&P 500 and the VIX rise together. The higher-rate trade has played out through a declining IEF, so short covering, combined with traders paying up for protection ahead of PPI, could explain much of today’s price action.
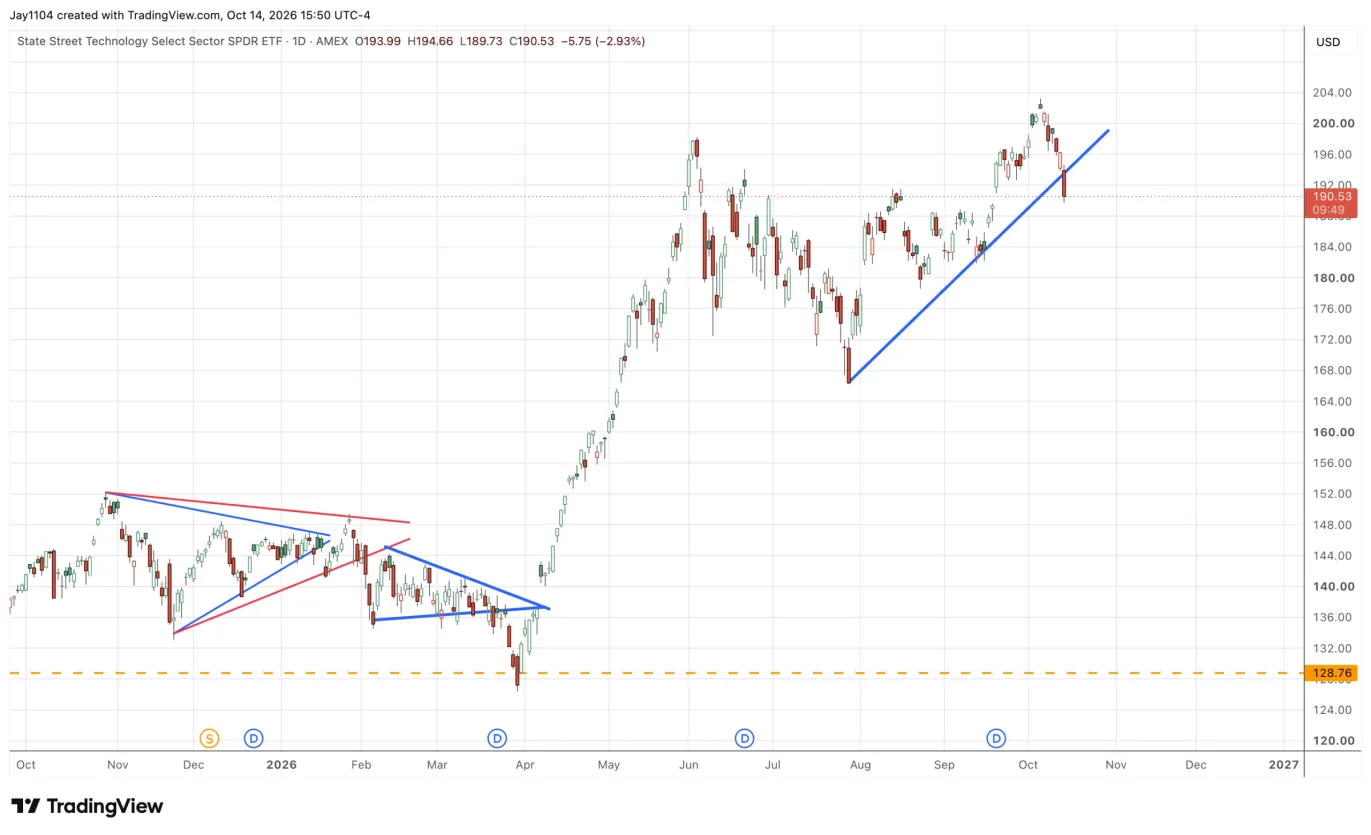
It was not a good day for technology stocks, with the XLK breaking below its uptrend on a closing basis. Typically, when I see patterns break like this, it suggests further downside is ahead, with the next support area for the ETF around $183. More importantly, if the S&P 500 loses the support of the technology sector, we are likely to face a much rougher road ahead. In my view, this group has been the main reason the index has managed to hold together so well, even as equal-weighted stocks and small caps have struggled.
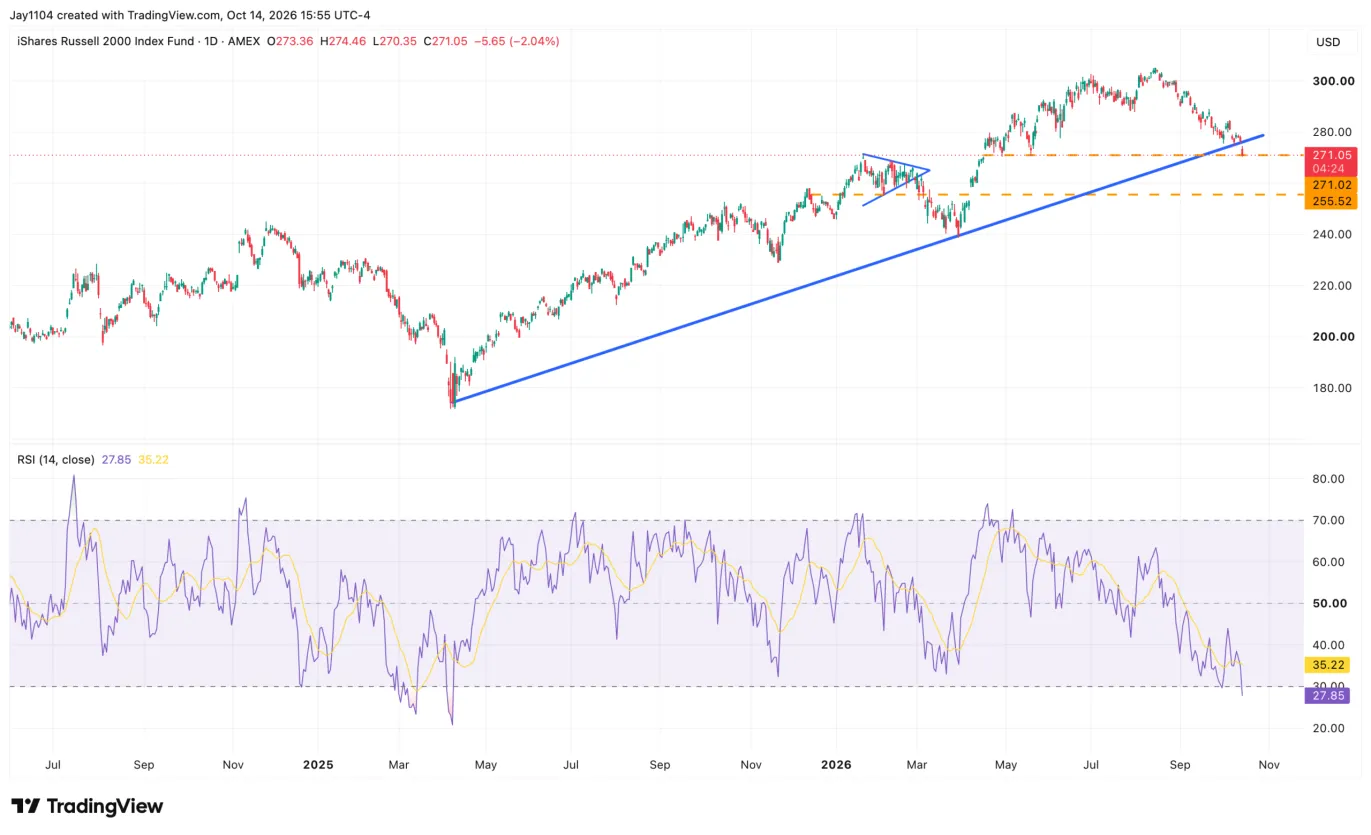
The small-cap ETF (IWM) fell more than 2% on the day, gapping below the uptrend that had held since March 2025. From this vantage point, it looks like a significant breakdown. The ETF really needs to hold support at $270, or it risks falling back into the $250s. This certainly doesn’t look like a chart suggesting the market is about to “broaden out,” unless, of course, by “broaden out,” they mean everything moving lower.
Comments
Log in or sign up to join the conversation.