
The good news is:
The Nasdaq composite (OTC) and S&P 500 (SPX) both closed at all time highs last Tuesday.
The Negatives
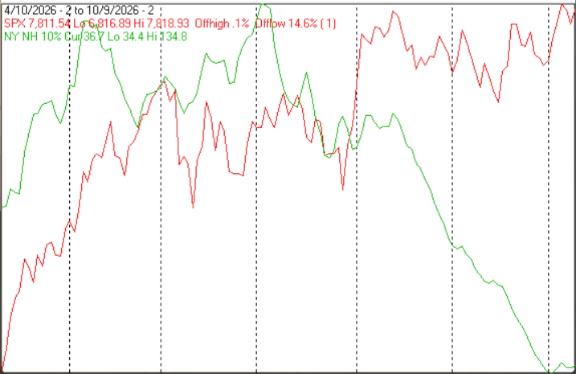
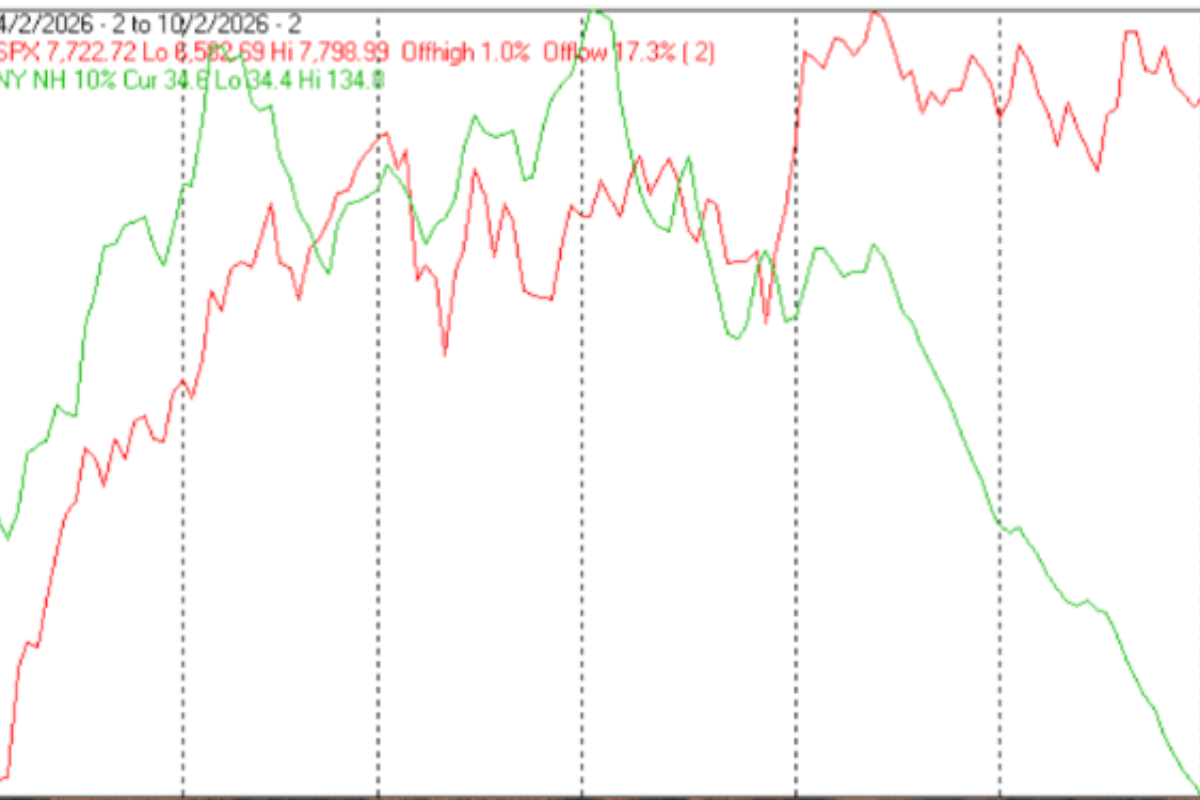
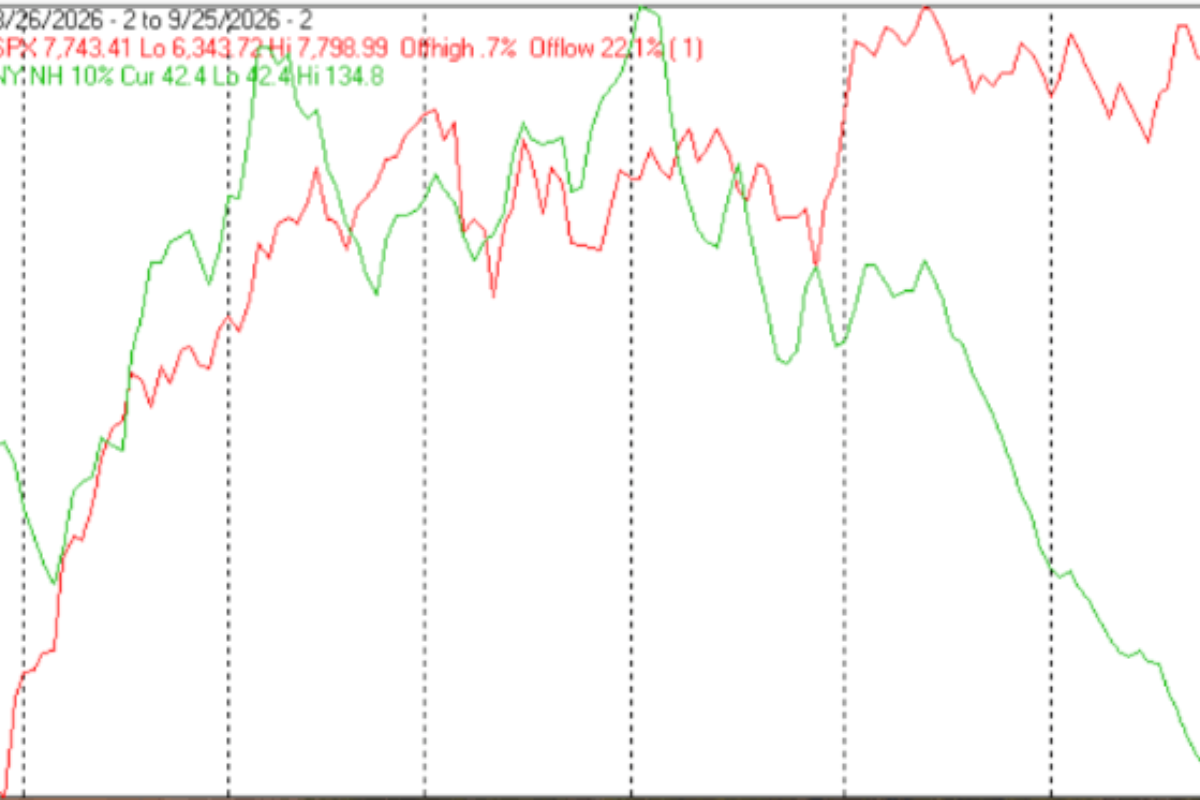
The first chart covers the past 6 months showing the SPX in red and a 10% trend (19 day EMA) of NYSE new highs (NY NH) in green. Dashed vertical lines have been drawn on the 1st trading day of each month. Declining new highs imply narrowing leadership.
NY NH failed to confirm the SPX all time high by a wide margin.
The next chart is similar to the first one except it shows the OTC in blue and OTC NH in green has been calculated with Nasdaq dat
OTC NH ditto.
The next chart covers the past 6 months showing the SPX in red and a 40% trend (4 day EMA) of NYSE new highs divided by new highs + new lows (NY HL Ratio), in blue. Dashed horizontal lines have been drawn, on the Y axis at 10% levels for the indicator; the line is solid at the 50%, neutral level (equal numbers of new highs and new lows).
NY HL Ratio remained in extremely negative territory.
The next chart is similar to the one above except it was calculated with Nasdaq data. The OTC is shown in blue while OTC HL Ratio is shown in red.
OTC HL Ratio ditto.
The next chart covers the past 6 months showing the SPX in red and a 10% trend (19 day EMA) of NYSE new lows (NY NL) in blue. NY NL has been plotted on an inverted Y axis so decreasing numbers of new lows move the indicator upward (up is good).
NY NL moved unimpressively upward last week.
The next chart is similar to the chart above except it shows the OTC in blue and OTC NL, in brown, has been calculated with Nasdaq data.
OTC NL stopped falling, but remained at an extremely low level.
The Positives
The negatives could be worse. Seasonality next week has been positive.
Seasonality
Next week includes the 5 trading days prior to the 3rd Friday of October during the 2nd year of the Presidential Cycle. The tables below show the daily change, on a percentage basis, for that period.
OTC data covers the period from 1963 to 2025 while SPX data runs from 1953 to 2025. There are summaries for both the 2nd year of the Presidential Cycle and all years combined. Prior to 1953 the market traded 6 days a week so that data has been ignored.
Seasonality for the coming week has been positive by all measures and stronger during the 2nd year of the Presidential Cycle than other years.
Report for the week before the 3rd Friday of October.
The number following the year is the position in the Presidential Cycle.
Daily returns from Monday through 3rd Friday.
OTC Presidential Year 2 (PY2)
Year Mon Tue Wed Thur Fri Totals
1966-2 -0.02% 0.77% 1.80% -1.12% -0.21% 1.22%
1970-2 -0.66% -0.85% -0.56% 0.19% 0.39% -1.50%
1974-2 2.17% -0.53% -0.34% 1.39% 1.14% 3.83%
1978-2 -1.21% -2.22% -1.56% -1.32% -2.67% -8.98%
1982-2 1.72% -0.07% 1.49% -0.16% -0.19% 2.79%
Avg 0.40% -0.58% 0.17% -0.20% -0.31% -0.53%
1986-2 0.15% -0.08% 0.53% 0.20% -0.18% 0.62%
1990-2 0.61% -1.24% 0.41% 2.22% 1.00% 2.99%
1994-2 -0.17% -0.13% 0.76% -0.31% -0.37% -0.22%
1998-2 3.59% -2.37% 2.11% 4.52% 0.62% 8.47%
2002-2 0.83% 5.07% -3.90% 3.24% 1.22% 6.46%
Avg 1.00% 0.25% -0.02% 1.97% 0.46% 3.67%
2006-2 0.28% -0.80% -0.33% 0.16% 0.06% -0.63%
2010-2 0.02% 0.65% 0.96% -0.24% 1.37% 2.76%
2014-2 -1.46% 0.32% -0.28% 0.05% 0.97% -0.40%
2018-2 -0.88% 2.89% -0.04% -2.06% -0.48% -0.57%
2022-2 3.43% 0.90% -0.85% -0.61% 2.31% 5.18%
Avg 0.28% 0.79% -0.11% -0.54% 0.85% 1.27%
OTC summary for PY2 1966 - 2022
Avg 0.56% 0.15% 0.01% 0.41% 0.33% 1.47%
Win% 60% 40% 47% 53% 60% 60%
OTC summary for all years 1963 - 2025
Avg 0.43% 0.03% -0.23% 0.36% -0.07% 0.51%
Win% 61% 51% 48% 60% 57% 57%
SPX PY2
Year Mon Tue Wed Thur Fri Totals
1954-2 -0.80% -0.40% -0.03% -1.21% -0.53% -2.97%
1958-2 0.45% -0.70% -1.33% 0.71% 1.02% 0.16%
1962-2 0.56% -0.33% -0.33% -0.97% -1.33% -2.40%
1966-2 1.14% 1.56% -0.80% -0.27% 0.45% 2.08%
1970-2 -1.07% -0.13% 0.15% 0.55% -0.44% -0.94%
1974-2 2.25% -1.79% -1.55% 1.19% 1.56% 1.66%
1978-2 -1.96% -1.32% -0.76% -1.15% -1.39% -6.58%
1982-2 2.61% -0.02% 1.69% -1.57% -0.74% 1.97%
Avg 0.59% -0.34% -0.25% -0.25% -0.11% -0.36%
1986-2 0.18% -0.23% 1.46% 0.31% -0.29% 1.43%
1990-2 1.07% -1.42% -0.05% 2.34% 2.20% 4.13%
1994-2 -0.03% -0.28% 0.56% -0.73% -0.42% -0.90%
1998-2 1.36% -0.29% 1.08% 4.18% 0.85% 7.17%
2002-2 0.73% 4.73% -2.41% 2.23% 0.59% 5.88%
Avg 0.66% 0.50% 0.13% 1.66% 0.59% 3.54%
2006-2 0.25% -0.37% 0.14% 0.07% 0.12% 0.22%
2010-2 0.01% 0.38% 0.71% -0.36% 0.20% 0.95%
2014-2 -1.65% 0.16% -0.81% 0.01% 1.29% -1.00%
2018-2 -0.59% 2.15% -0.03% -1.44% -0.04% 0.06%
2022-2 2.65% 1.14% -0.67% -0.80% 2.37% 4.70%
Avg 0.14% 0.69% -0.13% -0.50% 0.79% 0.99%
SPX summary for PY2 1954 - 2022
Avg 0.40% 0.16% -0.17% 0.17% 0.30% 0.87%
Win% 67% 33% 39% 50% 56% 67%
SPX summary for all years 1953 - 2025
Avg 0.42% 0.03% -0.25% 0.21% -0.09% 0.32%
Win% 64% 40% 47% 56% 51% 64%
Interest Rates
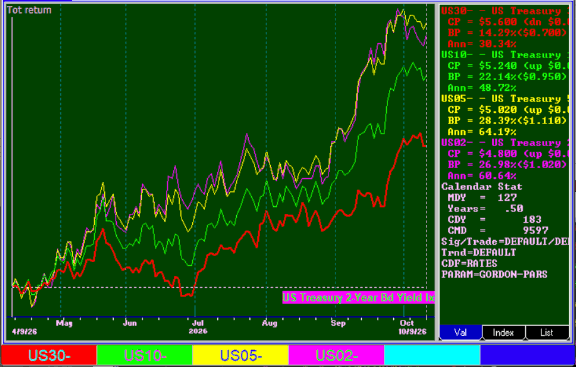
Treasury rates at their close last Friday and their changes from last July:
2yr yield 4.797% up from 4.183%
5yr yield 5.026% up from 4.289%
10yr yield 5.237% up from 4.550%
30yr yield 5.602% up from 5.072%
The next chart, made with FastTrack, covers the past 6 months showing a relative comparison of US treasury interest rates. 30 year in red, 10 year in green, 5 year in yellow and 2 year in purple.
Conclusion
Prices were mostly up last week and the breadth indicators quit deteriorating. It looks like the beginning of a rally.
The strongest sectors last week were Energy and Utilities (for the 2nd week in a row) while the weakest were Electronics (down from the top for the past 3 weeks) and Banks.
I expect the major averages to be higher on Friday October 16 than they were on Friday October 9.
Last week the Russell 2000 was down while the other major indices were up, so I am calling last week’s positive forecast a tie.
Comments
Log in or sign up to join the conversation.