
"When China enters the room, profits walk out the door." — Louis-Vincent Gave
When a company, CEO, or investment theme makes the cover of a major magazine, it can be a sign that enthusiasm. What follows is often a reversal.
It's called the magazine-cover indicator. My good friend Jared Dillian has talked about it for years. It's hardly foolproof. But it’s worth paying attention to when it happens.
Here’s the September 5th cover of The Economist.
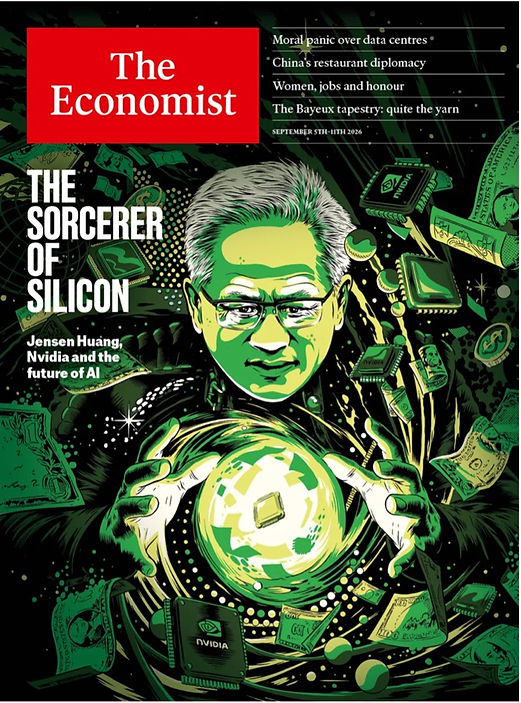
Source: The Economist
Unless you’ve been in a news blackout, you know that this week, Jensen Huang resigned as Nvidia (NVDA)’s CEO. It came days after he admitted to an extramarital affair with a woman US intelligence officials reportedly suspected of working for Beijing, and a day after reports of a second affair. That's quite a development two months after Huang's September appearance on the cover of a major magazine.
This happened at a time when Nvidia is facing growing domestic competition, and China is building a sophisticated and competitive semiconductor industry of its own. It’s part of a larger story unfolding.
Tale of Two Hemispheres
Today we are increasingly living in a tale of two hemispheres. One dominated by the US, the other by China. Both face challenges, of different sorts. A challenge for each is we are no longer lifting each other up. We’ve moved from being business partners to rivals. One way our economies are diverging is in how we're developing our industrial capabilities.
US manufacturing is expanding. The Institute for Supply Management (ISM) earlier this month reported that October marked the 10th straight month of manufacturing growth in the US. Much, but not all, of this growth can be attributed to data centers and AI.
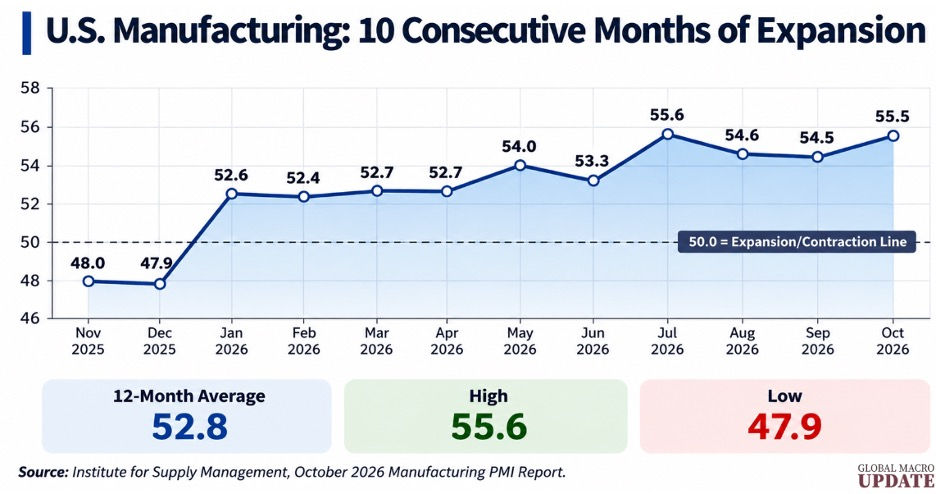
Source: ISM
I’m thrilled about this. I began my career in an industrial business, and I’ve always enjoyed the physical nature of manufacturing. Seeing products roll off an optimized line is just a thrill. It also is a sign of resilience. There’s nothing wrong with outsourcing production, but US financial engineers have taken things too far. And that has come at a cost.
Growth in US manufacturing means growth in US resilience. We shouldn’t rely on other nations to produce all of our essential goods like medicines or key inputs for our defense.
It took over four decades for the US to fall so far in terms of manufacturing capabilities and capacity. It will take years to rebuild. The key is getting started and committing to annual progress. That seems to be happening, but we’ve got a long way to go to catch up.
Our challenge today is we’ve gotten used to cheap goods produced by lower wage foreign labor. Bringing production home increases cost at a time when interest rates and inflation are higher than they’ve been. This is where things get hard for politicians. They, like so many CEOs of publicly traded companies, are focused on the short term, meaning their election cycles. It’s hard to do the right thing if you aren’t in office, and it’s hard to get re-elected while telling voters they have to take some medicine.
But here’s the thing: we can do both. We can become more resilient, while remaining open to global trade. Competition, after all, is a good thing. It brings down prices for consumers, and it forces innovation.
Think about it this way: would you like to pay less for your next iPhone? Your next TV? Would you like your next car to both cost less and be better (more efficient, more reliable, more useful technology, safer)? For this to happen, there needs to be more competition. Instead, we nurture and encourage fiefdoms, if not outright monopolies.
China has a different problem: overcapacity. In any industry they make a priority, they destroy margins, as Louis Gave of Gavekal often points out. They’ve done this in so many industries, like solar panels, EVs, shipbuilding, steel, mineral processing, and electronics.
Soon you’ll be able to add semiconductors to the list.
China has quickly learned the value of resilience. The US taught them this lesson, not fully anticipating what the response from Beijing would be. Instead of being crippled by denied access to high-end chips, China has set out to not only build their own, but to build the machines that make the chips.
For decades, this has been the exclusive realm of ASML. Based in the Netherlands, ASML produces the machines that make semiconductors. Without getting too into the weeds here, they have 100% market share in the extreme ultraviolet (EUV) lithography space, and well over 80% of total global semiconductor lithography market.
Their net profit margin is around 35%. Without their machines, you cannot produce the most sophisticated chips required for AI. The US denied China access to these machines.
Rather than cave, China is building their own ASML, called Aishengna, or more formally, Shanghai Aishengna Electronic Technology Group.
Also, China isn't relying on advances in semiconductor manufacturing alone, either. It's finding ways to compete using the technology and resources it already has.
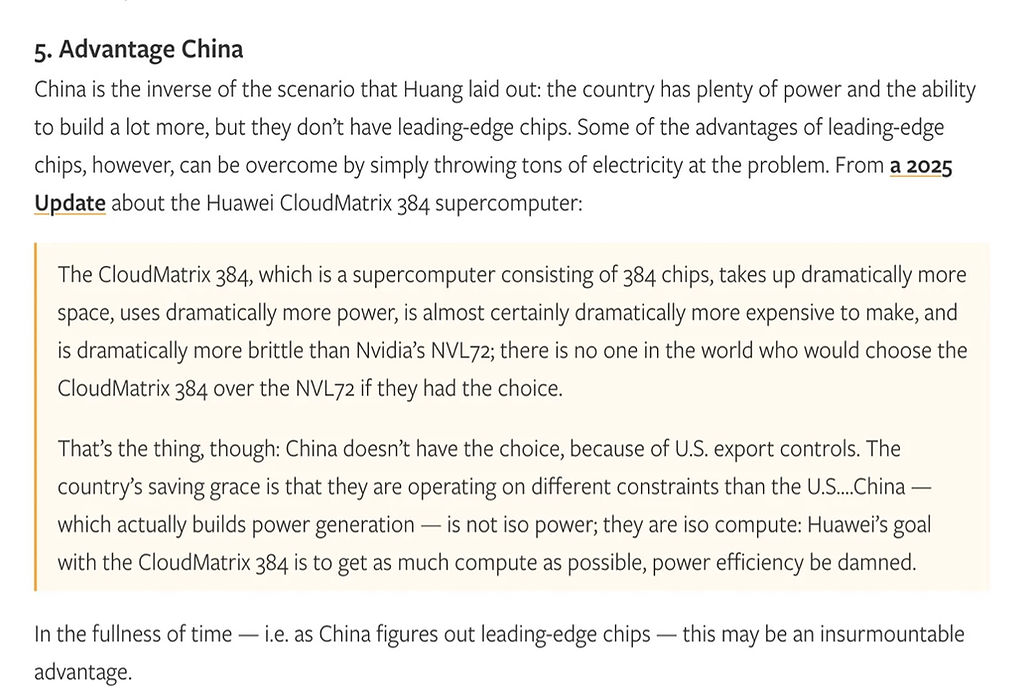
Ben Thompson of Stratechery explains how China is compensating for its less advanced chips by using more of them and a lot more electricity.
Source: Ben Thompson's Stratechery
If China eventually closes the gap in advanced semiconductors while retaining its advantage in power generation, it could become an even more formidable global competitor. Who do you think India will buy its chips from?
One of the lessons we should take away from this bifurcation of global trade: we need to build our own markets, domestically and globally.
The divergence in industrial priorities between the US and China raises an uncomfortable question: Have we become so focused on digital and financial engineering that we've neglected the physical aspects of our economy?
In the US, we produce two kinds of engineers. Digital Engineers and Financial Engineers. China has focused on the physical as much as the digital. Their area of maniacal focus is on cost + quality. While the US continues to lead the frontier, as they say in AI, our digital and financial engineering may be getting us in trouble. With the AI trade absorbing hundreds of billions of dollars, have we misallocated capital? I have a feeling there will be a reckoning. Jensen’s dalliance may have set it in motion.
Brave New Competition
China isn't the only source of pressure on Nvidia. Some of its biggest customers are becoming competitors, too.
Google (GOOGL), for example, has spent years developing its Tensor Processing Units (TPUs), chips designed specifically for AI workloads. To be fair to Nvidia, it still enjoys enormous advantages, particularly its software ecosystem. But Google operates its own data centers, develops AI models, and has a strong incentive to reduce computing costs.
And Google is finding customers. Anthropic, the company behind Claude, has made substantial commitments to Google's TPU technology. Broadcom (AVGO), which helps develop the chips, has outlined plans for multiple gigawatts of AI computing capacity for Anthropic. Google doesn't have to replace Nvidia to change the economics of its business. It only needs to offer a credible alternative.
Competition puts pressure on prices and profit margins. That's good for customers, even if it's less appealing to shareholders accustomed to extraordinary returns.
But beyond Nvidia, a much larger competition is taking shape between the US and China. America leads in advanced chip design, software, and innovation. China has built enormous manufacturing capacity and integrated supply chains, producing sophisticated goods at prices competitors struggle to match.
That doesn't mean global trade disappears. But as two increasingly distinct economic spheres emerge, the second- and third-order consequences could be enormous.
Which technologies will other countries adopt? Whose supply chains will they depend on? How will traditional alliances change?
And this goes well beyond technology and manufacturing. Both the US and China face their own economic, political, and social challenges. How each navigates those challenges will help shape its influence over the rest of the world.
For investors, the question isn't simply which country comes out ahead. It's how we navigate the changes along the way, and where the opportunities—and the profits—will emerge as these two hemispheres take shape.
It's going to be interesting, to say the least.
Comments
Log in or sign up to join the conversation.