

The Fed minutes, in my view, had a more hawkish tilt, laying out what appears to be a committee looking to hike again before the end of this year. Several participants said policy is not restrictive, or only mildly restrictive, with inflation running above target. The minutes also revealed that the NY Fed deems reserves ample and has PAUSED reserve management purchases, meaning it is no longer adding to its balance sheet by buying T-bills. The minutes also pushed back on leaning on 3-month annualized core PCE readings, noting:
“A few participants observed that the 3-month change measure of core PCE inflation showed a material decline since the start of the year but cautioned that this measure is more volatile than the 12-month change measure and has shown a strong tendency to understate inflation in the second half of the year compared with the first half.”
I guess everyone can stop looking at the 3-month annualized inflation reading going forward. It seems like a waste of time to keep watching it.
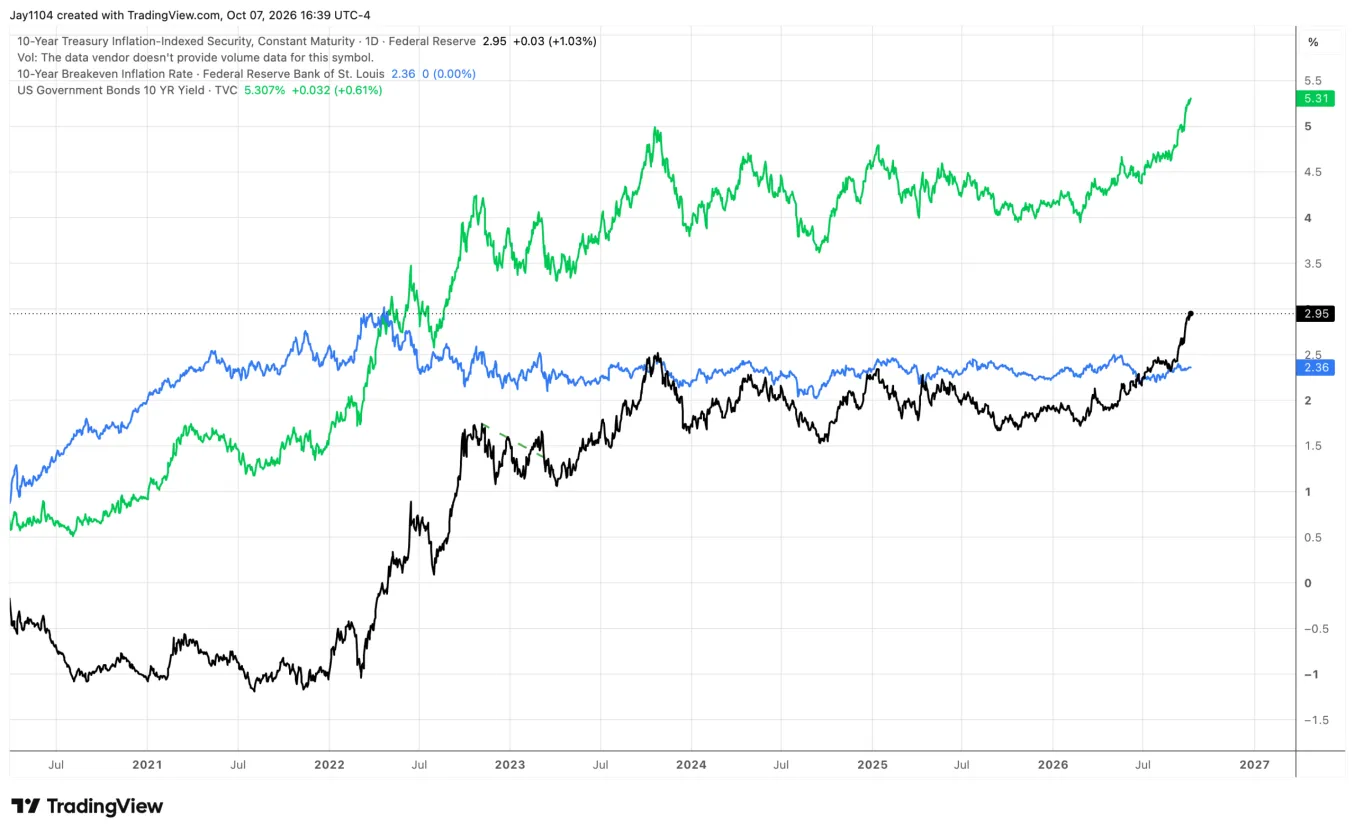
Meanwhile, the 10-year Treasury auction was really strong, and the 10-year Treasury rate finished the day flattish at 5.29%. The minutes also noted that the rise in longer-maturity rates was mostly driven by rising real yields, not inflation expectations. That is exactly what I have been writing about and saying for some time now. I think a chart of the three components makes it fairly obvious.
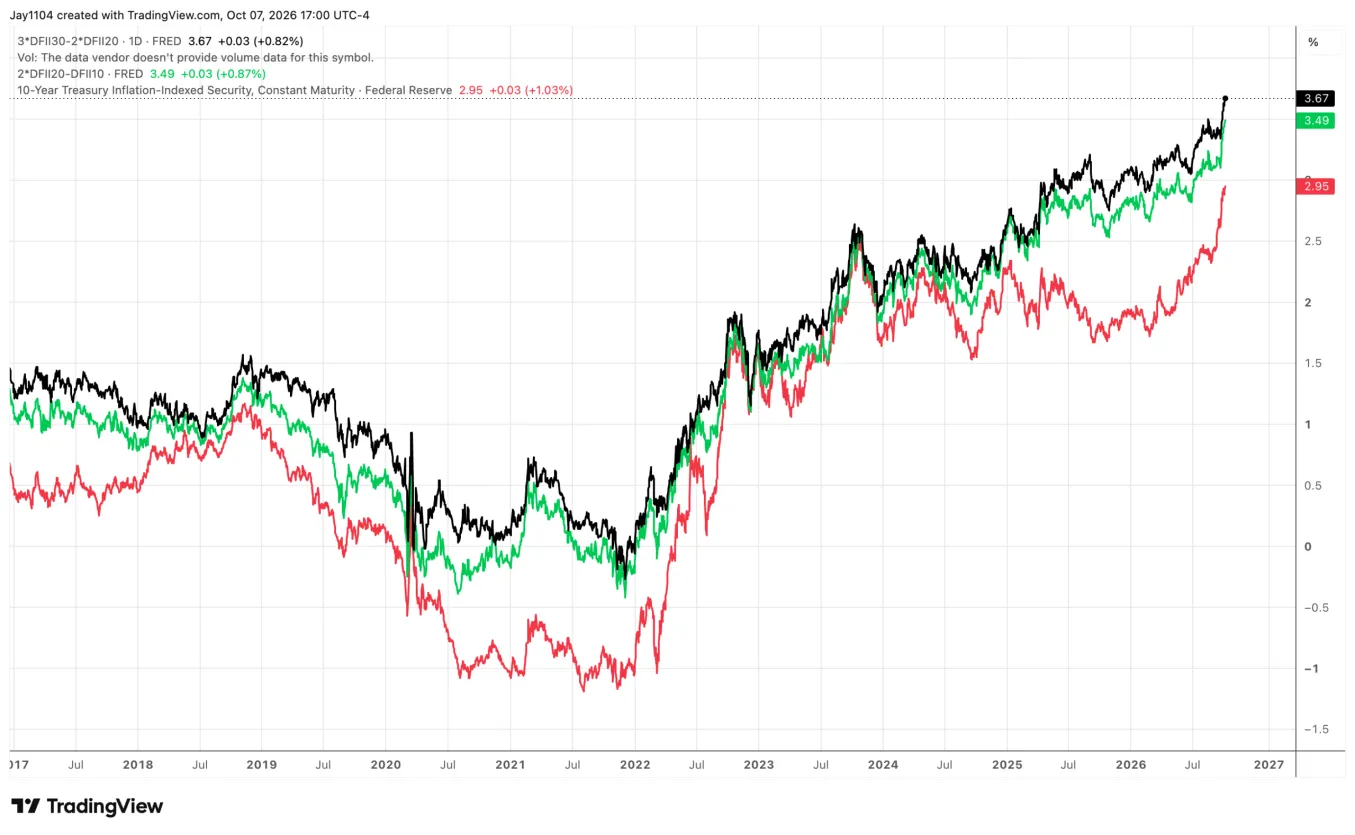
Speaking of real yields, the 10-year real yield is just shy of 3%, and both the 10y10y forward real yield and the 10-year real rate starting 20 years from now are higher, at 3.5% and 3.7%, respectively. The two forward rates have been climbing steadily since the end of 2022 in a fairly consistent trend. So even as the 10-year real yield diverged, the forward rates have been telling us for some time that real rates would be higher in the future. Based on these forwards, the market is pricing a 10-year real yield of about 3.5% to 3.7%, which, with a breakeven inflation rate of about 2.3% priced in, puts the 10-year around 5.8% to 6%. That is pretty close to the 10y10y nominal forward rate of 6.1%.
Comments
Log in or sign up to join the conversation.