
Every three months, I’m not alone in asserting that Nvidia (NVDA) earnings are the most important of the quarter for investors. Enthusiasm for the artificial intelligence buildout has been the key market driver for the past four years, and no company has been more integral to that effort than NVDA. While it maintains that central role, recent events have raised more existential questions about NVDA’s past activities and future prosperity. Since those can occupy far more column space than I can offer, let’s stick to examining options market pricing ahead of this afternoon’s event.
Expectations for NVDA’s fiscal third quarter, which ended on October 26, are once again spectacular. Revenues and EPS are expected to be about $109.3 billion and $2.47, respectively. That would show roughly 90% growth over the past year, an enviable, even ridiculous, growth rate. There will undoubtedly be concerns about guidance, specifically the degree to which future sales will be affected by the cessation of sales to Megaspeed and other customers in the countries affected by the new Commerce Department regulations.
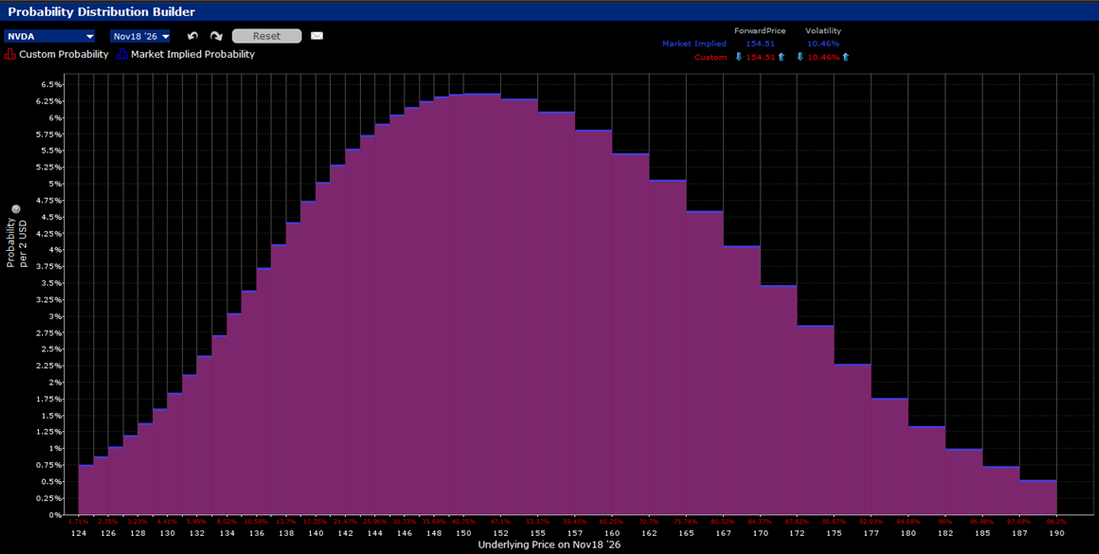
The IBKR Probability Lab shows fairly symmetrical distributions both for options expiring tomorrow and those expiring Friday afternoon. The peaks in the $152.5 range are slightly below the snapshot prices, but those were taken shortly after NVDA rallied on news that Jensen Huang would be “honored” to return to the company as CEO. (I’d be honored to be considered as a Presidential nominee, but I don’t see much likelihood of either occurring.) Basically, the market is telling us that it doesn’t have a clear view about the likely post-earnings move for the stock.
IBKR Probability Lab for NVDA Options Expiring November 18, 2026
IBKR Probability Lab for NVDA Options Expiring November 20, 2026
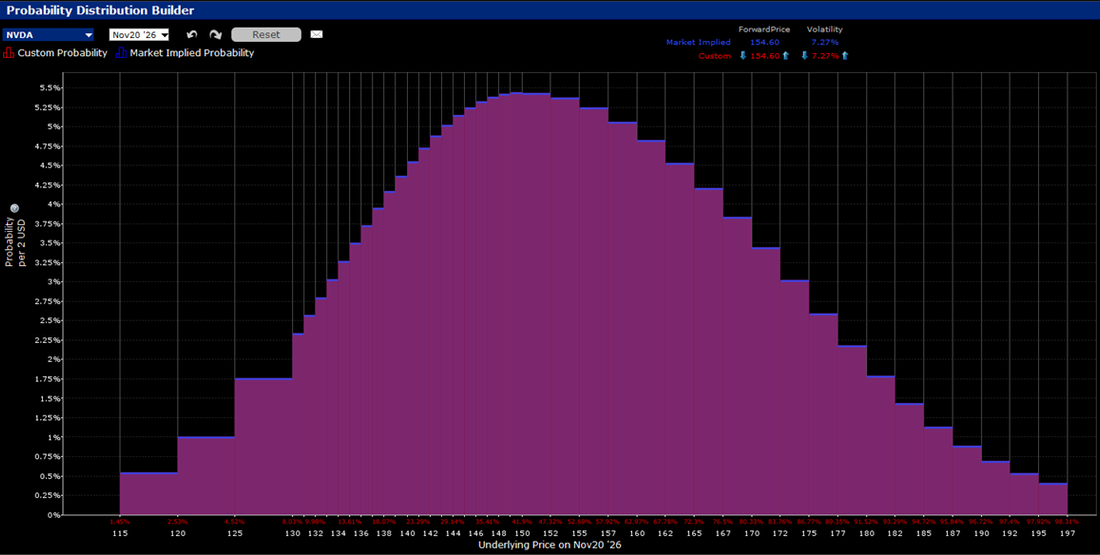
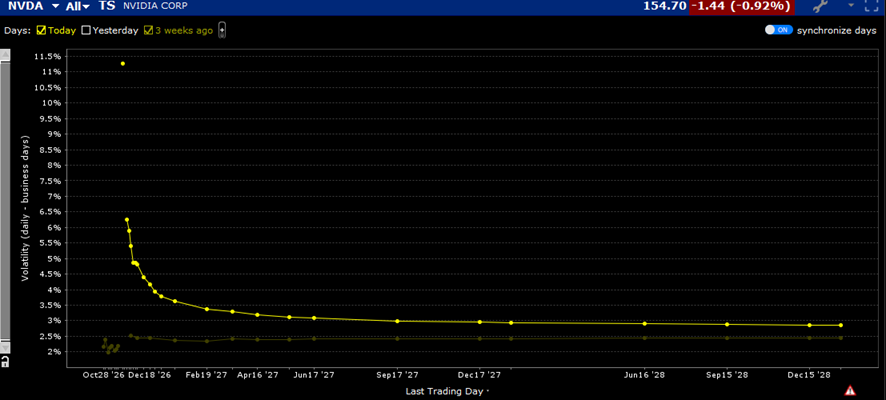
The implied daily volatility of at-money options expiring tomorrow is a robust 10.46%, which is about two percentage points below yesterday’s level. That is well above the six-quarter average of 3.86% (+8.74%, -1.77%, -5.46%, -3.15%, -0.79%, +3.25%). Understandably, traders are displaying quite a bit more uncertainty than usual. We can see how much excess volatility has been priced into the entire volatility term structure for NVDA over the past three weeks:
NVDA Term Structure of Volatility, Today (bright yellow), 3 Weeks Ago (pale yellow)
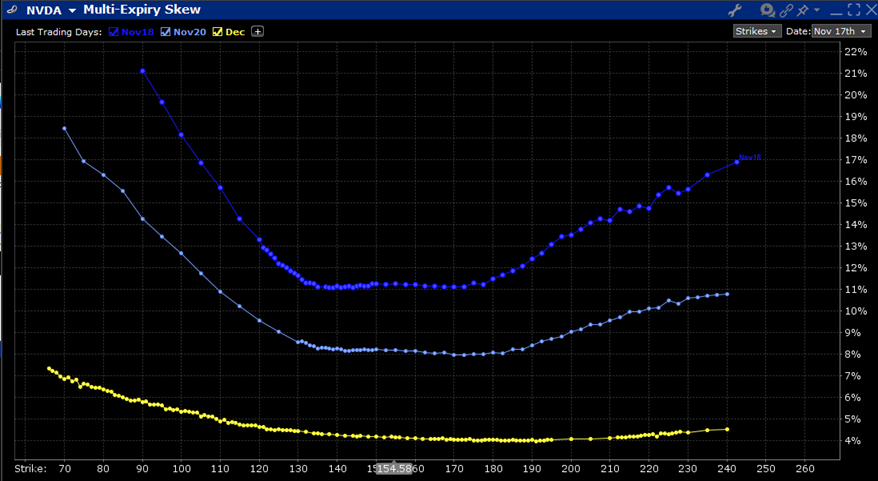
Befitting the general uncertainty surrounding this event, skews are flattish throughout a wide range of potential outcomes before they steepen quickly for extreme moves.
Skews for NVDA Options Expiring November 18 (dark blue), November 20 (light blue), December 17 (yellow)
Source: Interactive Brokers
Bottom line, it is incredibly difficult to know exactly what to expect from this afternoon’s report and conference call. The quick $6 rally that occurred after Huang’s hopeful comments today shows that the stock might be more susceptible to a rally on good, or even benign, news. The myriad questions surrounding NVDA are unlikely to be resolved this afternoon, but some clarity in either direction would be welcome.
Comments
Log in or sign up to join the conversation.