
Asia sets the tone: Xi landed in Washington for today's summit with Trump, with the US-China trade truce extended to January 10. Nikkei jumped on its first trading day back from holiday, the yen firmed, and a surprise jump in Australian jobs came with a rising jobless rate. Meanwhile the dollar stays broadly supported on the "higher-for-longer" Fed view.
EUR/USD
1.1408 (–0.36%), holding near multi-month lows as dollar strength persists. Bias stays bearish while below 1.1450.
Gold (XAU/USD)
$4,289, essentially flat after Tuesday's selloff – stabilizing as the market digests the stronger dollar and rate outlook.
Oil
Brent at $102.42 (–0.64%), drifting lower with no fresh headline drivers after this week's sharp swings.
Bitcoin
~$84,200 (–2.4%), extending its pullback from last week's $87K+ high after $280M+ in long liquidations; $80K–82K is the support zone to watch.
Asia overnight
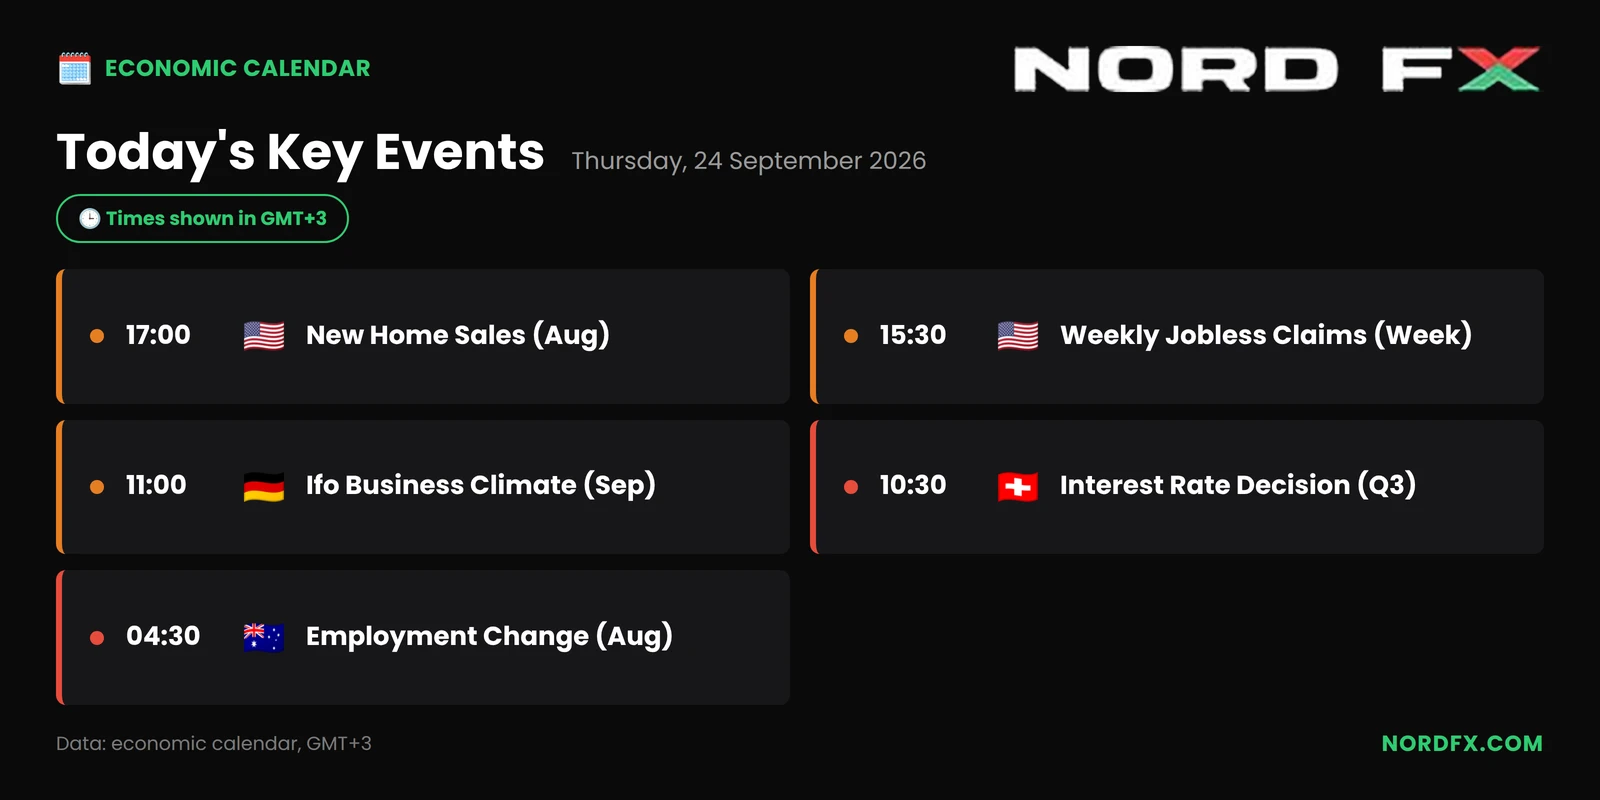
Nikkei +1.3% on its return from a three-day holiday, boosted by chip/component names after Meta's new device announcement; Topix +0.1%. USD/JPY slipped to ~157.80 from above 158.20 as the yen firmed. Australia added 39,500 jobs in August (roughly double forecasts), yet unemployment rose to 4.6% – the highest since late 2021 – as participation climbed. Mainland China markets close Friday for the Mid-Autumn Festival.
Bottom line: dollar strength and the Xi–Trump summit are today's key threads – watch for any statement out of Washington and US data for fresh direction.
Comments
Log in or sign up to join the conversation.