
Asia: chip rout, mixed picture
Kospi –6.2% (≈5,990) | Nikkei –2.0% (≈67,600) | Taiwan –1.8% | Hang Seng –0.2% (≈24,230) | Shanghai +0.2% (≈3,806) | ASX 200 flat (≈8,783). Fears over AI spending and new Chinese memory-chip competition hit SK hynix, Samsung, Kioxia and Tokyo Electron.
Wall Street: tech drags
Dow +0.38% (51,851) | S&P 500 –0.06% (7,807) | Nasdaq –0.44% (27,246). Semiconductors led the decline. Treasuries were closed for the Columbus Day holiday, so the 10-year yield stays near 5.24%.
Oil and geopolitics
Brent is near $105.7 (–0.9%) and WTI near $92.7. Hormuz shipping risks and Houthi attacks keep the risk premium high, while reports of extra Russian diesel exports cap gains.
Dollar and gold
DXY ≈102.4 (–0.15%), easing from an 18-month high | Gold ≈$4,195 (+0.6%) rebounds as the dollar softens.
Currencies and crypto
EUR/USD ≈1.1172 (+0.15%) | USD/JPY ≈158.3 | GBP/USD ≈1.3217 | Bitcoin ≈$83,500 (–0.8%) | Ethereum ≈$2,516 (–2%).
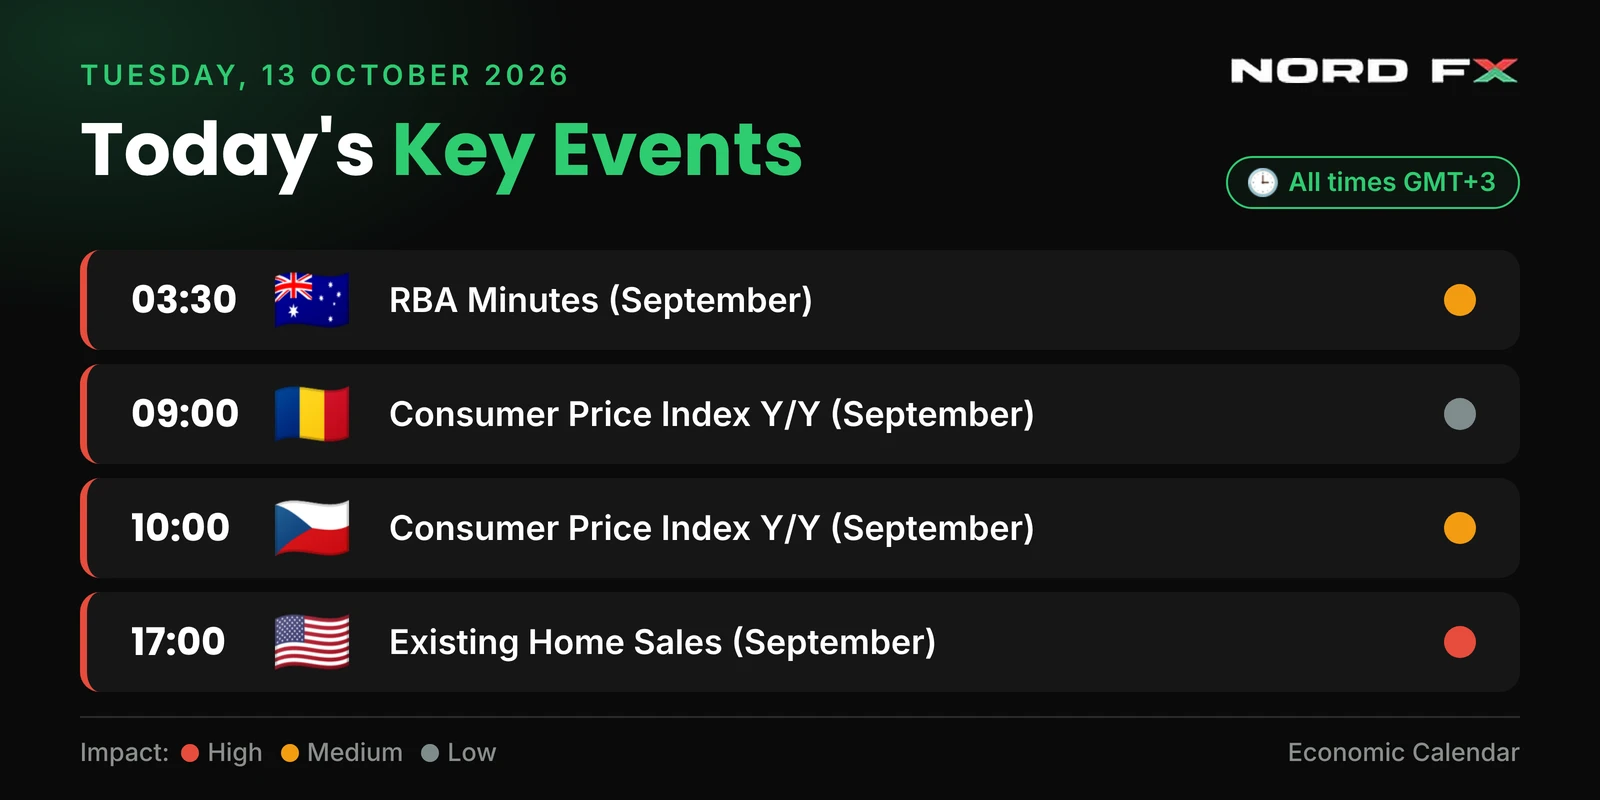
Today’s calendar
Germany final CPI | OPEC monthly report | ADP weekly employment and existing home sales | Bank earnings start: JPMorgan, Goldman Sachs, Citigroup, Wells Fargo.
Next up
Tomorrow brings US CPI (consensus 3.7% y/y vs. 3.4%), the last inflation print before the Fed’s October 27–28 meeting. Lagarde also speaks.
Comments
Log in or sign up to join the conversation.