
The Fed minutes turned hawkish: almost all officials see more rate hikes ahead, a few eye a move bigger than 25 bp, and Waller floated 50 bp. A 25 bp hike on December 9 is ~95% priced in. The 10-year US yield holds above 5%, and the dollar stays near a 19-month high.
Gulf tensions continue: a tanker was hit near Hormuz and Washington is reportedly weighing new strikes on Iran. Even so, oil is flat and gold is falling, as rate fears outweigh the safe-haven bid.
Wall Street: the S&P 500 fell 0.23% to 7,323.6 (5th straight loss), the Dow lost 1.11% to 50,198, and the Nasdaq gained 0.42% to 24,430. The VIX is at 24.6. Nvidia faded after earnings, and Moody’s cut its outlook after Jensen Huang’s exit.
Asia is mostly weaker:
Nikkei 225: +0.46%, 59,298
Hang Seng: –2.11%, 22,803
Shanghai: –0.52%, 3,569
Kospi: flat, 5,068
Taiwan: –4.60%, 38,348
ASX 200: –1.04%, 8,730
Nifty 50: +0.33%, 25,312
FX: EUR/USD 1.0966, near a 19-month low. GBP/USD 1.3137. USD/JPY 159.53, close to the 160 level. AUD/USD 0.6689.
Gold $3,739, near a 14-month low and down ~3.7% on the week. Silver $45.3. Brent $92.0, WTI $82.2.
Bitcoin $63,384 (–2%), with $62,000 as key support. Ethereum $1,801.
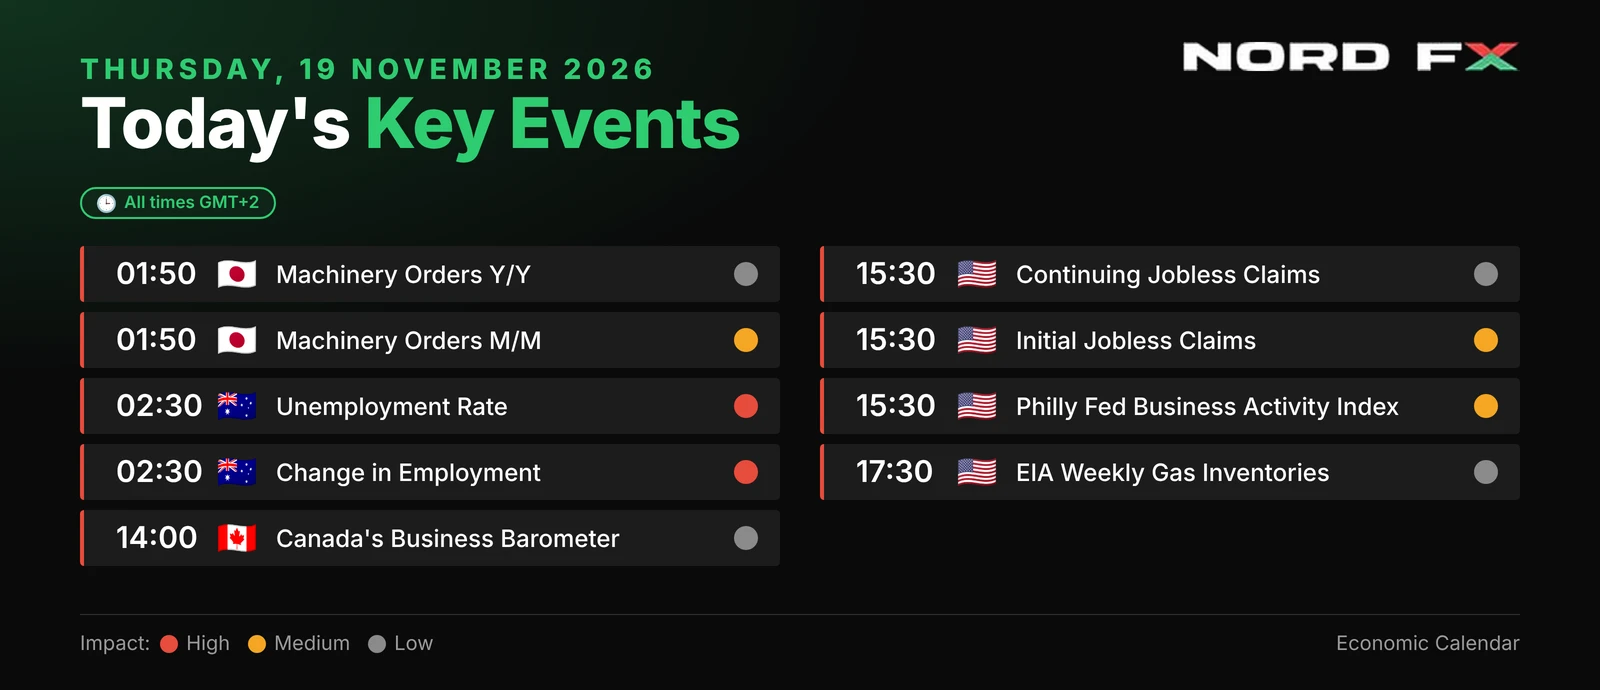
Today: US jobless claims and the Philly Fed index at 13:30 GMT 🇺🇸, Walmart earnings, and Anthropic’s Nasdaq debut (ANT, priced at $83).
Comments
Log in or sign up to join the conversation.