
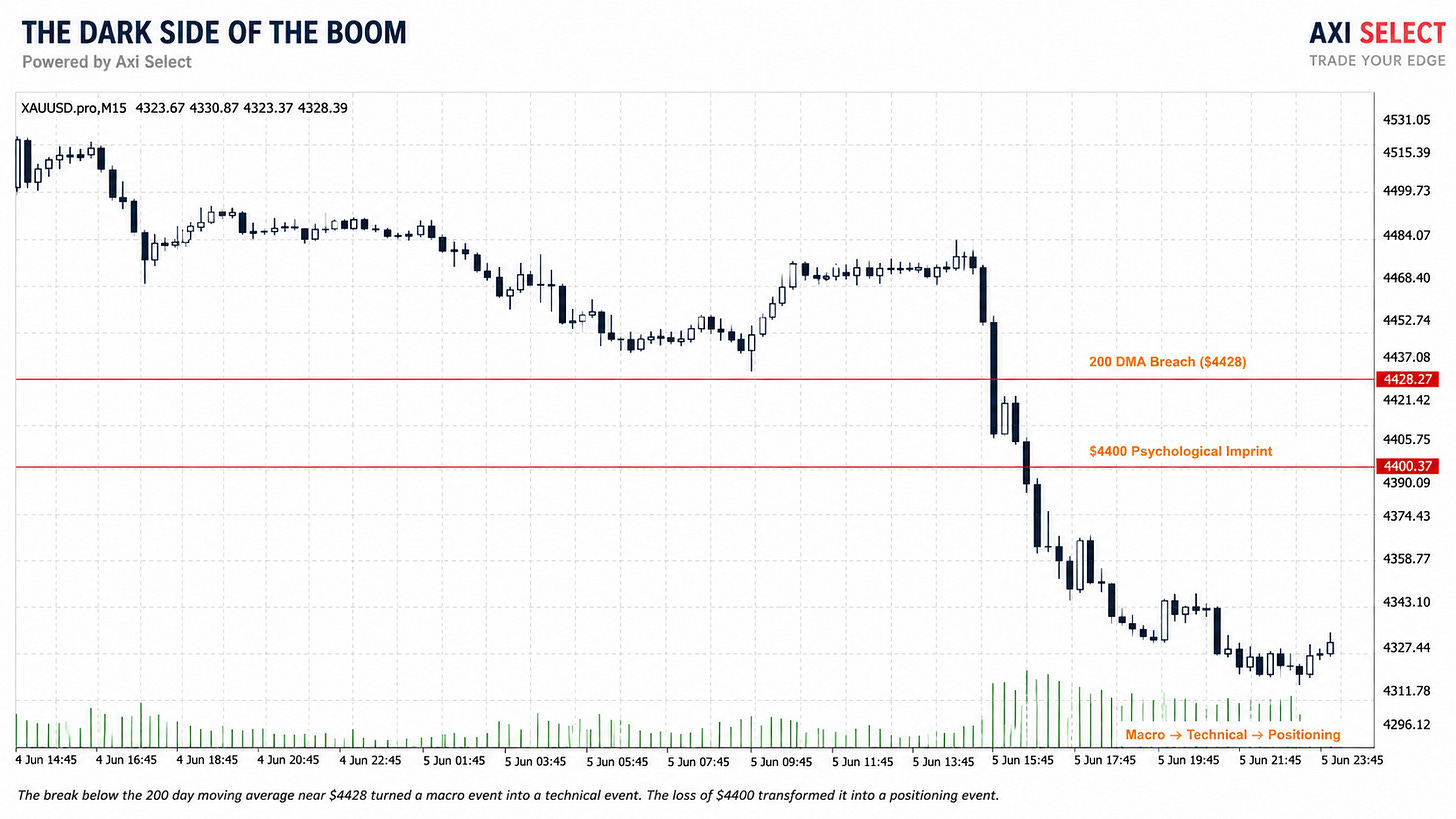
The broader narrative remains intact with plenty of discussion around peak growth and inflation, as well as policy support, with worries exacerbated by the continuing spike in the Delta variant of covid. Hotter-than-expected consumer and producer price reports this week and continued reports of supply chain challenges have seemingly not dented the market's faith in inflation as a transitory phenomenon. Yields are slightly higher, although the curve is meaningfully flatter on the week, with real rates still near YTD lows, supporting gold. Commodities are mixed with base metals continuing to trade well, while oil remains under pressure on the prospect of OPEC+ supply increases as well worries over demand given the aforementioned However,I think the producer compromise limits oil downside & lessen OPEC tail risks to the outlook from either strategy pivot or coalition breakup, I am still bullish up to Brent USD 80/bbl
London Open

The broader narrative remains intact with plenty of discussion around peak growth and inflation
Disclaimer: This and other personal blog posts are not reviewed, monitored or endorsed by TalkMarkets. The content is solely the view of the author and TalkMarkets is not responsible for the content of this post in any way. Our curated content which is handpicked by our editorial team may be viewed here.
Comments
Log in or sign up to join the conversation.