
Paramount Skydance Corp (PSKY) call options saw a huge volume on Friday, expiring at the end of 2026. This is ahead of the expected Oct. 6 merger close with Warner Bros. Discovery (WBD). This may indicate investors are bullish on PSKY given its low valuation. This article will discuss this trade.
PSKY closed at $9.50 on Friday, Oct. 2, when these huge call options at a $9.00 strike price expiring Dec. 18, 2026, traded. Moreover, PSKY is down from a recent peak of $11.14 on Sept. 16.
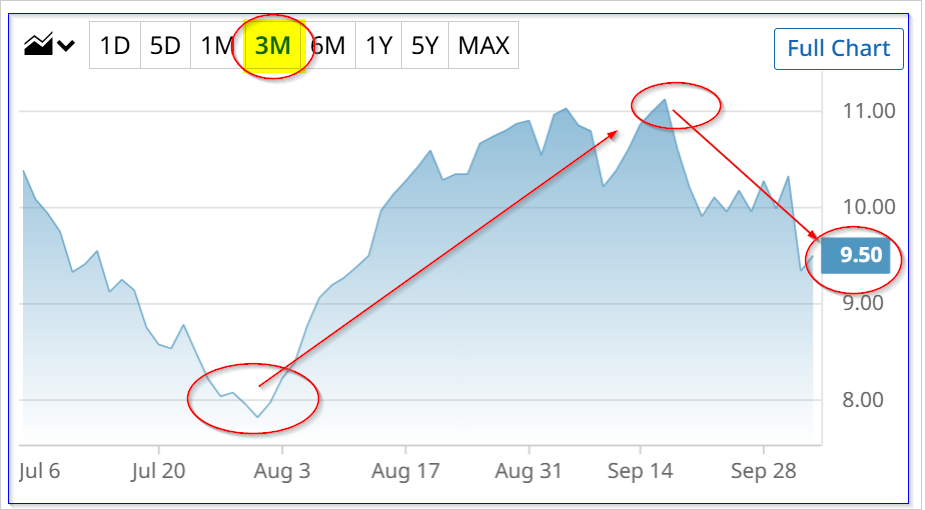
That drop may have piqued investors' interest in these 3-month $9.00 call options, especially given that analysts seem positive on the merger for Paramount.
The huge volume of ITM call options was highlighted in the Barchart Unusual Stock Options Activity Report on Oct. 2, as can be seen below. It shows that over 38,000 call options traded for a $1.21 premium at the $9.00 strike price for the Dec. 18, 2026 expiration date.
That volume is almost 90x the prior number of call options outstanding. It may imply that investors are very bullish on the merger prospects for the combined company.
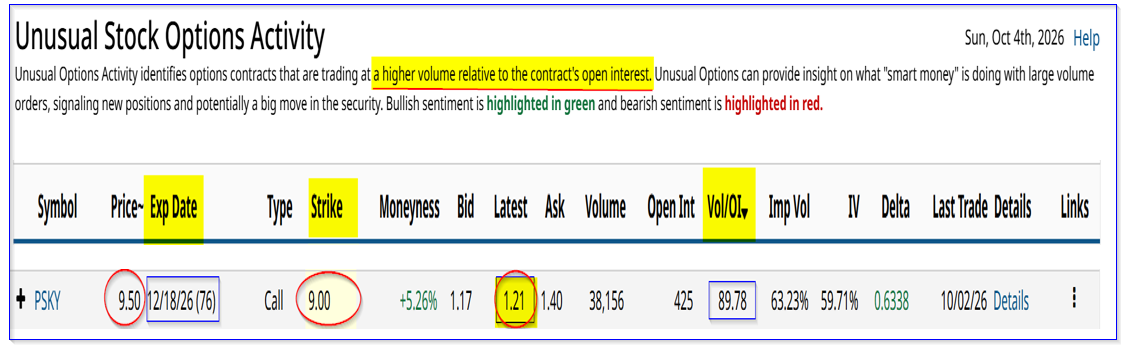
PSKY calls expiring Dec. 18, 2026 - Barchart Unusual Stock Options Activity Report - Oct. 2, 2026
As a result, buyers of these calls (and hoping to exercise them) expect PSKY to rise to over $10.21 ($9.00 +$1.21) on or before Dec. 18.
That's just 7.5% higher than Friday's close. So, any upside in PSKY's stock after the merger could push these call options significantly higher.
Could PSKY rise over 7.5% in the next three months?
Growth and Valuation Forecasts
Investors in these calls may be speculating that PSKY's valuation is not stretched at this point. For example, analysts are now projecting $0.85 in earnings per share (EPS) for next year (ending Dec. 2027).
That's higher than the expected EPS of $0.54 this year. In other words, analysts expect a 57.4% increase in EPS next year as a result of the merger.
That could be one reason why investors are buying these call options.
On the other hand, it may be fully valued today. At Friday's close of $9.50, PSKY is trading on a seemingly low price/earnings (P/E) ratio of just 11.2x.
However, Morningstar reports that the average forward P/E ratio for PSKY for the last 5 years has been 10.78x. That's lower than its present forward P/E.
It could imply a potential 3-4% drop in PSKY's stock price. That assumes the stock drops to the average P/E ratio.
In addition, analysts' price targets are not very high. For example, the average price target (PT) from 22 analysts is just $9.92, according to a Yahoo! Finance survey. That's just 4.4% over Friday's close of $9.50.
However, Barchart's mean survey PT is $10.53. That implies that there is still good upside in PSKY, +10.8%. That is also over the $10.21 breakeven point for this huge call options volume.
Debt Issues
The truth about the merger is that the company will be taking on a massive amount of debt. It is estimated to be over $80 billion to fund the $110 billion merger. Analysts estimate that annual interest costs will be over $6 billion, according to a report by The Deal.
Right now Paramount Skydance only has $14.489 billion in long-term debt on its balance sheet. So, this will be a huge increase in debt. Nevertheless, the CEO David Ellison is reported to have estimated $6 billion in synergies between the two companies.
It may be too early to project the combined company's cash flow, as the closing may also include an equity capital raise. That could lower the amount of debt the company is taking on.
The bottom line is that once the merger closes, analysts are likely to update their forecasts and produce new price targets. The buyers of these call options may be betting on higher PTs, despite the heavy debt burden.
Comments
Log in or sign up to join the conversation.