
Carnival Corp (CCL) generated strong revenue and free cash flow (FCF) for Q3 ending Aug. 31, and CCL stock looks cheap, even after its recent spike. One way to play CCL is to sell short out-of-the-money puts.
CCL closed at $25.76 on Oct. 2, up from a recent low of $21.84 on Sept. 18. After its recent Sept. 29 earnings release, CCL is up 16% from Sept. 22, when it closed at $22.14.
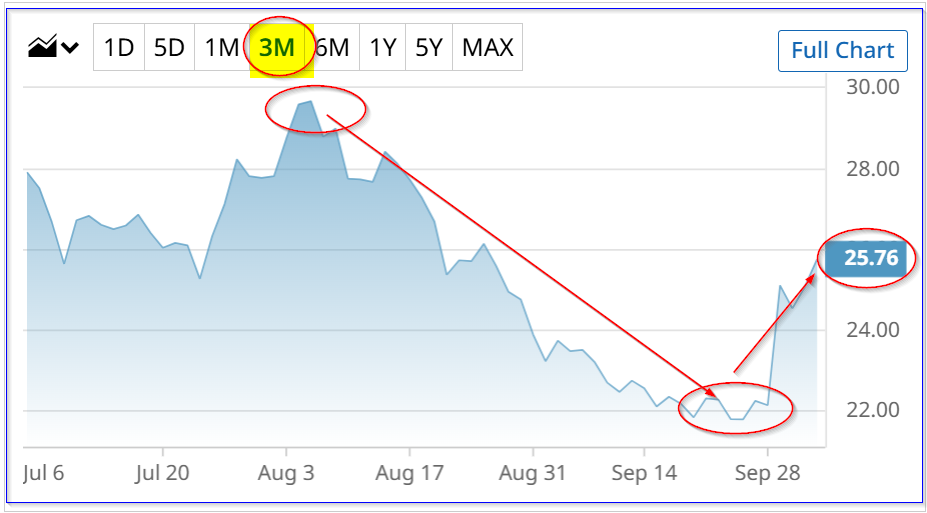
CCL stock - last 3 months - Barchart - Oct. 2, 2026
Strong Revenue, Earnings and Free Cash Flow
Carnival's Sept. 29 quarterly earnings release showed strong results, with Q3 revenue up 5.5% YoY and 6.28% higher for the nine months ending Aug. 31. In addition, Q3 net income was up 3.67% YoY and its earnings per share (EPS) rose 5.26%.
More importantly, it is continuing to generate strong free cash flow (FCF) and FCF margins. Stock Analysis data shows that its quarterly FCF was $712 million, down 3.1%. However, much of its annual FCF is made during Q2, so it's important to look at the company's trailing 12-month (TTM) FCF and FCF margins.
From this standpoint, the company has generated $3.176 billion in TTM FCF, despite higher capex, representing 11.51% of its TTM revenue. That is useful to project FCF for next year.
For example, analysts now forecast $28.60 billion in revenue next year ending Nov. 2027. Using an 11.5% FCF margin, that leads to a FCF forecast of $3.289 billion.
That could lead to a higher valuation for CCL stock
CCL Valuation and Price Targets
For example, using a 12x multiple for its FCF leads to an estimated market value of $39.5 billion. Yahoo! Finance says CCL's market cap is $34.637 billion today. That implies 14% upside and a price target of $29.37 per share (i.e., $25.76 x 1.14).
I discussed Carnival's cheap valuation in a Sept. 22 Barchart article ("Carnival Corp Stock Looks Cheap to Value Investors Ahead of Earnings Next Week").
I showed that CCL could be worth between $24.45 and $29.95 per share based on several valuation methods, including FCF yield analysis and historical price/earnings (P/E) valuation. At the midpoint, that's a target price of $26.95. So, its PT is now 10% higher.
Moreover, analysts surveyed by Yahoo! Finance show an average price target (PT) of $33.93. That's over 31.7% higher than Friday's close. Barchart's mean survey PT is $33.47, implying 30% upside.
Shorting OTM CCL Puts
Investors who shorted out-of-the-money (OTM) puts that I discussed in last week's Barchart article have made money. I had suggested shorting the $21.00 strike price put expiring Oct. 23 for a $0.62 premium. Today, that put premium is down to 8 cents.
This makes it worthwhile for investors to roll that trade into a new short-put play.
For example, look at the Nov. 6 expiry period. It shows that the $23.00 strike price put option, which is over 10% below today's close (i.e., it's out-of-the-money or OTM), has a midpoint premium of 30 cents.
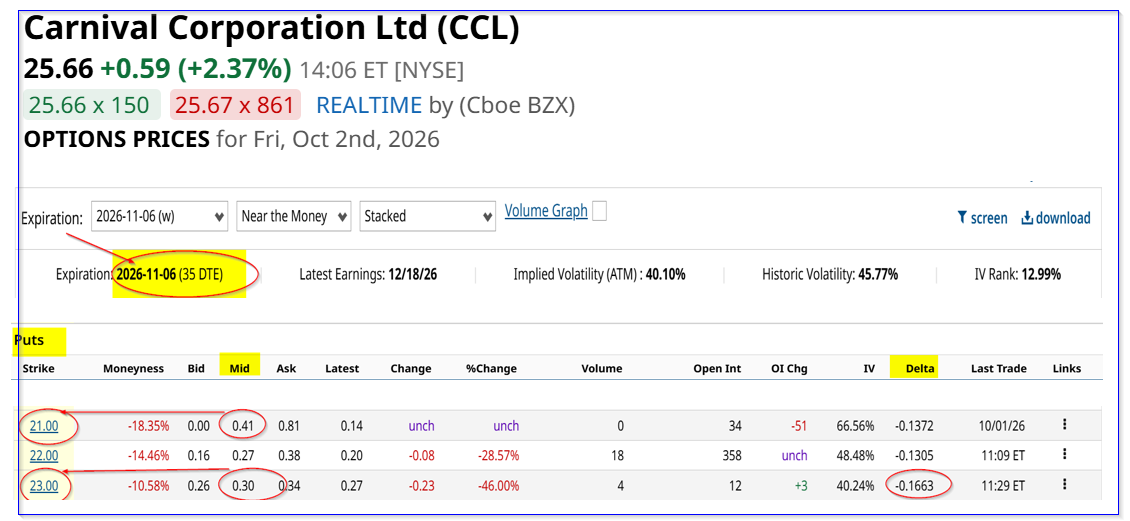
CCL puts expiring Nov. 6 - Barchart - Oct. 2, 2026
That implies a short seller can make a 1.30% monthly expected yield (i.e., $30/$23.00) by entering an order to “Sell to Open” the put. This means the investor has to post $2,300 in order to collect $30.
Note that the delta ratio is very low at just -0.166, implying just a 16.6% chance that the stock will drop to $23.00 by the end of the expiry period. That implies over an 83% chance of profit here.
Moreover, the breakeven point, if CCL drops to $23.00, is $23.00 - $0.30 = $22.70.
This way, an investor can gain extra income, even if they already own CCL shares and after buying back the earlier CCL put trade.
The bottom line is that value investors can make good money shorting CCL puts while also owning CCL shares for upside potential.
Comments
Log in or sign up to join the conversation.