

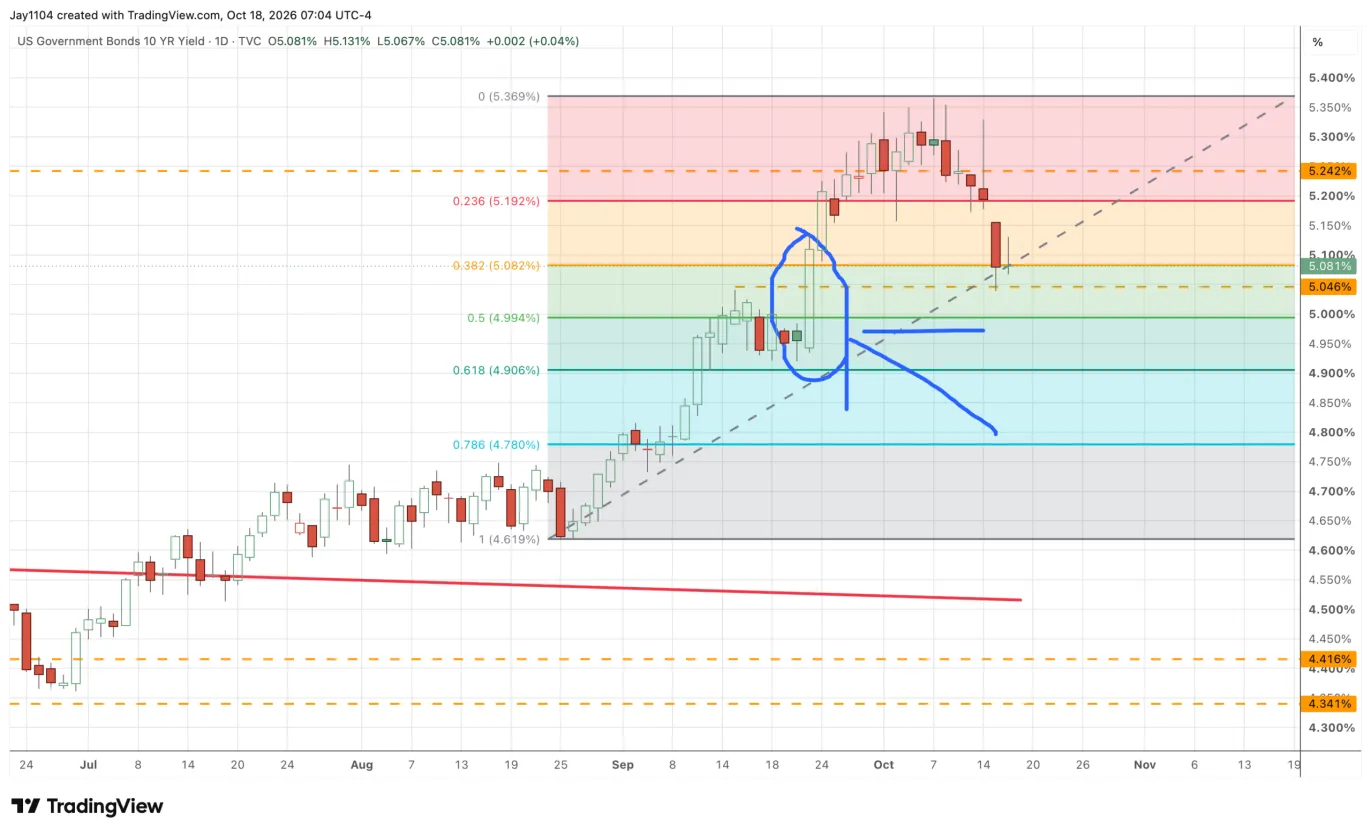
The Fed has entered a blackout period, and that means no speeches. It will also be a very slow week for economic data. The highlight could come Friday when we get the S&P Global Flash PMI reading for October. Remember, the September report sent bond yields soaring, so this is probably the report to watch, and it could have a bigger impact than many think. That was the case last month.
I think many missed that rates didn’t get to where they were from the job or CPI reports alone; the S&P PMI did it, and it shows how expectations for a hot CPI report played into it. So, the case of why rates fell on the CPI report, I think it was a buy-the-rumor, sell-the-news type of event.
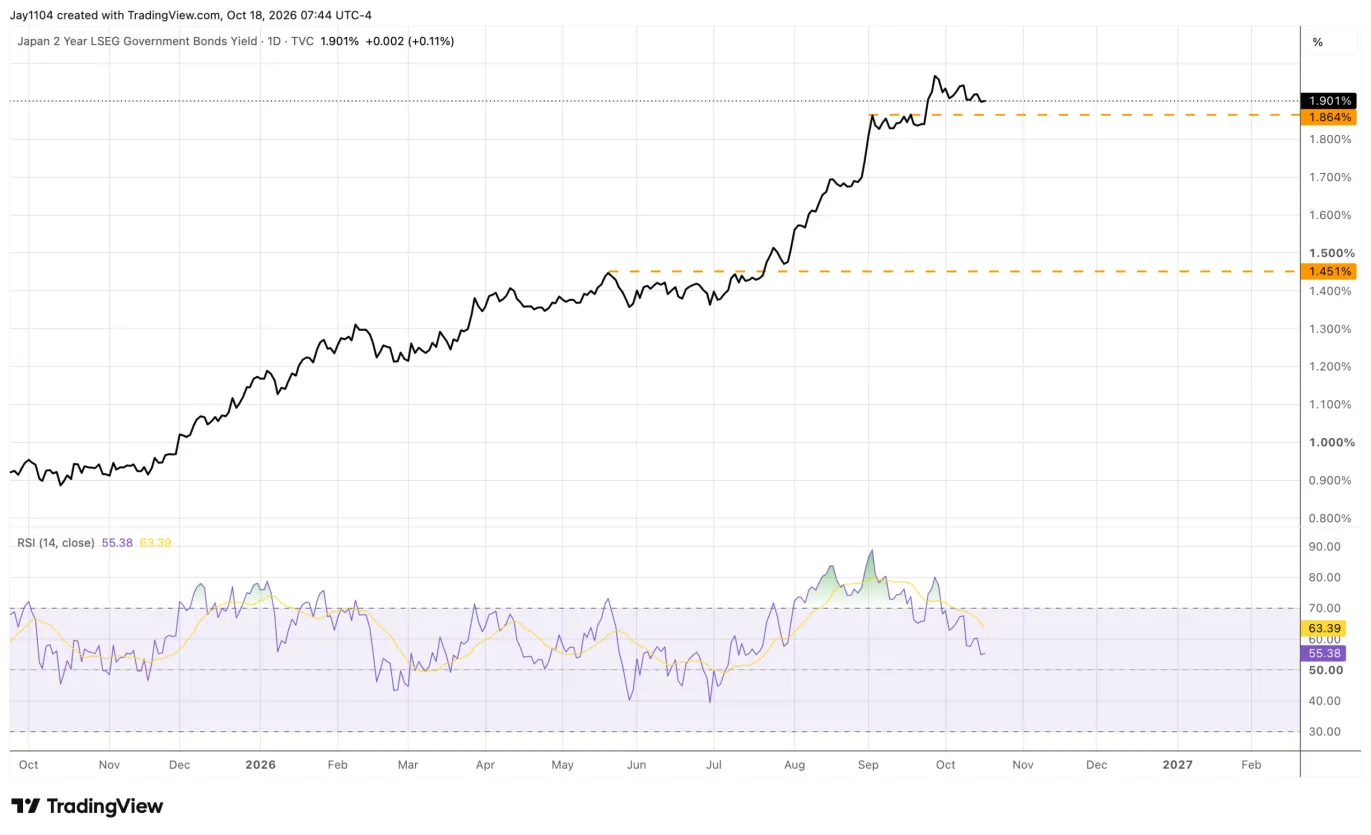
This week will also bring the CPI report from Japan, where both CPI and core CPI are expected to be 2.1% y/y, up from 1.9% and 1.7%, respectively. Bond yields in Japan have fallen sharply as well, so what we saw last week was not just a move in US rates, but a move in global rates. Currently, the BOJ is expected to not raise rates again until December; a hotter-than-expected CPI print could alter that path, which is why it should remain on the radar.
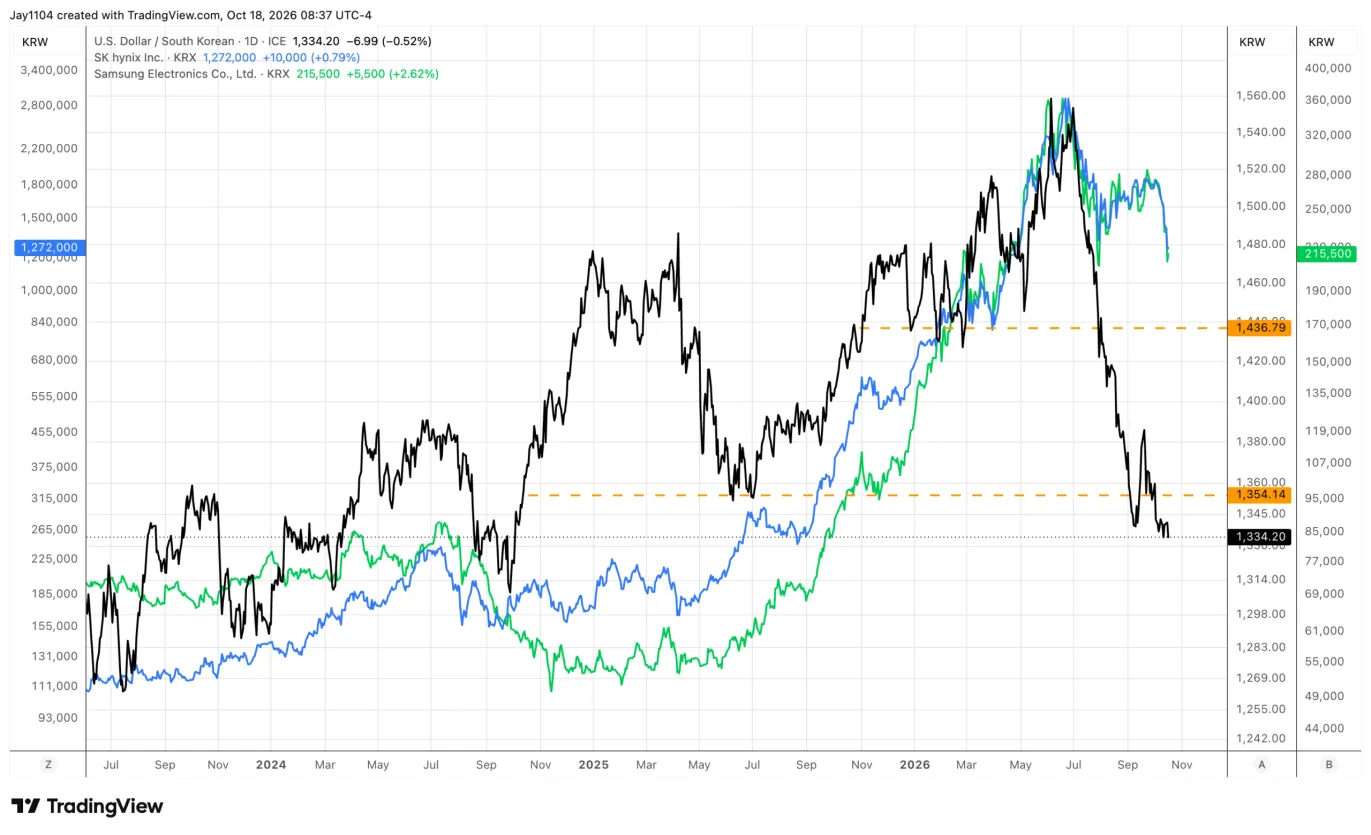
The Bank of Korea meets this week and isn’t expected to raise rates until December; while many may be thinking, “Who cares?” I would argue you should. Look at USDKRW since July, when the BOK signaled more hawkish views on monetary policy; it has fallen materially (strengthening).
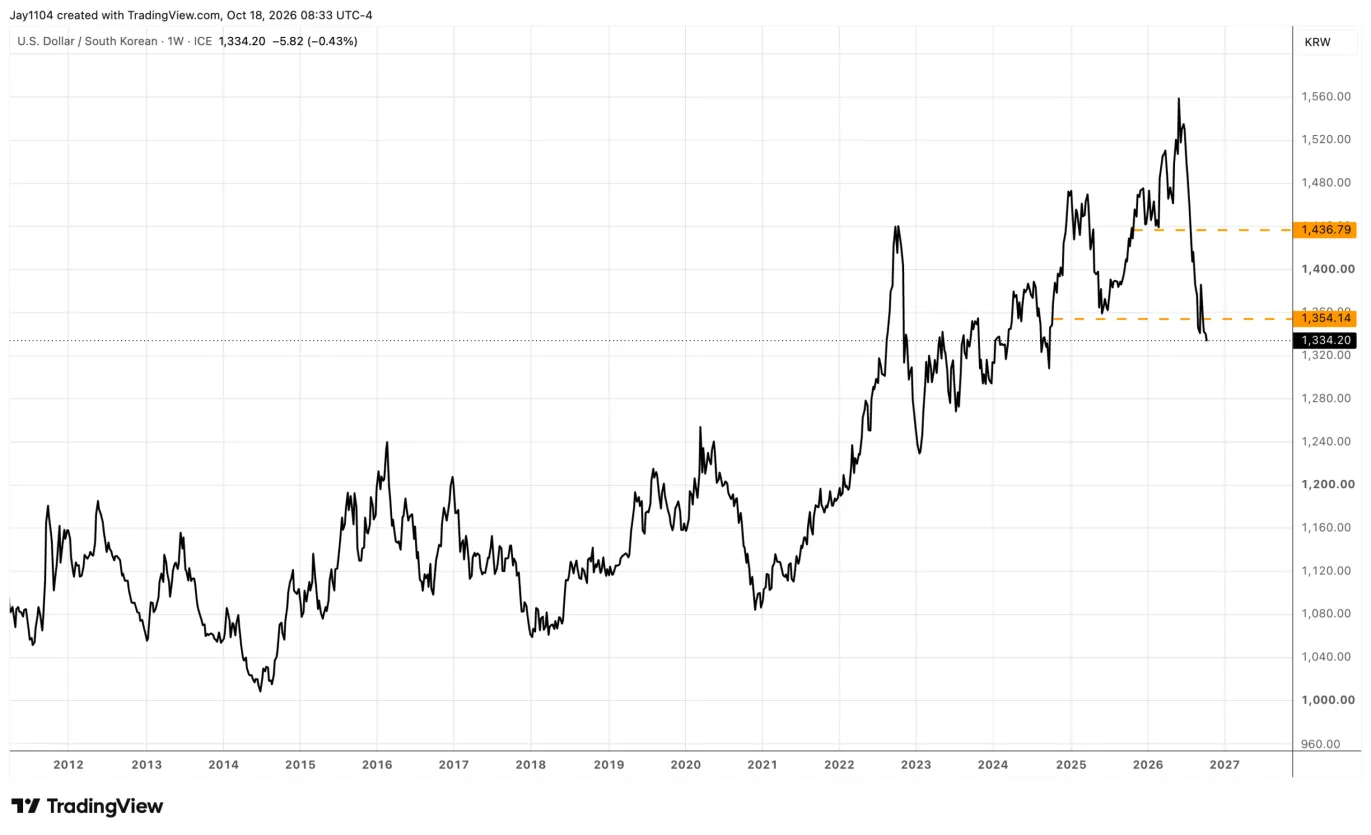
The stronger won isn’t positive for stocks like SK Hynix (SKHY) or Samsung (SSGFF); neither has performed well since the won started that strengthening trend, and since both are the largest in the KOSPI, they haven’t performed well either. That has been the AI trade for the most part, and one has to think that tighter policy in Korea means a strong KRW, which will continue to weigh on Korean stocks.
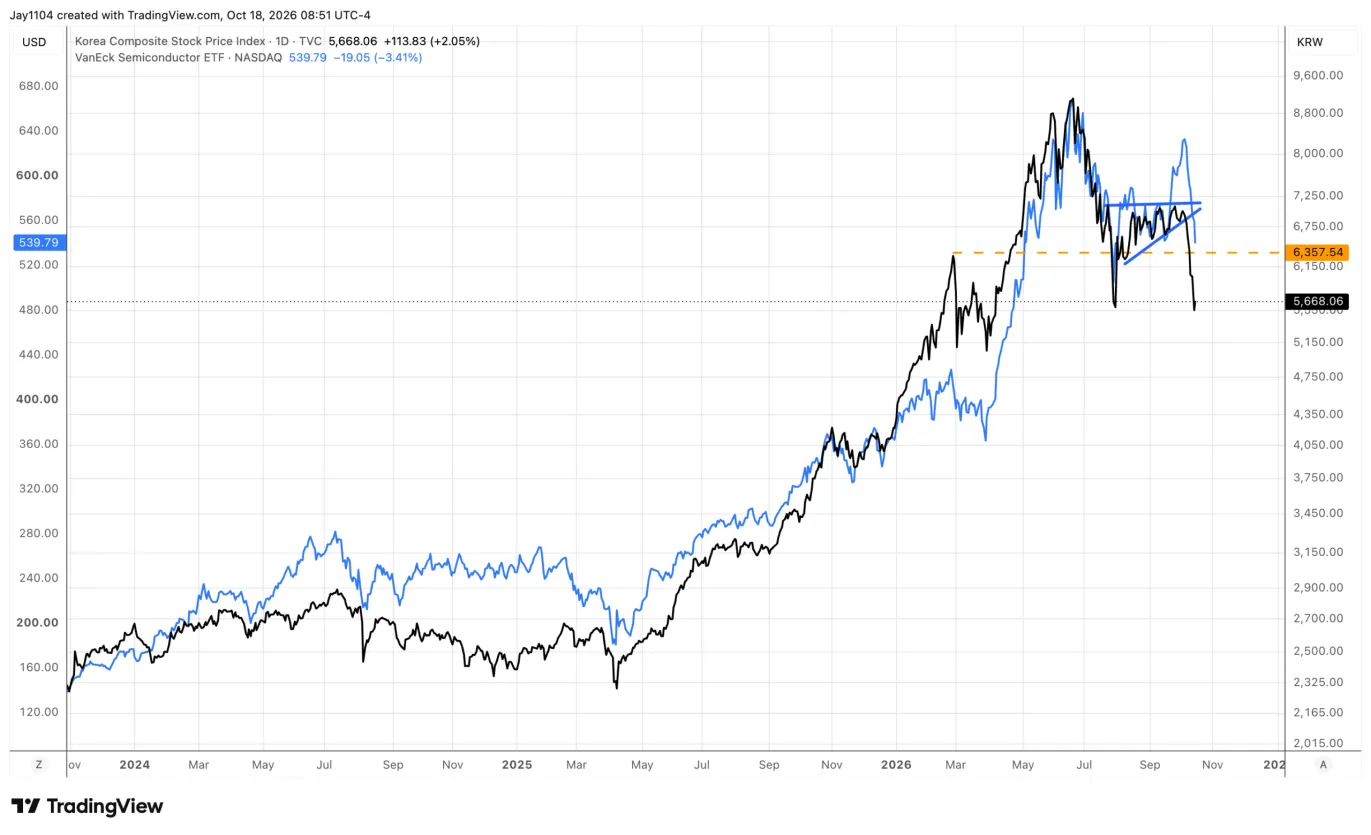
For the most part, whether right or wrong, the KOSPI and the SMH have moved together; you can’t argue with that; the charts make it clear. So as long as the KOSPI struggles, the SMH will too.
Comments
Log in or sign up to join the conversation.