
For years, I’ve tried to do my best Paul Revere imitation, warning readers about out-of-control government spending, and the disastrous effects of never-ending inflation.
I’ve emphasized that we are living on borrowed money, borrowed time, and eventually there will be a currency collapse – and perhaps much worse.
The two most common responses are, “It’s right there in plain sight, why don’t more people see this?” -and- “What can we do about it?”
In the 1970’s President Ford, addressing a joint session of congress warned America:
“We must whip inflation right now,” he said. “I say to you with all sincerity that our inflation, our public enemy number one, will, unless whipped, destroy our country.”
Expecting politicians to control spending and balance the budget is foolhardy. We got a temporary slowdown when Fed Chairman Paul Volcker raised interest rates into double digits to slow down the process:
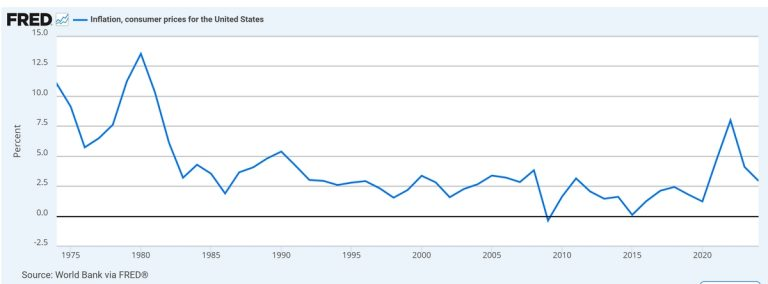
For the last 50+ years, inflation – public enemy #1- has continually robbed wealth from citizens. Truth in Accounting runs the numbers:
“1975–2025: $100 in 1975 is worth only $16.40 in 2025, representing an 84% decrease in purchasing power.”
Quoting Sheila A. Weinberg, Founder and CEO of Truth in Accounting:
“These numbers tell a devastating story. ‘The dollar has been consistently devalued across generations, yet elected officials and media rarely discuss that a $100 Social Security benefit in 1975 has the purchasing power of only $16.40 today, an 84% decline.'”
The Real Inflation Concern
Most people can’t relate to decades old statistics; their concern is inflation today and going forward.
Inflation is comparing the value of a dollar when they earned it, versus what it will buy today and in the future. Workers hope their wages grow ahead of inflation so their net worth is not declining.
Retirees understand their life savings must last for the duration. We’ve seen many surveys concluding, “Americans are more worried about running out of money than death.”
Retirees know government Social Security COLA increases fall woefully short; and feel powerless to do anything to reduce inflation. Instead they downsize, cut back and make do as best they can.
Are We Really Powerless?
Not exactly. Many retirees get part-time jobs to help pay the bills and reduce the drawdown from their life savings.
We are powerless to address the cause of inflation, an out-of-control political class. Candidates vow to reduce inflation; it never happens. No matter who is in charge, inflation marches on.
A currency collapse is inevitable. Politicians always blame their political opponent, but do nothing to change their behavior. Since Nixon took the USD off the gold standard, the political class has spent our nation into debt that cannot be repaid – unless the currency is devalued.
Expecting those who assume no responsibility for creating the problem to fix things is foolhardy. More and bigger government is not the solution to every problem.
You Are Responsible For Your Own Financial Well-Being
Many positive things have happened since the Volcker years. The government has instituted IRAs and 401k type programs to allow people to save and build a retirement fund.
The flaw in the system…..
What is the best way to protect your life savings from inflation? Investing in precious metals…. During the Carter years we saw double digit inflation and gold did the job.
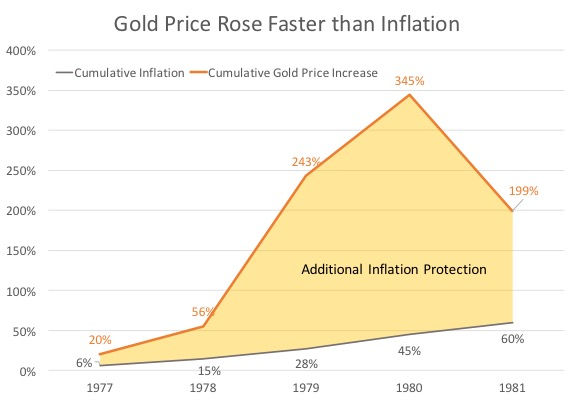
There is a finite supply of gold, silver and precious metals. If a government could find a way to weave gold out of straw, we would have gold inflation!
We are not powerless, we can choose to invest some of our life savings in assets that not only keep up, but also have historically grown well ahead of inflation.
Friend Frank Trotter at Battle Bank shared an eye-popping statistic in their recent Battle Bulletin which really bothers me:
“Despite gold’s spectacular run, including a roughly 65% gain in 2025, its best year since 1979, U.S. investor allocations remain remarkably thin.
Bank of America’s Global Fund Manager Survey found average professional allocations of just 2.4%, with nearly 40% of managers reporting no gold exposure at all. Estimates of gold’s share of U.S. household financial assets run well under 1%.
Morgan Stanley’s headline-making late-2025 recommendation that investors adopt a 60/20/20 portfolio, with gold receiving the same 20% weighting as bonds, was newsworthy precisely because actual positioning is nowhere close to that.”
Today, five casino banks control almost 50% of the nation’s wealth in savings, investment accounts, 401k’s, you name it. While inflation is “public enemy #1”, less than 1% of household assets is devoted to inflation protection despite constant warnings – including Morgan Stanley emphatically recommending 20% of a portfolio should be allocated to gold!
Morgan Stanley recommends 20% allocation, yet the financial community guides their clients to 2.4% – that’s a major flaw!
Why isn’t the financial community protecting their clients?
For years, at various money shows I’d visit booths of Certified Financial Planners and financial firms asking them how they protect their client’s portfolio from losing significant value because of inflation.
While some trumpeted their high-falutin’ computer programs, when pressed, many were honest, but always beginning with, “Don’t quote me, but….”
If you have a company managed retirement plan like a 401k, most workers are given very few choices like “conservative, aggressive, etc.” The overwhelming response is music to the ears of the planner…. “I don’t want to lose money.” Here is why.
The employer, wanting to avoid any potential lawsuits, turns over the management of the plan to an “outside expert” and recognized pension fund manager like Fidelity, Schwab, you name it. The firm allocates the clients money into many of their fee-based funds. They claim diversification among funds is conservative.
I’ve interviewed several professional, fee-based money managers and asked, “Suppose a new client came to you with $1million, how would you allocate their investments?” The process is similar. All (confidentially) said, “We turn the money over to our friends at (a major investment firm) and their specialized computer programs diversify the investments.”
When I specifically asked about gold and inflation protection, the most immediate response was gold was “risky.” Gold, was defined as the whole gamut, from high-risk exploration stocks to owning physical metal. They guide clients away from metals. The 2.4% survey allocation, with 40% of clients having no exposure at all tells the scary story.
When I pressed harder, some opened up (confidentially of course). If their client invests in real metal they don’t earn fees. Several financial managers candidly reported they follow the “conventional wisdom and guidelines” to avoid lawsuits. “The client said they don’t want to lose money.” Another said, if a client presses, they have a waiver form that must be signed abdicating them from any responsibility if they lose money. He grinned, and said, “Normally the form doesn’t get signed and they fall in line.”
The final blow!
Certified Financial Planners emphasize why the CFP designation is important to potential clients. Certified Financial Planners are bound to put their client’s needs ahead of their own. Non CFP’s, like stock brokers and other financial advisors, without the ethical restrictions, have been known to funnel their client’s money into products that earn them higher commissions.
In one memorable situation, I pressed. “OK, I get the commission and ethics part. However, isn’t avoiding the best inflation hedge known to man to avoid potential lawsuits, putting your needs ahead of your clients?”
He responded, “Dennis, if we can show we followed the industry guidelines, our lawyers emphasize we are less likely to lose a lawsuit for mismanagement. We can’t put our entire practice in jeopardy.” I was shocked, but appreciated his honesty – the system is flawed!
We Are Not Powerless!
Investors are responsible for their own well-being, and their nest egg must last for the duration.
I’m not opposed to using financial advisors and diversifying your portfolio – to a point. It takes courage to override professionals and do what you feel is right.
To protect your portfolio from public enemy #1 – INFLATION – we must break from the herd and go outside “conventional wisdom.” Investors who allocate 10-20% of their money to gold, silver, foreign currencies, and other inflation protecting assets will survive and thrive.
If you have 10-20% of your assets invested in inflation protecting assets, what is the downside? You might lose some money in the short term, but over the long haul, the value of the dollar will go down and offsetting investments will rise.
Clarity
While the system is flawed, those I interviewed expressed a sincere and genuine concern for their clients. Many had served their clients for years and were friends. Most financial managers don’t have the time or resources to do real analysis. They delegate the responsibility to a financial firm that uses their computer program to guide the clients’ money into many of their fee-based funds. It’s unrealistic to expect any financial manager to put their entire business at risk from a lawsuit that could put them out of business.
If adequate inflation protection is a concern, we are not powerless. We must act and take a portion of our life savings and invest accordingly, outside of what we have allocated to the professionals. It’s the only way I have found to adequately protect your nest egg from the evils of inflation.
We must take responsibility, learn about alternative investments, and proceed with caution. There’s too much to lose when the house of cards collapses.
On The Lighter Side…
Congratulations to the Milwaukee Brewers; they are headed to the World Series. The Dodgers, with their $430 million payroll were trying for a three-peat, but the Brewers (with 60% lower payroll) swept them in four games. Baseball fans better enjoy the World Series because the labor contract is set to expire. I expect things will likely get very ugly. Baseball is the only major sport without a salary cap and small market teams struggle to compete, knowing they will develop stars they can no longer afford to pay as they move into their prime.
The players association will go to the court of public opinion and decry the billionaire owners are greedy. If MLB ownership is smart, they would calculate total payroll for all teams as a percentage of revenue and offer the players a raise, along with a salary cap and floor. In that manner, the total player payroll would rise but would be allocated differently among teams.
Want to see real world inflation? In 1997, we bought tickets from a broker for the 7th game of the World Series in Miami for $65 each. The last time the Brewers were in the World Series was 1982. Want to see your favorite team again this year?
Stubhub offers seats for the first game in Milwaukee. Nosebleed seats are just under $3,000, field level start at $3,662 with some premium level seats are over $11,000. Somewhere between the prices of entertainment tickets and the phony government 3.6% Social Security Cost of Living increase is the real number……inflation is clobbering the middle class.
Quote of the Week…
“I do not think it is an exaggeration to say history is largely a history of inflations engineered by governments for the gain of governments.” — Friedrich Hayek
And Finally….
We will end this week with some more quotes from the famous philosopher “Unknown.”
|
|
|
|
|
|
|
|
|
And my favorite
A funny thing about getting older, your eyesight may weaken. Yet you can see through peoples BS very clearly.
Until next time…
Comments
Log in or sign up to join the conversation.