
Despite President Trump’s objection, his hand-picked Fed Chairman, Kevin Warsh raised interest rates. NPR reports:
The Federal Reserve raised interest rates for the first time in more than three years Wednesday, in a show of its determination to attack stubborn inflation.
“The central bank raised its benchmark interest rate by a quarter percentage point to a range between 3.75% and 4%.
…. ‘Inflation remains elevated,’ Fed policymakers said in a statement. ‘Today’s policy action will support a timelier return to the Committee’s 2% goal.'”
The market, media and politicos jumped into action. Their hype and garbage just obscure the bigger problem politicos of all flavors have been hiding for years.
We are living on borrowed money, borrowed time, and eventually there will be a currency collapse – and perhaps much worse. |
Politicos know this, but make no attempt to fix things, preferring to focus on the next election cycle and blame their political opponents.
The Great Depression began in 1929 under Republican Herbert Hoover. A major cause was creation of the Federal Reserve in 1913. Easy money led to the “roaring 20’s” and the collapse came on Hoover’s watch. Regardless of who, or what policies caused the mess, the public demanded a change. Franklin Roosevelt was sworn in in 1933, and the democrats ran the show for the next 20 years.
Fixing the problem today would be political suicide, requiring massive spending cuts coupled with tax increases. One constant – politicians are politicians – and their reelection concerns take precedence over what is right for the public. No matter who wins/loses, the public will suffer recovering from impotent politicians and the excesses of their elders.
Some background
Banks collapsed, leading to the Great Depression. Congress took steps to prevent it from happening again. They established the FDIC, protecting consumer bank deposits. They enacted Glass-Steagall, designed to create banking competition and keep banks small enough that a major failure would not cause catastrophic damage to the entire system. The new laws, coupled with the fact the nation was still on the gold standard, worked well for decades.
In 1971, Nixon took the nation off the gold standard, removing much of the spending restraints on congress. Politicians love to borrow and spend, versus making hard decisions regarding taxes, spending and balancing the budget. Ten years later, our national debt topped $1 trillion, unheard of – and mind-boggling at the time.
In 1999, after decades of keeping the banking system safe, Glass-Steagall was repealed. PBS explains:
“After 12 attempts in 25 years, Congress finally repeals Glass-Steagall, rewarding financial companies for more than 20 years and $300 million worth of lobbying efforts. Supporters hail the change as the long-overdue demise of a Depression-era relic.”
The depression era relic worked, no major bank bailouts. $300 million buys a lot of political clout in congress.
Things happened quickly. Big banks gobbled up small banks, creating huge mega banks. Today, five banks control almost half the nation’s wealth with their brokerage arm marketing risky investments to clients. A major banking failure would have a huge impact on the entire world banking system.
Bill Bonner explains the big money game:
“The big bankers wanted to be able to make big bets, but without the risk of going broke. They solved that problem by creating the Fed in 1913. Now, when business is good, they keep the profits. When their bets go bad, they get bailed out by the Fed, generously sharing their losses with the public.”
Less than a decade after the repeal, the banks had taken on so much risk they were on the verge of collapse. Congress had to pass emergency legislation, the Troubled Asset Relief Program, to bail out what was now deemed “too big to fail” banks.
Congress repealed Glass-Steagall which allowed it to happen, but – unlike the Great Depression – took no meaningful steps to address the cause.
PBS continues, explain former Fed Chairman Paul Volcker’s prediction:
“In less than a decade, Mr. Volcker’s fears came true, lenders recklessly lowered loan standards in pursuit of lucrative securities offerings and marketed bad loans to the public – while Congress authorized some $29 trillion, bailing out “too big to fail” banks.”
“The Bank Was Saved, and the People Were Ruined.” — William Gouge, commenting on the Panic of 1819 |
The Federal Reserve flooded the system with trillions in cheap money. Retirees, pension funds etc. who had invested heavily in safe government bonds saw their retirement projections, and in many cases dreams, go up in smoke.
Cheap Money
Theoretically the public was supposed to borrow cheap, spend and stimulate the economy again. David Stockman debunks that theory:
“Anyone who doesn’t imbibe in the Keynesian Kool-Aid dispensed by the central banking cartel can see in an instant that 80 months of ZIRP (zero interest rate policy) has done exactly nothing for the main street economy.
Notwithstanding the Fed’s gussied-up theories…the litmus test is real simple.
…(A)rtificial suppression of free market interest rates by the central bank is designed to cause households to borrow more money than they otherwise would in order to spend more than they earn, pure and simple…
But the whole enterprise is a crock. The consumer spending pump can’t be primed anymore because households reached a condition of “peak debt” at the time of the financial crisis.”
Politicians never feel the pressure of “peak debt” – and went nuts:
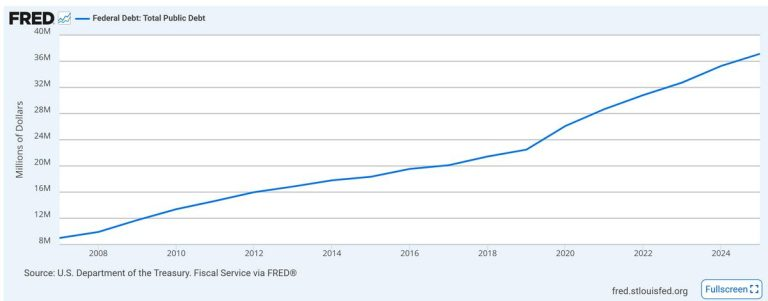
Total government debt has grown around five-fold, currently topping $40 trillion. Since 2000, government debt as a percentage of GDP has more than doubled, and now sits at 123%.
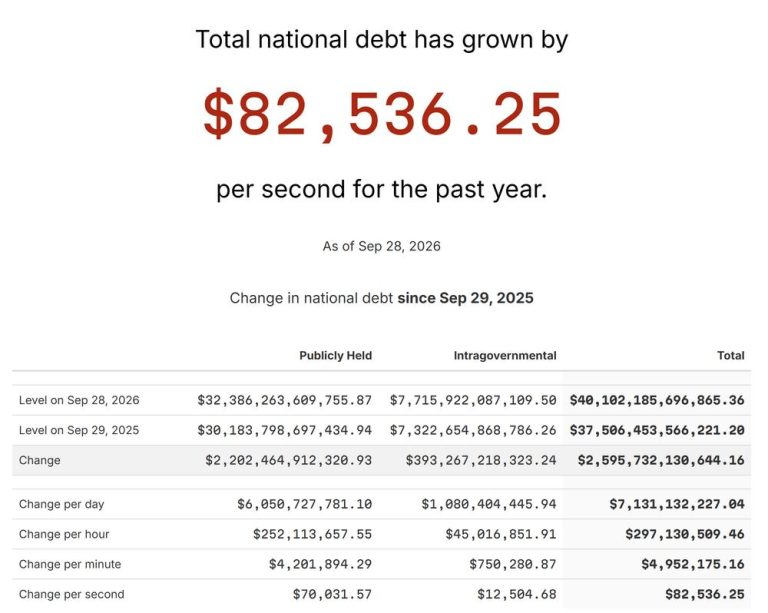
For politicians to continue the illusion, they need a never-ending supply of governments, companies, pension plans and individuals who are fool enough to lend us money – knowing it is impossible to be paid back with the same buying power of the dollar. Inflation must be factored in to the system; $1 when you lent it will buy more than $1 when it is paid back! US debt is growing at a rate of $83,000/second. That is both unsustainable and mind boggling….
The Debt Dashboard shows us the folly:
The Treasury’s Magic Man
Treasury Secretary Scott Bessent announced a buyback of up to $6 billion in long term government bonds at approximately 60% of par value, reducing the deficit by a net $2.4 billion. He must borrow the money, $3.6 billion, at double the current interest rate. In the long run, it will cost taxpayers more in interest.
Our debt increases by over $7 billion per day. Trading low interest bonds for higher interest bonds, will save about 8 hours of congressional spending. My Marine Corps drill instructor would call that worrying about a pimple on a gnat’s ass…..
The World Isn’t Fooled….
The US demand for capital is enormous. Lender’s factor future inflation into their decision. The interest rate should cover the risk of default and inflation. The world is demanding higher rates to lend the US money.
Pundit John Mauldin explains new Fed Chairman Warsh has changed the dynamic:
“While we will never get rid of the FOMC, the chairman is changing the cadence of how they make their decisions. He was very clear in his press conference after the meeting:
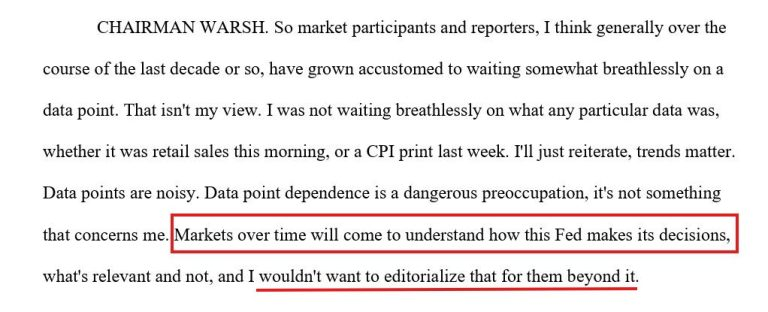
John quotes Fed policy analyst Rene Aninano:
“For decades “the market” has looked to the Fed to determine the direction of interest rates. They waited breathlessly on any speech, any indication of what the Fed would do to try to position themselves ahead of any particular meeting.
Warsh has been clear that he thinks this is backwards. He believes the market should determine the rates and that the Fed should respond to market conditions without trying to insert itself into the equation.” |
While the current Fed increase may help slow the inflation rate; Warsh is also acknowledging the market is demanding higher interest to continue to finance our spending folly.
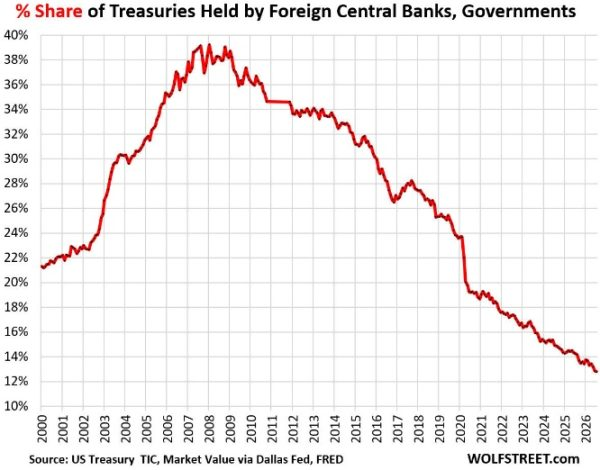
Wolf Street reports:
Treasuries Have Become Badly Unappetizing for Foreign Central Banks & Governments
Gold??
Gold serves the role of inflation protection, as higher inflation appears investors want more gold. When rates go up, gold prices may go down. Bullion Vault supplies us with an updated chart:
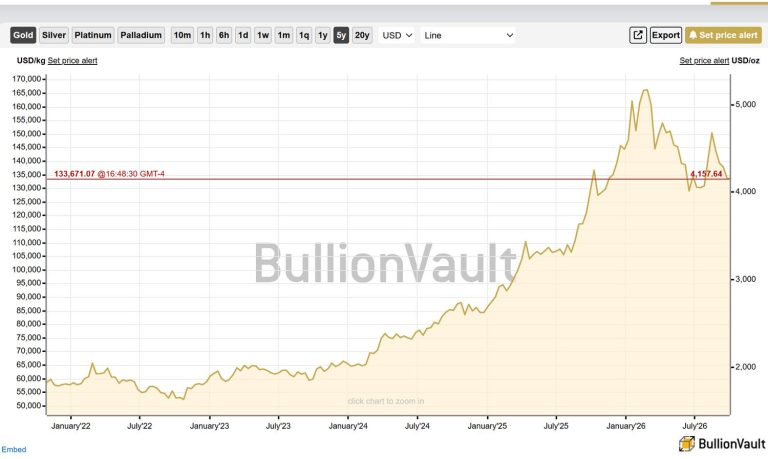
On 9/30/2025 gold closed at $3,833.00. After the rate announcement, gold dropped over 10%, closing on 9/30/2026 at $4,166.60.
TD Securities believes the gold bull run isn’t over, predicting prices over $5,000.
The Constant
Government debt continues escalating at a historic pace with no end in sight. High inflation will follow.
Kitco quotes Ole Hanses, Head of Commodity Strategy at Saxo Bank:
“Instead of triggering another wave of ETF liquidation, investor demand for gold is showing resilience.”
…. This time, therefore, it is not just the gold price that has decoupled from real yields – ETF holdings are showing signs of doing so as well.
…. One explanation is growing concern about fiscal sustainability and rising government debt burdens, Investors may increasingly view higher long-term yields not simply as an attractive alternative to gold, but also as a potential warning signal about fiscal risk, rising debt-servicing costs and financial stability. In that environment, gold’s role as an asset outside the traditional financial system may become more important.”
I’m with Ole. The Fed and Treasury Department try to fool the world, but it’s not working. The US is spending itself into a currency collapse, it’s just a matter of time.
On The Lighter Side…
I anticipated my beloved Cubs season would end last week, they were eliminated quickly by the Padres. The World Series could end on Halloween weekend. Let’s hope the weather is decent.
Our Florida weather is warm, but very overcast and cloudy with afternoon rain. October isn’t the prettiest month, and can often be nailed with some ugly hurricanes. So far, so good. Hoping for good weather.
Went to the cancer center last week and all is well. They said my iron level was a tad low so I’ll be getting a shot. The nurse said it was much easier than trying to eat an anvil….
Quote Of The Week…
“Capitalism should not be condemned, since we haven’t had capitalism. A system of capitalism presumes sound money, not fiat money manipulated by a central bank. Capitalism cherishes voluntary contracts and interest rates that are determined by savings, NOT credit creation by a central bank.”
— Ron Paul
And Finally…
Here’s some quotes from the famous philosopher “unknown” to close out the week:
|
|
|
|
|
|
|
|
|
And my favorite:
The law of common sense – If too many people enjoy the free ride….and not enough people help pull, the wagon isn’t going anywhere!
Until next time…
Comments
Log in or sign up to join the conversation.