
Technology shares suffered severe selling pressure for a second consecutive session as disappointing earnings from Amazon and Intel deepened doubts over the economics of the generative AI investment cycle. Nasdaq 100 futures slid 2.0%—extending the de-risking triggered earlier by Alphabet and Samsung—while capital rotated into US Treasuries, the Swiss franc, and the Japanese Yen. The retreat confirms a fundamental transition from thematic AI euphoria to rigorous cash-flow scrutiny.
Amazon slid 7.3% in after-hours trading, weighed down by concerns over AWS margin durability and heavy infrastructure capex, while Intel plunged 23% on severe execution headwinds and market-share erosion. Across high-beta assets, Bitcoin retreated 0.5% toward $78,400 following temporary deposit and withdrawal halts at Binance amid a potential security probe. The price action demonstrates that equity markets are no longer willing to underwrite massive data center, chip, and power commitments without visible, near-term free cash flow accretion.
The flight to safety pushed sovereign bond yields lower across developed markets. However, the duration rally clashed with a fresh spike in commodity prices: Brent crude climbed 1.4% to $116.45/bbl amid rising risks of resumed US military action against Iran. While lower yields typically signal growth deceleration, crude trading north of $116/bbl injects immediate supply-side inflation pressure into the macroeconomic framework. Precious metals decoupled from the bond bid, with spot Gold slipping below $4,000/oz and Silver shedding 2.0% as leveraged investors liquidated hedges to cover cross-asset margin calls.
Central bank communications reinforced a stagflationary policy dilemma. Following Thursday’s rate hold, European Central Bank President Christine Lagarde delivered an overtly hawkish press conference, emphasizing the “increased magnitude and duration of the energy shock.” With money markets now heavily pricing a 25 bps ECB rate hike in December, Lagarde maintained a strict stance on sovereign fiscal discipline, indicating that the Transmission Protection Instrument (TPI) will not be deployed to shield French OATs from fundamental fiscal repricing. Meanwhile, the Bank of Japan held policy steady, providing temporary stability for the Yen.
Looking to the week ahead, market participants face a dense macroeconomic gauntlet. The Bank of England is widely expected to deliver a 25 bps rate hike on Thursday following strong UK employment, resilient services inflation (3.7%), and a firm composite PMI. In the US, focus centers on Tuesday’s midterm elections alongside a full employment slate—headlined by job openings, ADP, and Friday’s non-farm payrolls—which will test whether resilient growth justifies a December Federal Reserve rate hike.
Macro to Micro: The cross-asset landscape is confronting a toxic combination of megacap tech de-risking and supply-side energy friction. While safe-haven flows are temporarily suppressing Treasury yields, Brent at $116.45/bbl keeps central bankers anchored to a restrictive bias. For traders, the key focus centers on post-market Amazon and Intel follow-through, Brent price action around Middle East headlines, US pre-midterm polling, and incoming Eurozone flash CPI prints.
Overnight Headlines
BoJ Holds Benchmark Rate Steady As Expected After September Hike
Lagarde Reportedly Set To Step Down Early Amid French Political Woes
UK Inflation Expectations Decline In Oct, Citi/YouGov Survey Shows
US Military Presents Trump With Options For Renewed Strikes On Iran
Tanker Hit By Unknown Projectile In Strait Of Hormuz, UKMTO Reports
Iran: Diplomatic Progress Depends On Acceptance Of Seven Conditions
Netanyahu’s Likud-Led Bloc Wins Most Seats In Israeli Election
Ukraine Pauses Strikes On Russian Refineries Following US Pressure
Oil Rises On Prospect Of Renewed US Military Action Against Iran
Exxon And Chevron Executives Cancel ADIPEC Trips Amid Regional Tensions
Treasuries Extend Rally Alongside Global Bonds As Technology Stocks Decline
Microsoft Plans To Raise $25B Through US Bond Issuance
Amazon Fall As Q4 Sales Forecast Misses Estimates And Cash Burn Rises
Intel Shares Slide On Weak Earnings And Disappointing PC Market Outlook
Nvidia In Talks To Back Nscale’s $45B Anthropic Financing Deal
Bitcoin Falls After Binance Reports Potential Security Breach
FX Options Expiries For 10am New York Cut
(1BLN+ represents larger expiries and is more magnetic when trading within the daily ATR.)
Friday 30/10
EUR/USD: 1.1075 (EU1.6b), 1.1100 (EU1.8b), 1.1125 (EU989m), 1.1150 (EU5.6b), 1.1170 (EU696m), 1.1175 (EU2.2b), 1.1200 (EU4.5b), 1.1225 (EU737m), 1.1250 (EU762m)
USD/JPY: 157.00 ($1.2b), 157.50 ($831m), 157.80 ($619m), 158.00 ($2.1b)
GBP/USD: 1.3300 (GBP726m)
USD/CHF: 0.8325 ($610m)
USD/CAD: 1.4025 ($791m), 1.4040 ($701m)
AUD/USD: 0.6925 (AUD612m), 0.7000 (AUD614m), 0.7025 (AUD1.2b), 0.7075 (AUD600m)
Monday 02/11
EUR/USD: 1.1150 (EU2.7b), 1.1175 (EU660m), 1.1200 (EU901m), 1.1250 (EU654m)
USD/JPY: 157.00 ($1.5b), 158.00 ($1.2b)
USD/CHF: 0.8300 ($952m)
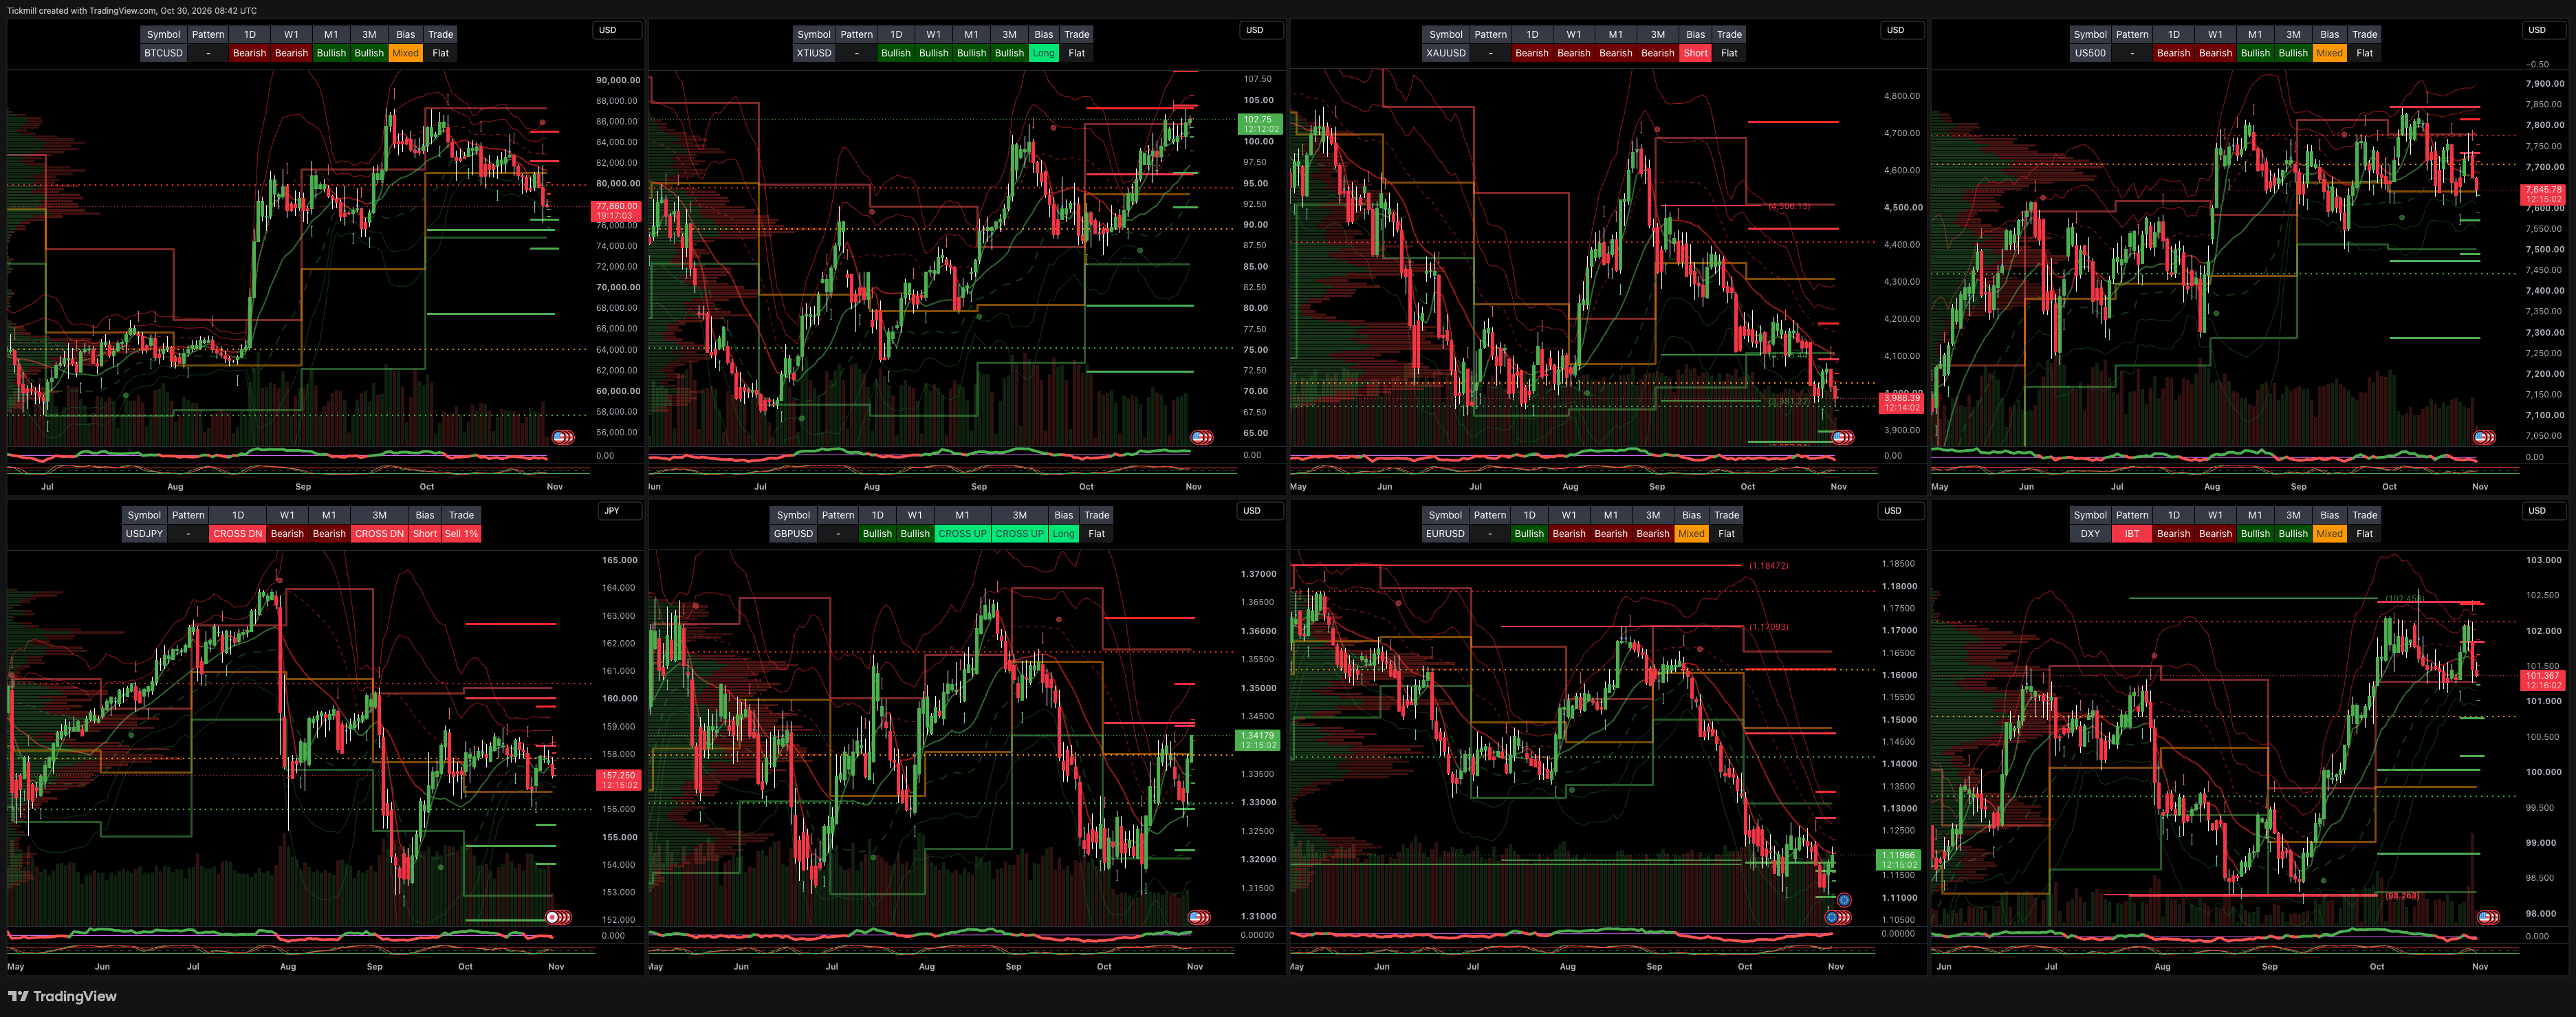
Technical & Trade Views
Comments
Log in or sign up to join the conversation.