
Global equity markets attempted a tentative stabilization on Thursday morning as blockbuster pricing for Anthropic’s historic initial public offering provided tactical relief following five consecutive losing sessions on Wall Street. After the S&P 500 slipped 0.2% to 7,324 and the Dow Jones Industrial Average shed 1.1% on Wednesday, US equity futures rebounded into the European open—led by a ~1.5% bounce in Nasdaq 100 contracts and ~0.8% gains in S&P 500 e-minis. Anthropic priced its Nasdaq debut (ticker: ANT) at $83 per share—well above its $70–$78 marketed range—to raise roughly $81bn in the largest IPO on record, proving that institutional capital remains hungry for frontier artificial intelligence models even as hardware sentiment wobbles.
However, regional divergence across Asia-Pacific underscored that IPO relief has not resolved underlying semiconductor stress. Taiwan’s Taiex plunged over 4.0%, forcing financial regulators to enact emergency short-selling restrictions as investors continued to mark down hardware exposure amid Nvidia’s ongoing leadership vacuum and US export-control scrutiny. Hong Kong slid ~2.0% and South Korea’s Kospi traded softly, leaving Japan’s Nikkei 225 (+0.6%) as a rare regional outperformer. European futures pointed to a modestly firmer cash open (DAX contracts near 25,870), though fragile market structure constrained conviction. With S&P 500 spot pinned below key gamma-flip thresholds (7,500–7,520) and net dealer gamma deeply negative, index price action remains mechanical and fragile: failure to sustain a reclaim of the 7,400 call wall leaves the tape vulnerable to renewed downside liquidation.
An unyielding Federal Reserve continues to govern fixed income and currency markets. Wednesday’s October FOMC minutes confirmed that nearly all officials anticipate further rate hikes to return inflation to target, with two participants even floating the risk of a 50 bps move in December if price pressures persist. Crucially, policymakers took comfort from tighter market-implied rate paths doing the Fed's heavy lifting—meaning any sustained AI-driven easing in financial conditions risks provoking a sharper monetary pushback. In a notable macro-prudential shift, Fed staff also flagged growing financial-stability vulnerabilities tied to debt-funded AI infrastructure and supply-chain leverage.
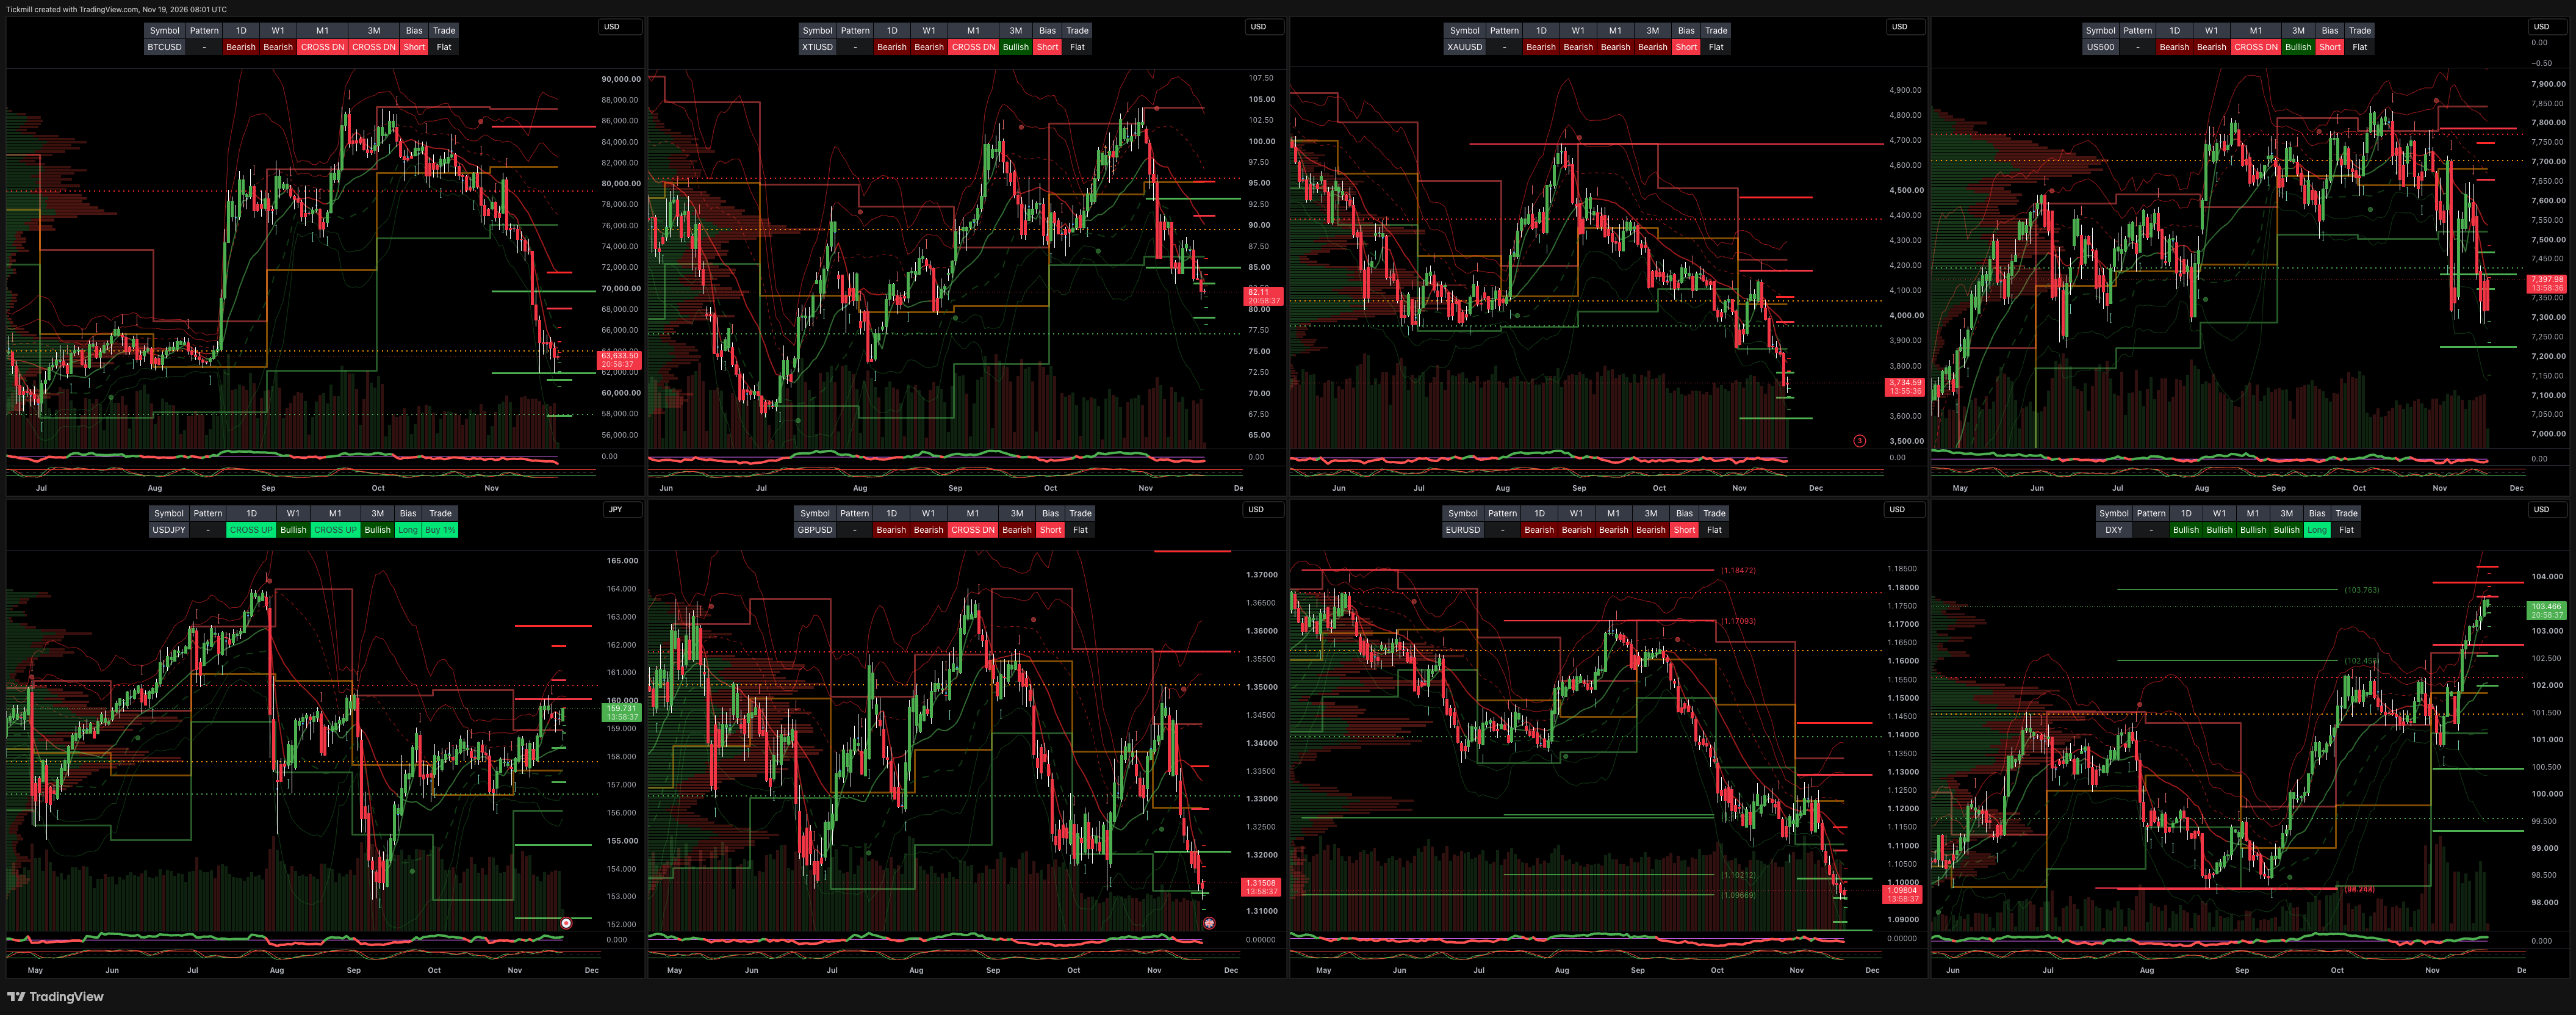
Cross-asset pricing reflected this restrictive rate regime. While softer crude—WTI near $83/bbl and Brent around $92.50/bbl following US inventory builds—offers headline relief, sticky core services and import-price pressures keep the US Dollar well-bid. Elevated real yields continued to crush non-yielding hedges, driving spot Gold to a 14-month low near $3,730/oz, while Copper dipped on soft Chinese industrial momentum. Across the Atlantic, yesterday’s benign UK October CPI print (3.6% headline, 3.7% services) gives Bank of England Governor Andrew Bailey room to anchor market expectations around February rather than December for the next rate hike, though an accelerating maturity cliff in low-coupon gilts threatens acute cash and repo squeezes for sterling desks.
Macro to Micro: Financial markets are caught between a record-breaking private-to-public AI liquidity milestone and a Federal Reserve actively guarding against premature financial-conditions easing. While Anthropic’s $83 pricing validates frontier model demand, negative dealer gamma and hardware supply-chain friction prevent a clean all-clear. For traders, immediate tactical focus centers on ANT’s aftermarket trading execution, S&P 500 resistance at 7,400 against 7,300 put support, today’s US weekly jobless claims and Walmart consumer read-through, Alibaba’s post-close cloud print, and low-coupon gilt repo scarcity.
Overnight Headlines
Trump Weighs Fresh Strikes On Iran As Israel Presses For Action
US Intelligence Director: Threats From Iran Have Increased Substantially
Iran Says Three Tankers Caught Fire After Hitting Mines East Of Hormuz
Trump Says He Would Not Make Deals With Putin Without Ukraine
UK Pledges Long-Range Missiles To Ukraine Despite US Criticism
Trump Pushes For China Nuclear Arms Curbs At Xi-Putin Summit
Trump Suggests US Could Sell Nvidia Blackwell Chips To China In Future
Fed Minutes: Some Officials See Need For Larger Rate Increase
Fed's Barr Says Further Interest Rate Rises Likely Ahead
Foreign Holdings Of US Treasuries Fall By Most Since March
BoJ's Ueda Unfazed By Consumption Weakness, Remains Open To Hike
Australian Unemployment Jumps To 4.9% After RBA Rate Hikes
Pound Hits One-Year Low As Traders Pare BoE Rate Hike Bets
Anthropic Reportedly Prices IPO At $83 Per Share – BBG
Anthropic Raises $3B In Japan Tranche Of US Mega IPO
Moody's Cuts Nvidia Ratings Outlook To Stable From Positive
Arm CEO Rene Haas Approached By Nvidia Board's Recruitment Firm
UniCredit, Germany Reach Broad Agreement On Commerzbank Takeover
Palo Alto Networks To Buy AI Startup Applied Compute For $4.5B
Deutsche Bank's Italian Unit Allegedly Concealed Mortgage Losses
Technical & Trade Views
Comments
Log in or sign up to join the conversation.