
The Reserve Bank of India is widely expected to deliver a 25bp rate hike. Markets will also be watching inflation data from the Philippines, household spending and external-sector figures from Japan, and inflation and trade releases from Taiwan
India: RBI expected to hike rate by 25bp
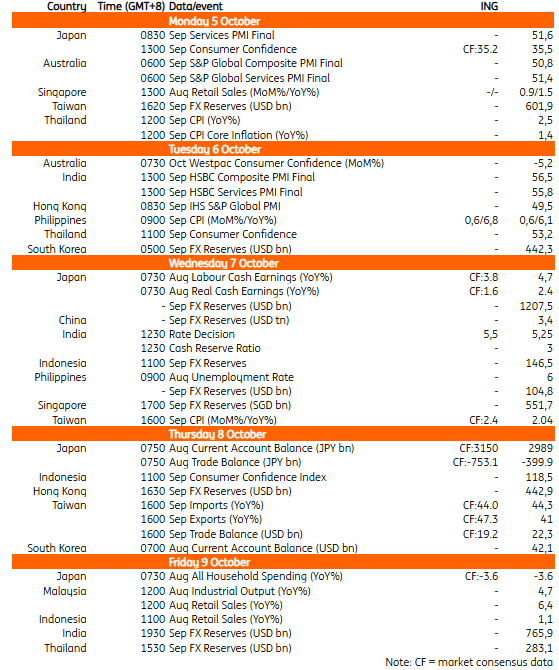
The Reserve Bank of India is likely to begin its tightening cycle on Wednesday with a 25bp hike in its policy rate to 5.5%, after holding rates steady since December. Rising oil and a sharp pickup in food prices are expected to push CPI inflation back above the RBI's target range in the fourth quarter. While the inflation shock is largely supply-driven, we expect the RBI to raise rates to prevent inflation expectations from de-anchoring. Markets will be focused on the RBI's guidance on the extent and duration of the tightening cycle.
Philippines: Inflation to rise on food and fuel pressures
Fuel and El Niño-related food price pressures are likely to push Philippine inflation higher to 6.8% year-on-year in September, from 6.1% in August. Domestic fuel prices rose by more than 15% during the month, while adverse weather conditions continue to drive up food costs, particularly rice.
Japan: Wages, spending, external balances in focus
Japan releases a range of household and external-sector data. Market consensus sees consumer confidence edging down to 35.2 in September. Labour cash earnings growth is forecast to moderate to 3.8% YoY in August, while real cash earnings are expected to remain positive but slow to 1.6% YoY. The current account surplus is expected to widen to JPY 3150bn, supported by overseas investment income, despite the trade deficit widening to JPY 753.1bn. Meanwhile, household spending is expected to remain weak, declining 3.6% YoY, highlighting continued pressure on domestic consumption.
Taiwan: Export growth to remain strong
Taiwan releases September inflation and trade data. Market consensus expects headline CPI inflation to accelerate to 2.4% YoY, from 2.04% in August. Export growth is forecast to strengthen to 47.3% YoY, from 41.0%, supported by continued demand for semiconductors and other electronic products. Imports are seen remaining broadly stable at 44.0% YoY, compared with 44.3% previously. The trade surplus is forecast to narrow to $19.2bn, from $22.3bn in August.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.