

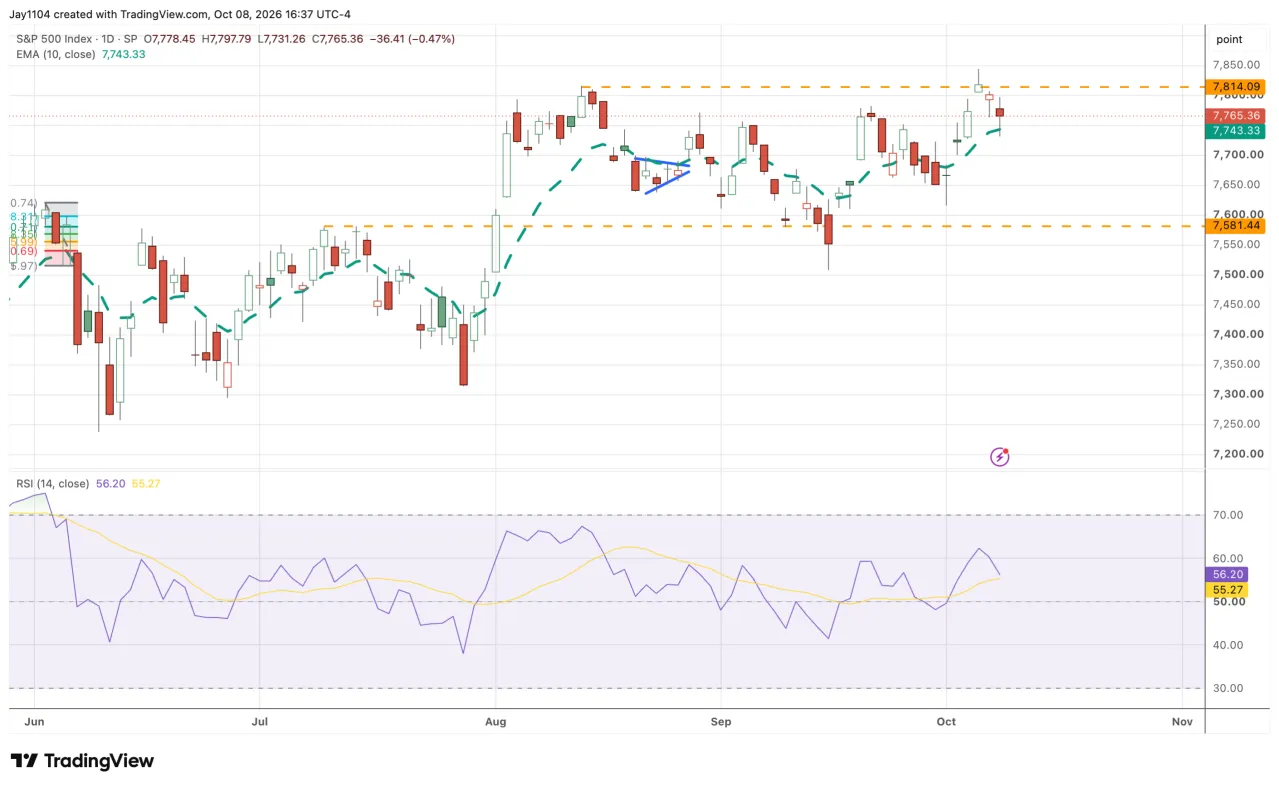
S&P 500 finished the day lower but remains above the 10-day exponential moving average, so nothing material has changed for the index at this point. A break below that average could signal a shift in the recent trend and further downside. Until then, today’s decline appears relatively insignificant.
Technically, the potential double-top pattern stands out, but it remains unconfirmed. A drop below 7,500 would confirm it.
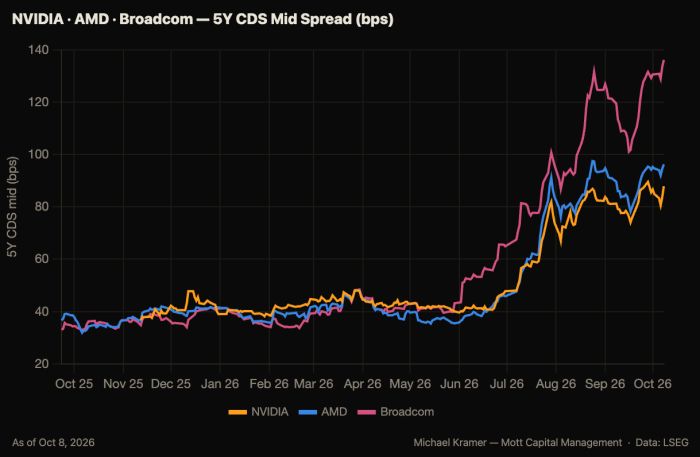
Credit default swap spreads are widening again, with those for Nvidia (NVDA), Broadcom (AVGO), and AMD all moving higher. In some cases, spreads are exceeding their previous highs.
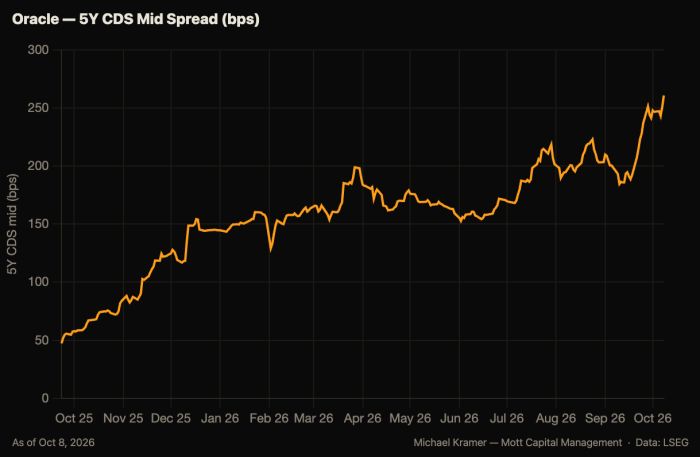
Oracle (ORCL)’s five-year CDS spread is now above 260 basis points, surpassing its previous highs. Based on the assumed recovery rate, that implies a 19.5% market-implied probability of default over five years—a significant level of perceived credit risk.
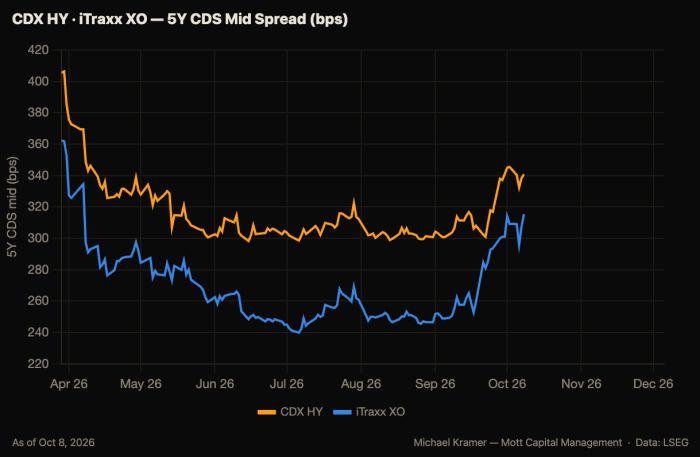
After a couple of days of easing, credit spreads widened today, including those on the CDX High Yield and iTraxx Europe Crossover indexes. I think relatively tight credit spreads help explain why stocks have avoided more pain as yields have risen. I’m not sure how much longer equities can shrug off widening spreads, but if the widening continues, I would expect it to feed into higher implied volatility.
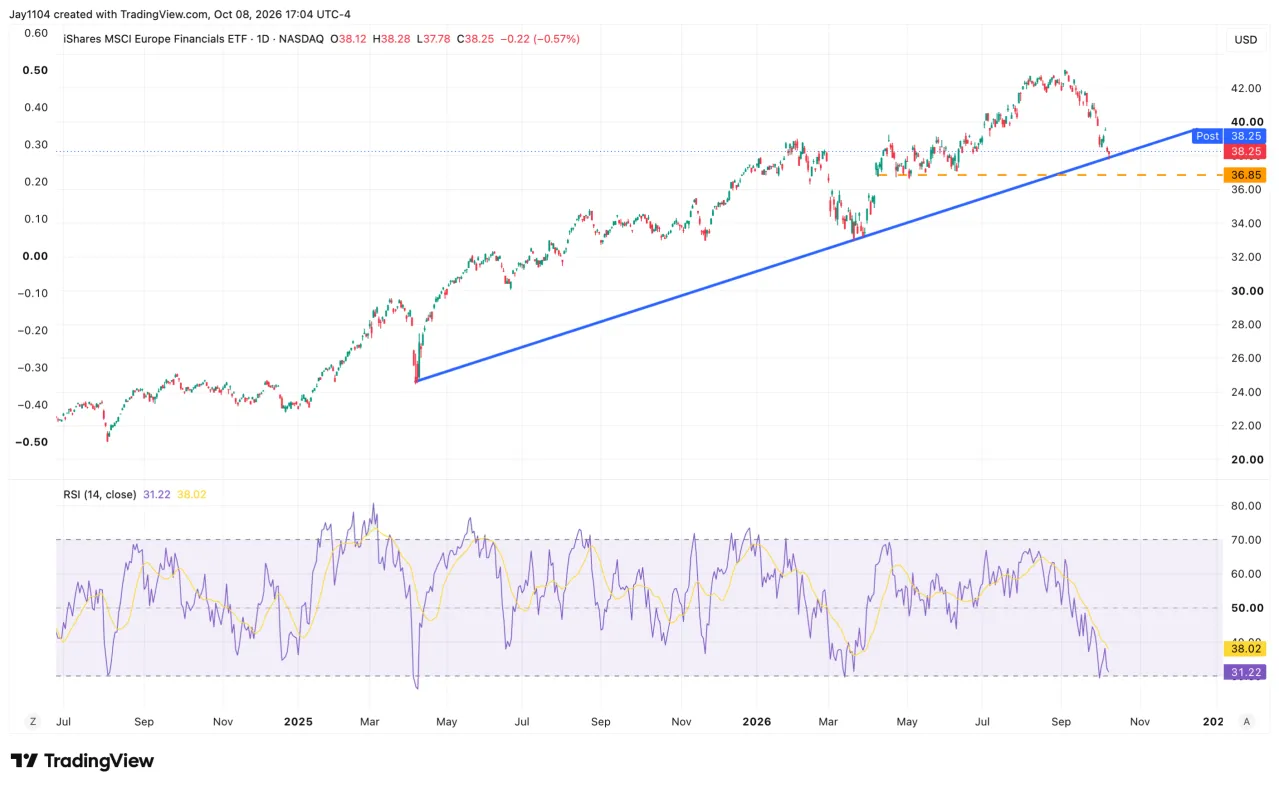
US banks aren’t the only ones struggling; the European Financials ETF (EUFN) is under pressure too. It is sitting on an important trendline, and a break below that support could signal significantly more downside for the sector.
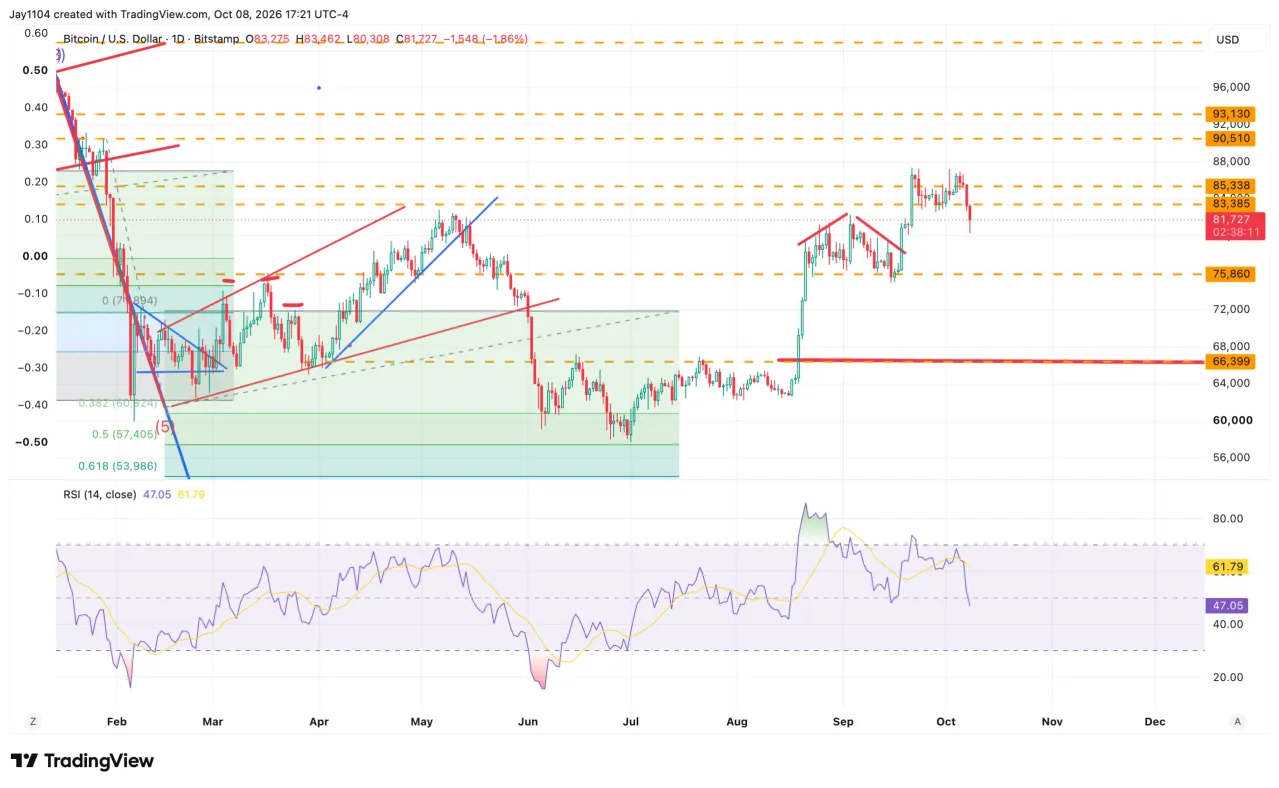
Finally, a friendly reminder that today brought $13.7 billion in T-bill settlements. That amount jumps considerably next week, with $36.5 billion on Tuesday and another $32.6 billion on Thursday. Let Bitcoin (BTC.X) lead the way—probably lower.
Comments
Log in or sign up to join the conversation.