
FTSE climbs ahead of the BoE boosted by banks and miners
FTSE 100 futures are on the rise, extending gains from the previous session as investors continue digesting the fallout from the U.S. midterm elections and look ahead to the Bank of England rate decision.
The FTSE jumped 1.8% on Wednesday and trades 0.8% higher on Thursday, surpassing the previous record closing high set in February.
The rally comes as bond yields continue to decline and oil prices hover around a two-year low. Oil prices have fallen sharply on expectations that a Democratic Congress in the U.S. could increase the chances of the war in the Middle East ending. As a result, oil fell 8% yesterday. While prices have ticked up 1% today, they are holding on to most of those losses. This has helped ease inflationary concerns and pull bond yields lower, supporting demand for riskier assets such as stocks.
Energy stocks on the FTSE are trading lower.
Precious metals have rebounded firmly after the US midterm elections, with gold back above $4000. This is supporting miners higher.
Attention is now turning to the BoE rate decision. The BoE is expected to hike rates by 25 basis points to 4%, marking its first hike since August 2023.
The decision comes as UK inflation has risen to 3.5%. Core inflation is also higher, while services inflation stands at 3.7%, pointing to elevated domestic price pressures.
With the hike fully priced in, attention will be on the vote split, which is expected to be 7–2. Updated growth and inflation forecasts, as well as comments from Bank of England Governor Andrew Bailey, will offer clues about the path forward for rates. The market is pricing in four hikes between now and the end of 2027, which could be considered aggressive. Should the Bank of England look to rein in those expectations, this would be a dovish hike and could be beneficial for the FTSE.
However, a hawkish-sounding Bank of England, accompanied by an upward revision to inflation forecasts, could be considered a hawkish hike, which would be negative for housebuilders and consumer discretionary stocks but could lift bank stocks higher, which have massively underperformed in recent months.
FTSE forecast – technical analysis
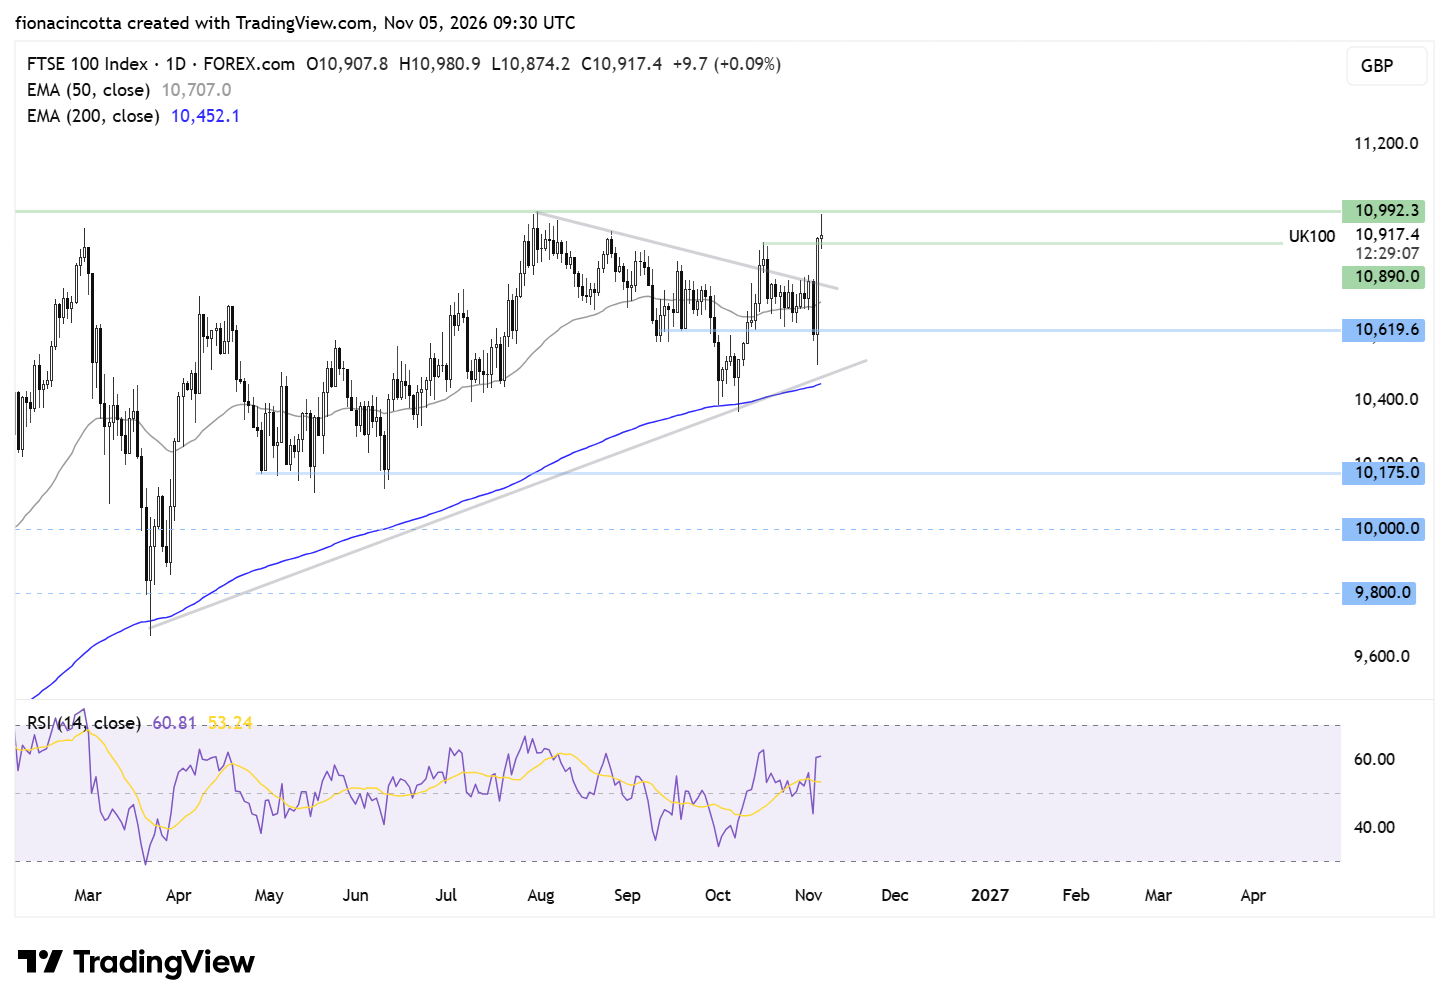
The FTSE has once again broken out of the symmetrical triangle pattern, rising to within a whisker of its record high at 10,980.
The price has since eased back to 10,920. It remains above support at 10,900, as well as above its 50 and 200 EMAs, keeping the outlook constructive.
Buyers will look to extend gains above 10,990 to fresh record highs.
Sellers will be keeping an eye on the potential formation of a shooting star candle, which may suggest that demand at higher levels was weak. Immediate support can be seen at 10,900, the October high. A break below here exposes falling trendline support at 10,750 and the 50 EMA at 10,700. A break below 10,600 horizontal support opens the door to the 200 EMA at 10,450.
EUR/USD rises as oil prices fall but gains could be limited
The euro/U.S. dollar is rising for a fourth straight session on Thursday, lifted by falling energy prices and hopes that the Iran conflict could de-escalate following the Republicans' loss of control of Congress in the U.S. midterm elections.
The market is seeing a Democratic Congress as a potential path towards a resolution of the conflict, helping to restore oil flows that have been disrupted by the ongoing war.
However, this is by no means a done deal. Given the limited domestic power Trump could have, he may turn his attention to foreign policy and escalate tensions with Iran following the election.
Oil prices fell 8% yesterday. However, the other side of this coin is that falling inflationary pressures could temper expectations for further ECB monetary policy tightening.
It is worth keeping in mind that concerns over France's fiscal trajectory and its ability to cut its budget deficit could also limit the upside in the euro. Protesters are expected to march through French cities, and public workers are on strike today.
The U.S. dollar is falling further on Thursday and trades at its lowest level since September.
Following the midterm elections, questions remain over AI, the pace of AI implementation going forward and the potential for less government spending, helping Treasury yields move lower.
However, the Federal Reserve's interest rate path remains largely intact, with the market pricing in an 80% chance of a 25-basis-point hike at the December meeting.
Jobless claims data is in focus later today, ahead of tomorrow's nonfarm payroll report.
EUR/USD forecast – technical analysis
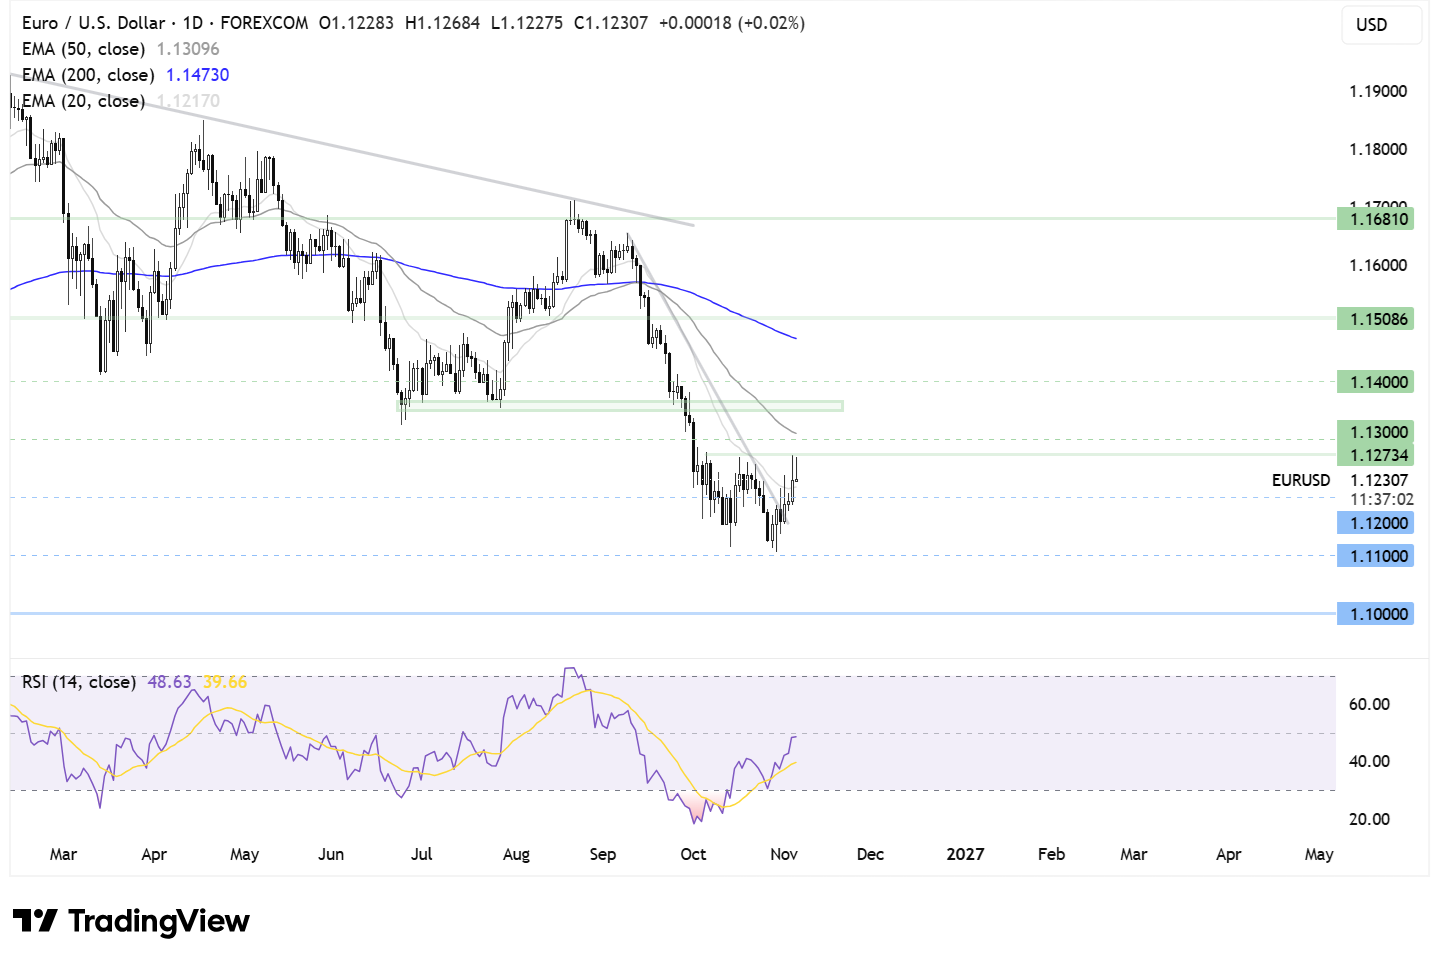
EUR/USD recovered from the 1.11 low, but ran into resistance at 1.1270, the mid-October high. The near-term outlook has improved as the price rises above its falling trendline. However, its 20 EMA remains below the 50 and 200 EMAs, keeping the longer-term outlook bearish.
Buyers would need to retake 1.1270 and the 1.1300 round number, as well as the 50 EMA, to put the price on a firmer footing towards 1.1350.
Sellers may be encouraged by the long upper wicks on recent candles, suggesting that buying demand at higher levels has been weak. Immediate support is seen at the 20 EMA at 1.1220, ahead of 1.1200. A break below here opens the door to 1.1100.
Comments
Log in or sign up to join the conversation.