
FTSE underperforms as miners slide and inflation rises
European stocks are mixed as investors weigh upbeat forecasts from AI chipmaker Nvidia, which are helping to lift the battered tech sector. However, this is being offset by a sell-off in miners, while the UK is also digesting cooler-than-expected inflation.
Tech stocks are rising, and sentiment has brightened after Nvidia, the bellwether of the AI trade, reported impressive quarterly results and an upbeat outlook, offsetting concerns over turmoil at the top level. Nvidia posted revenue of $115.8 billion, doubling from a year earlier and beating expectations. Q4 revenue is expected to come in at $126 billion to $134 billion, above the $125 billion expected, highlighting strong AI demand.
The European tech index is rising 1.2%, with ASM International up 2% and heavyweight chipmaker ASML trading 1.8% higher.
Attention is also turning to Anthropic's IPO pricing later today, with the company targeting a valuation of $1.4 trillion.
However, mining stocks are the biggest laggard, down around 3% and near a nine-month low as copper prices continue to fall.
The FTSE, which has little exposure to tech stocks but has heavyweight miners, is underperforming its European peers.
Copper prices have fallen to their lowest level since July, as recent weakness in tech stocks has raised concerns about AI-related investment weighing on risk appetite. AI stocks have fallen sharply in recent weeks, raising concerns about the demand outlook for copper, given the metal's growing exposure to the trade through power grids and data centres.
However, the downside could be limited by signs of tight supply.
Miners such as Anglo American are trading 3% lower, while Antofagasta is also down. Glencore is down 2.95%, while Fresnillo is also over 2.5% lower.
Energy stocks are also under pressure, tracking oil prices lower.
On the data front, UK inflation rose to 3.6% year on year, up from 3.5% in September, marking its highest level in a year but also coming in below the 3.7% forecast. However, the market has reined in Bank of England rate hike expectations for next month as some underlying components held steady.
Core inflation, which removes more volatile items such as food and fuel, together with services price inflation, which the Bank of England watches closely, actually held steady, defying expectations of a rise.
Even so, the Bank of England sees inflation approaching 5% by Q2 2027, owing to higher energy prices. This means further rate hikes from the Bank of England remain a possibility. The market is pricing in an 80% chance of a hike in December, down from 90%.
FTSE forecast – technical analysis
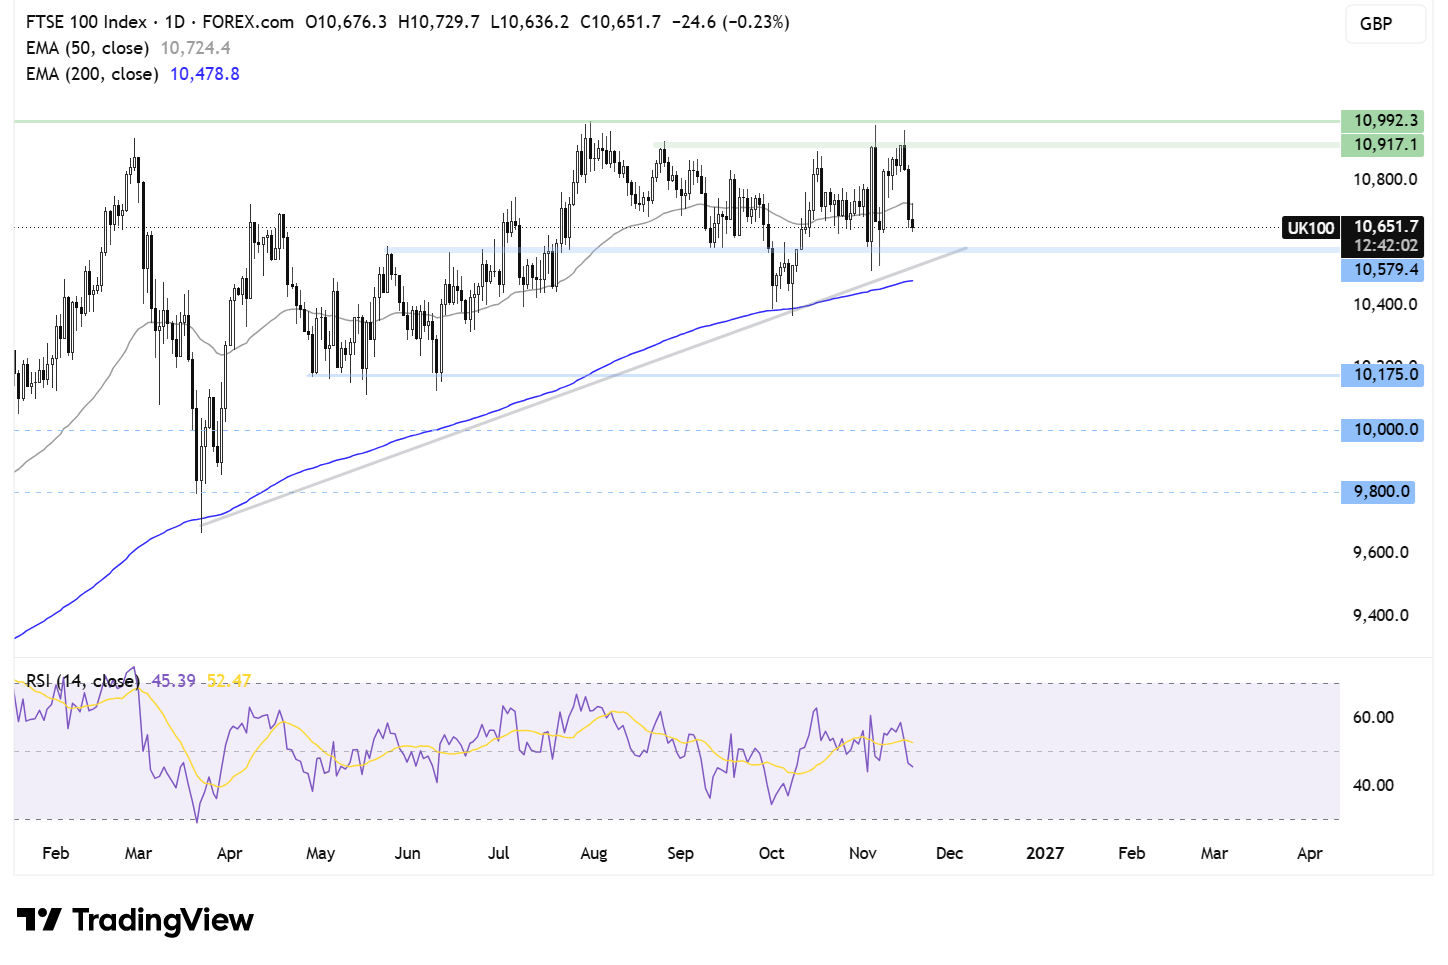
After running into resistance just below 11,000, the FTSE has rebounded lower, breaking below its 50 EMA. However, it still remains above its 200 EMA and rising trend line, keeping the longer-term outlook bullish for now.
Sellers would need to take out support at 10,575, as well as the horizontal support, rising trend line and the 200 EMA around the 10,500 level, for the outlook to turn more bearish.
On the upside, a rise above the 50 EMA at 10,730 is needed for attention to turn back to 10,900 horizontal resistance and 11,000 for fresh record highs.\
Oil breaks below key support as stockpiles rise, supply surplus weighs
Oil prices are falling on Wednesday after data showed an increase in U.S. crude and fuel stockpiles, overshadowing ongoing attacks between the U.S. and Iran.
Prices are falling sharply today after U.S. crude stock data showed that U.S. crude stockpiles rose by 5.28 million barrels in the week ending November 13. Gasoline inventories also jumped by 5.12 million barrels, while distillates rose by 351,000 barrels. These builds point to softer near-term demand.
The EIA's official figures are due later today and could confirm the builds seen in the API report.
These reports come after forecasts from Goldman Sachs of a surplus of 200 million barrels in 2027. JPMorgan also believes the oil market has returned to surplus, with estimates of 1.1 million barrels per day in September and 1.4 million barrels per day in October. Furthermore, the IEA expects the market to return to balance by the end of this year, as the growth in exports is outpacing the recovery in demand.
Without an escalation of the conflict in the Middle East, the surplus could grow to 3.8 million barrels per day by the end of 2027.
Adding to the picture is weak demand in China. According to Reuters, refineries in China processed 490,000 barrels per day less in October than they could have, given imports and domestic production.
However, losses may be limited by the ongoing conflict in the Middle East.
Both Brent and WTI settled higher on Tuesday after the U.S. and Iran traded strikes and the conflict intensified. Bahrain's defence force said today that it had intercepted Iranian aerial attacks. Talks between Iran and mediators Oman and Qatar continue.
Ongoing attacks on ships transiting the Strait of Hormuz keep supply concerns alive and could limit the downside in oil prices. Under current conditions, and taking into account the latest vessel data, the normalisation of flows through the Strait of Hormuz is not happening for now.
Furthermore, Yemen's Houthis have also launched drone attacks on pumping stations along Saudi Arabia's East-West Pipeline, targeting infrastructure that has been key to rerouting oil and bypassing the Strait of Hormuz.
Oil forecast – technical analysis
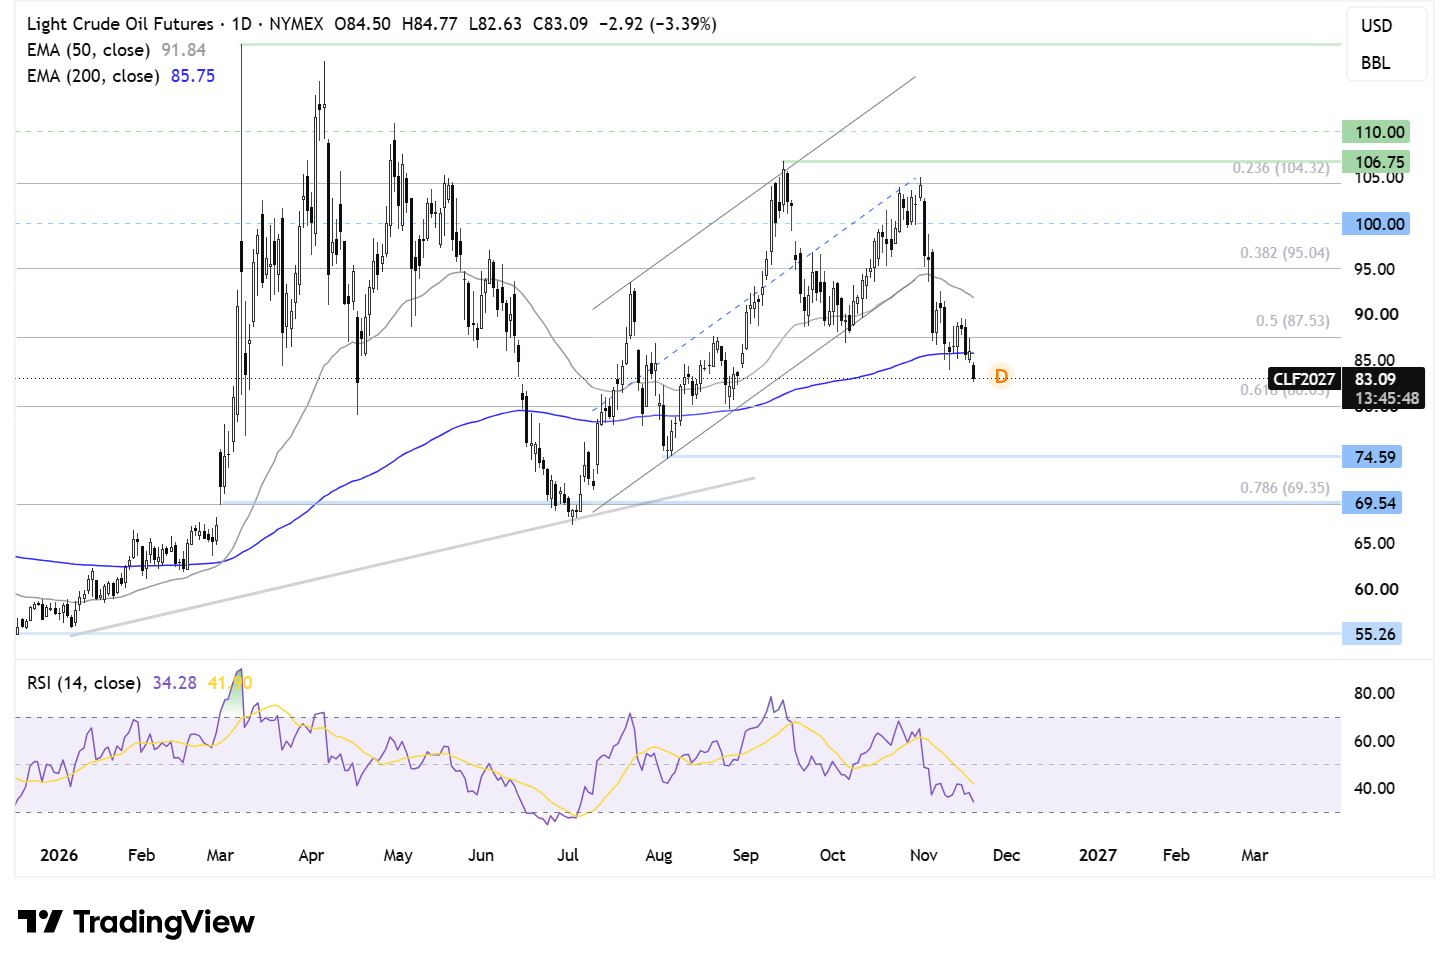
Oil ran into resistance at $105 and rebounded lower, breaking below the rising channel, the 50 EMA and the 200 EMA, to trade at $83 at the time of writing. The break below these key levels, combined with the RSI below 50, keeps sellers hopeful of further downside.
Attention will now turn to $80, the 61.8% Fibonacci retracement of the move from the $55 low to the $120 high. Should sellers take out this level, attention will turn to $75, the August low, ahead of $70, the round number.
Any recovery would first need to retake the 200 EMA at $86 and the 50% Fibonacci level at $88. A rise above here turns attention to $92, the 50 EMA, and $95, the 38.2% Fibonacci retracement. Above here, the price would be on much firmer footing.
Comments
Log in or sign up to join the conversation.