
Here are some things I think I am thinking about this weekend: valuations, TIPS and the narratives that just got ruined….
1) Valuations Matter, but Not the Way Wall Street Says
I published a new research piece this week discussing valuations and the proper way to contextualize them. This is something I’ve been working on for a year as the Defined Duration methodology has really altered my way of thinking about things across a temporal spectrum. The typical way of thinking about valuations is that they can be used to predict future potential returns. The problem with most of the data is that it’s not very old and so the independent periods in the data are usually limited to something like 3 to 4 rolling 20 or 30 year periods. And the period in those 3 or 4 that skews all the data is the Nasdaq Bubble. So the tendency in the last 20 years has been to look at current valuations and claim that we have to have low returns in the future. You know the narrative by now. After running the numbers this is not the conclusion I come to though.
When I look at valuations I don’t assign a short-term expected return because valuations don’t inform us about the short-term. Instead, I assign a potential long-term expected return. For instance, if valuations are very high in US tech then the right interpretation isn’t to say they are going to generate low or negative future returns in the near-term. The market is valuing the shares high because expectations are high. That means the margin for error is lower. Therefore, the potential for those high expected returns to materialize over a very long time horizon is a rational expectation. But what the high valuation is informing us of is that the potential dispersion of that return is likely to be wider over time. This is important because it doesn’t mean you should be necessarily bearish about tech just because valuations are high. It means you need to assign a different time horizon to shares with higher valuations. You don’t sell them or turn bearish on the shares just because valuations are high. You simply assign them a different asset match entirely. For instance, in my personal accounts technology is a retirement holding and a multi-generational holding. As you can probably tell from my writings here I am extremely optimistic about AI and robotics. But I don’t expect those things to materialize into higher return assets in the near-term. They’re a very long duration asset match for me. I actually assign a long time horizon to them specifically because the probability of poor sequence risk is higher in these instruments.
In my opinion this is an important way to compartmentalize and assess your equity allocation because it allows you to accept what seems like two competing views. Instead of assuming high valuations must lead to lower expected returns you can accept that higher valuations are due to higher expected returns while also acknowledging that higher expectations means higher potential sequence risk. You don’t change your allocation because of this and you certainly don’t sell all your tech because of this. You simply accept that a technology stock isn’t going to fund a 15 year liability with the same probability that a consumer staple stock will.
Anyhow, go have a read and let me know what you think.
2) Is Shifting to TIPS Tactical Asset Allocation?
Another financial advisor sent me an interesting question. I’ll summarize it like this:
“Cullen, with TIPS yields near their highest levels since 2008, doesn’t it make sense to add longer-term TIPS now? It feels like a no-brainer, but it also feels like an active, tactical shift in my client portfolios and that makes me uncomfortable. What do you think?”
The answer depends on what you’re doing. Are you making the change because you’re trying to beat the market? Or are you matching an asset to a liability?
If it’s the first, you’re making an inflation bet. And it’s not really a bet on whether inflation goes up or down. It’s a bet on whether inflation comes in above or below what the market has already priced in. Say you buy a 5 year TIPS at a 2.7% real yield. If inflation averages 2.5% over the next five years you’ll earn about 5.3% per year. If it averages 3.5% you’ll earn about 6.3%. Whether that beats a 5 year nominal Treasury depends on the breakeven inflation rate the day you bought it. If inflation comes in below that breakeven, you’ll wish you owned the nominal bond. That’s a tactical call based on an implicit forecast, whether you call it that or not.
But what if you’re using an ALM approach? Then the choice between a nominal bond and a TIPS isn’t tactical at all. It’s a planning decision, and it comes down to one question. Is the liability nominal or real?
If you owe a fixed dollar amount in seven years, the nominal Treasury is your match and the TIPS is the bet. If you need to fund seven years of living expenses that rise with the cost of living, the TIPS is your match and the nominal bond is the bet. In that case it doesn’t matter whether inflation goes up or down, because the benchmark isn’t relative performance. The benchmark is whether the money is there when you need it. A TIPS held to maturity comes about as close to guaranteeing that as anything in finance.
A few caveats matter here. You need to hold the bond to maturity, which means an individual TIPS or a defined maturity ladder, not a constant maturity fund. The maturity should line up with the liability. Buying a 20 year TIPS to fund something seven years out is still a duration bet, no matter how attractive the yield is. And the protection is against CPI, before taxes, so in a taxable account the phantom income on the inflation adjustments will chip away at it.
So, is buying longer-term TIPS today a tactical allocation change? If you’re doing it because yields look high, you’re making a market call. That’s fine, just be honest about it. If you’re doing it because you have long-dated liabilities that rise with inflation, you’re not making a call at all. You’re just matching assets to liabilities, and higher real yields mean it costs less to fund those future needs today.
This is just one more reason why I think ALM strategies will come to dominate total return strategies in financial planning practices over the coming decades. A well structured ALM strategy doesn’t worry about changing the assets for the sake of optimizing the assets because it’s the quantification of the liabilities that dictates the asset in the first place.
3) That Survey of Consumer Finances is Gonna Ruin a Whole Lotta Narratives….
The Fed released the 2025 Survey of Consumer Finances (SCF). The SCF is a huge survey that summarizes the status of American households. It is one of the most data rich surveys they produce and it only comes out once every three years. And this one is going to blow up a lot of narratives because it shows just how insanely rich Americans are. For instance, median real household wealth has exploded 91% since 2013. So, even though inequality has broadened Capitalism has lifted all the boats. That is, after all what Capitalism does well. It lifts all the boats, but does so even though some of the boats get much nicer than others across time. This is a gigantic hole in the narrative that only the rich are getting richer.
The other big narrative that this report blew up is the one that says young people are doing worse than their parents and grandparents were at the same stage in life. In fact, the SCF shows that younger generations are ahead of their parents or doing just as well. Ernie Tedeschi, former White House Chief Economist, has the key data in the chart attached.
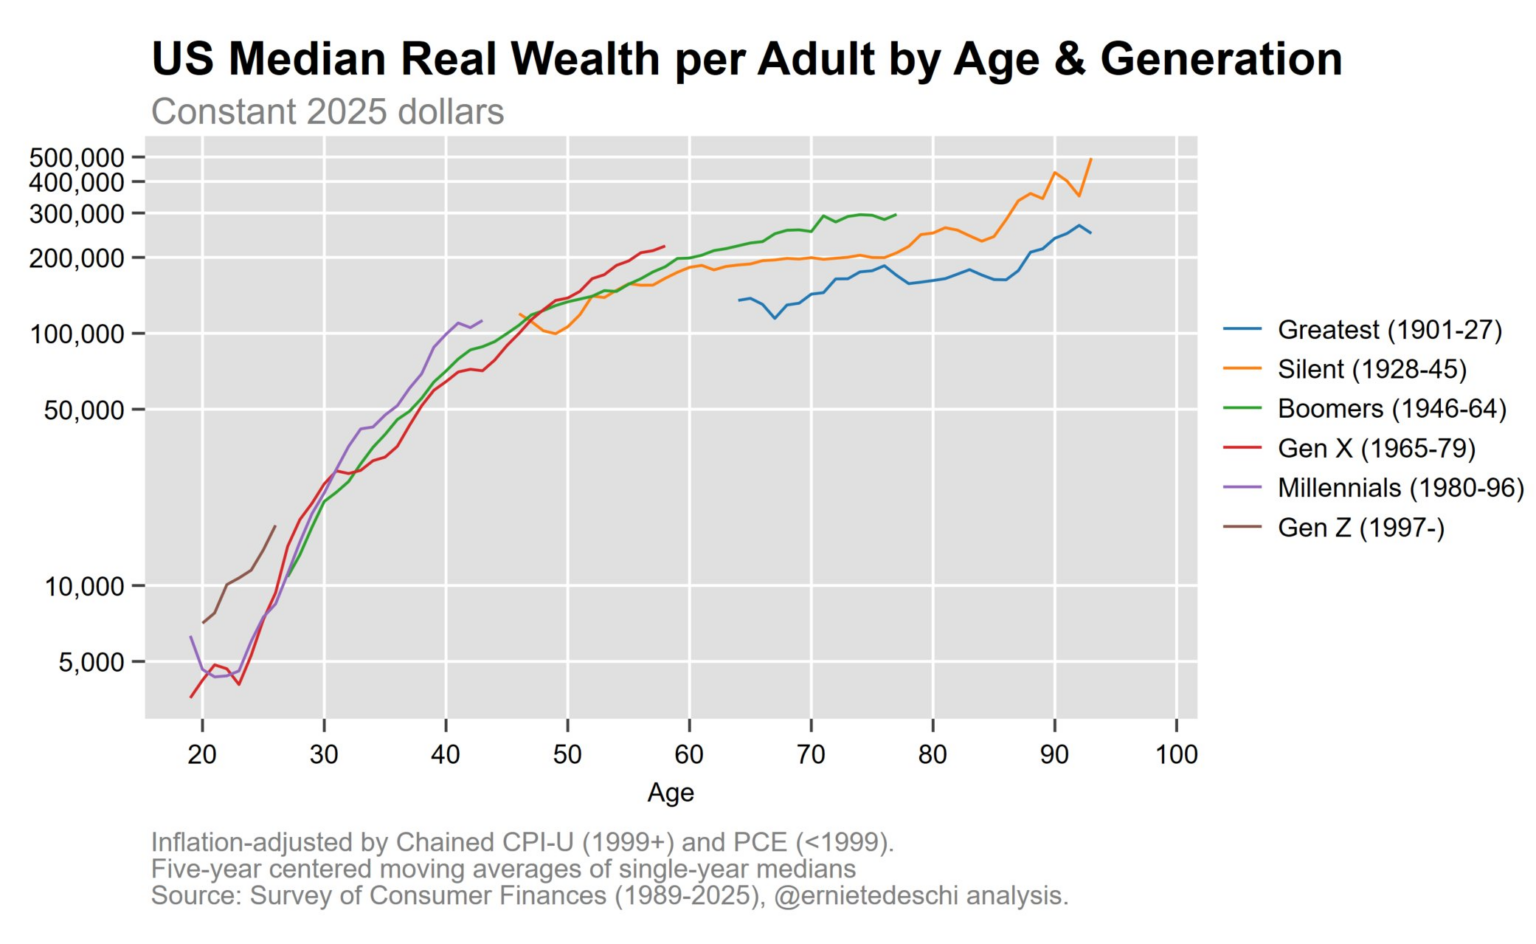
Of course, there are other real concerns as well. Debt servicing has become a bigger problem and asset appreciation is carrying more and more of the load here so you can that things have improved a lot and that the system has become a bit more fragile in various ways. I would also add that things like housing affordability are huge problems that the younger generation is, and should be, very pissed about. So it’s not all sunshine and roses. But things are much better than some of the doomer narratives out there want us all to believe.
Alright, that’s all I’ve got for you this week. I hope you have a great weekend. And as always, stay disciplined out there.
Comments
Log in or sign up to join the conversation.