
London's FTSE 100 hovered in positive territory past midday on Tuesday, as strong corporate earnings updates and selective buying across retail and industrial engineering helped offset wider Middle East geopolitical anxieties and a deteriorating domestic fiscal backdrop. Investors maintained a cautious stance as global markets looked ahead to U.S. President Donald Trump's scheduled speech at the UN General Assembly.
Retail and industrial engineering heavyweights led the top-flight gainers. Home improvement giant Kingfisher soared nearly 10% after delivering a 9.9% surge in first-half adjusted pre-tax profit to £404 million, supported by gains in Screwfix's market share, trade demand, and gross margin expansion. The B&Q owner subsequently upgraded its full-year profit guidance range to £595 million–£635 million. Industrial engineering company Smiths Group surged 6.5% after posting resilient full-year results featuring 1.2% organic revenue growth, 20 basis points of operating margin expansion to 20.6%, and a 5.4% dividend hike. Broad-based momentum across discretionary, consumer, and financial names saw JD Sports Fashion, Coca-Cola HBC (CCH), St. James's Place, Antofagasta, Anglo American Plc, IAG, Informa, and Howden Joinery Group gain between 2.3% and 4.0%. Further buying interest buoyed Diploma, Metlen Energy & Metals, Games Workshop, Spirax Group, Weir Group, Marks & Spencer, Compass Group, Aberdeen Group, Bunzl, Intercontinental Hotels Group (IHG), IMI, Diageo, ICG, Polar Capital Technology Trust, Reckitt Benckiser, AutoTrader Group, and Unilever.
Conversely, defensive, property, and selected energy counters slipped into the red. BT Group, BP, Airtel Africa, Admiral Group, Land Securities Group, British Land, BAE Systems (BA), Ithaca Energy, Hiscox, and Aviva (AV) fell between 1.0% and 2.5%, dragging on wider index momentum.
On the domestic macro front, official data from the Office for National Statistics (ONS) and Office for Budget Responsibility (OBR) highlighted growing pressure on public finances ahead of October's Budget. Public sector net borrowing (PSNB) reached £18.3 billion in August, pushing cumulative fiscal year-to-date borrowing to £77.3 billion—standing £8.1 billion above the trajectory envisaged by the OBR's Spring Forecast. While tax receipts remained resilient on first-half economic activity, higher expenditure across benefits and debt interest costs driven by elevated Gilt yields drove the overshoot. The current budget deficit stood £4.8 billion over forecast at £51.9 billion, while the central government net cash requirement overshot by a narrower £2.9 billion.
Finish Line: U.K. equities pushed higher as beat-and-raise earnings from Kingfisher and margin resilience at Smiths Group provided powerful stock-specific tailwinds. While an £8.1 billion fiscal borrowing overshoot highlights tough trade-offs ahead for the October Budget, strength across retail, mining, and industrials helped the FTSE 100 maintain its positive posture ahead of global diplomatic signals.
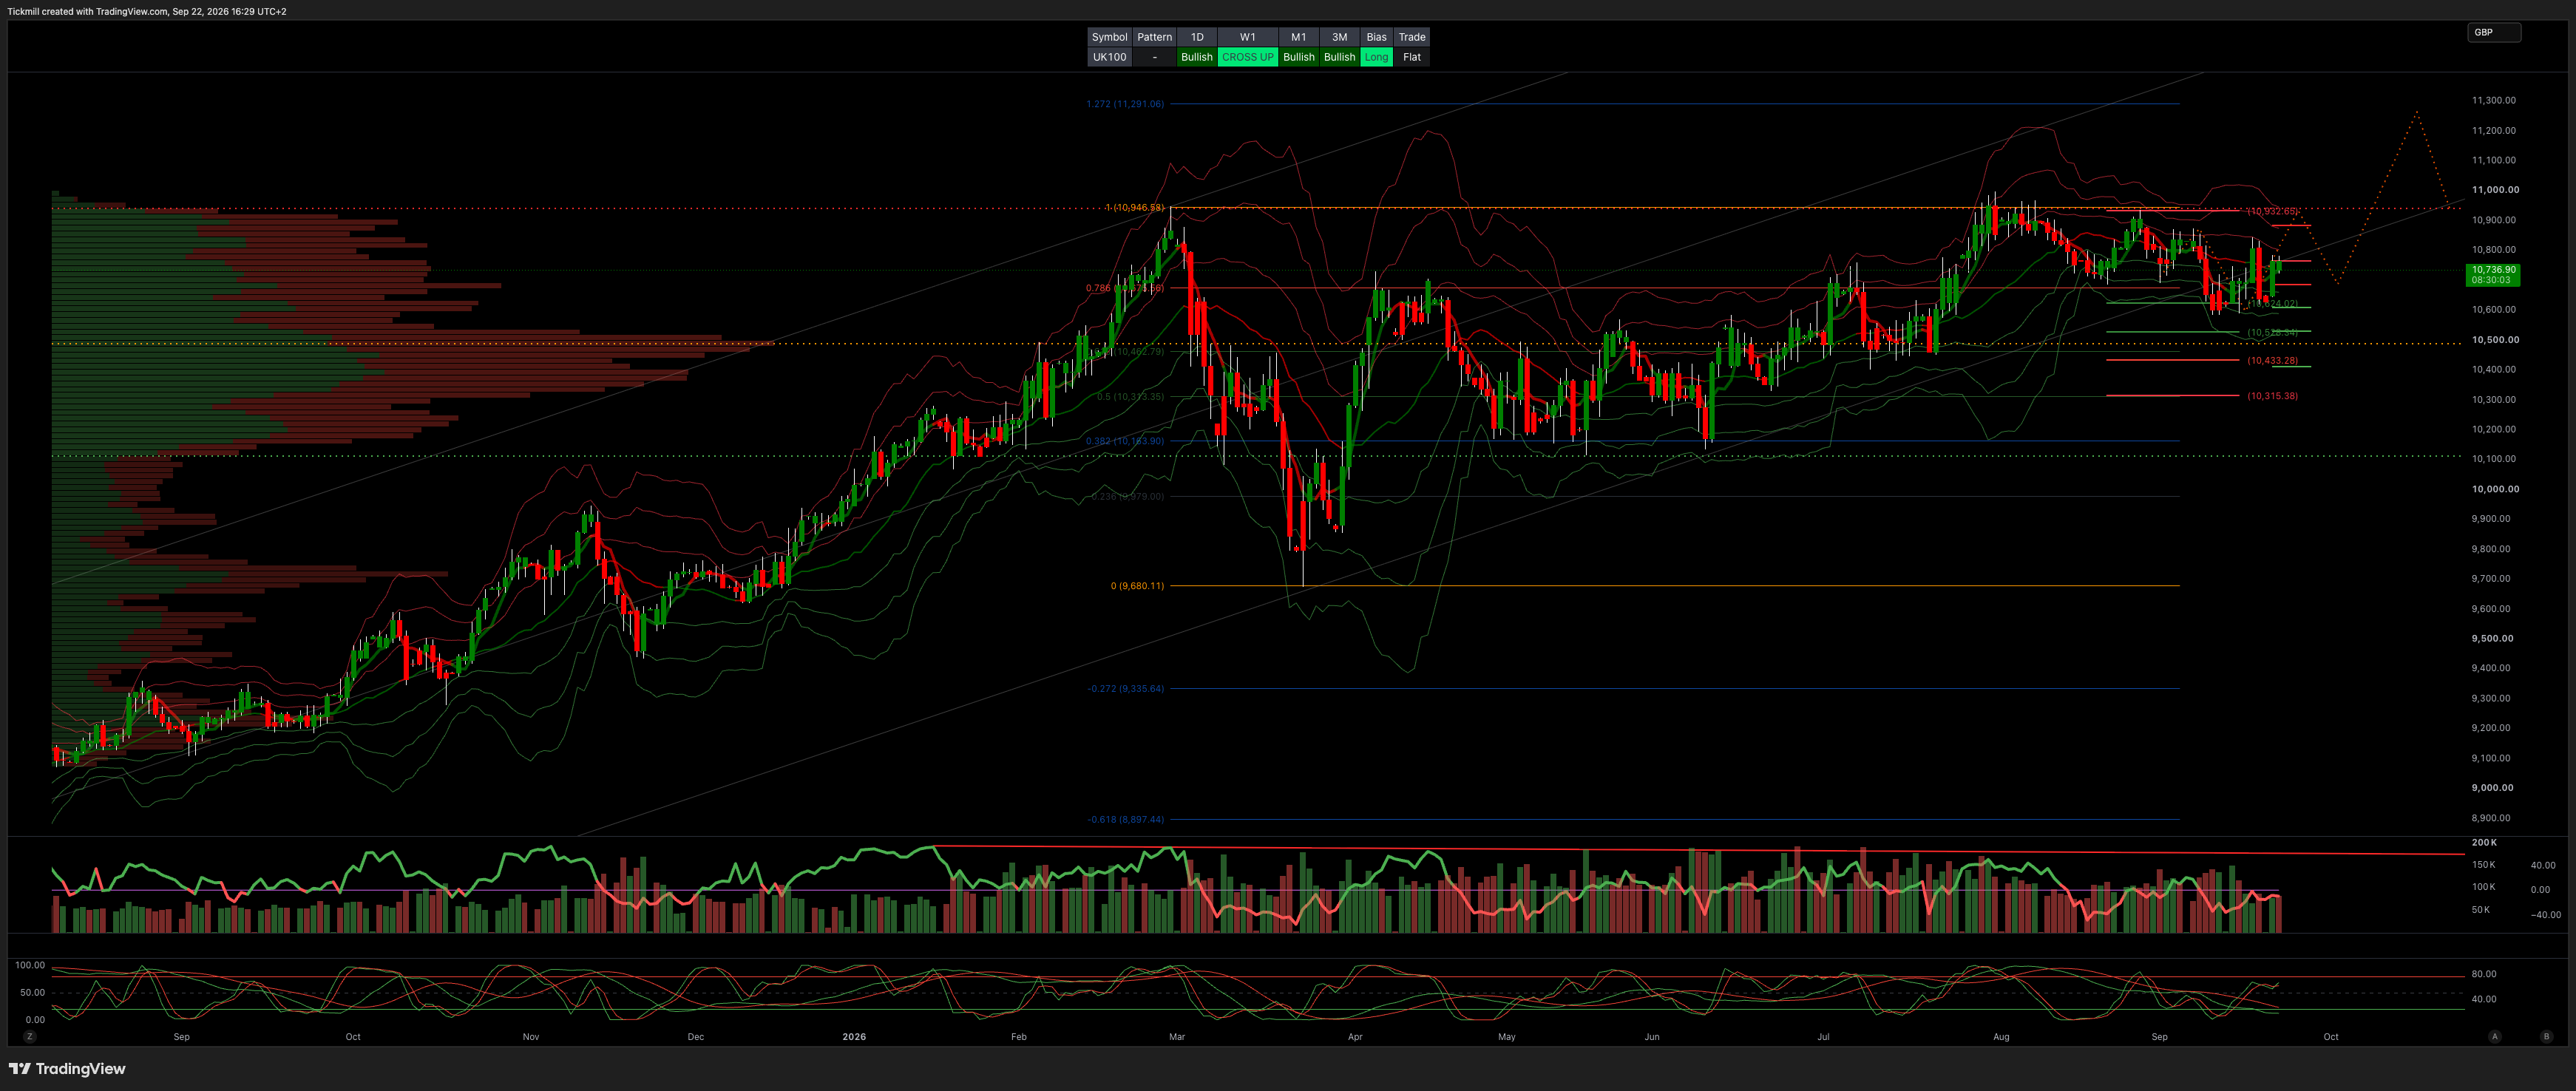
TECHNICAL & TRADE VIEW
Comments
Log in or sign up to join the conversation.