
We don’t have to go decades back to find an analogy. Just look back a few years, to the pandemic. We all lived through it, most of us in sweatpants. And it offers a near-perfect preview of what is about to happen in AI.
A note before we start: this piece began as part of the Fall Letter I sent to IMA clients last week. The rest of that letter dealt with our individual holdings, which is not something I write about publicly. But the section on AI stocks and the pandemic kept growing as I wrote it, and I think it deserves a wider audience. I have lightly edited it for readers who are not clients. Everything else is as I wrote it.
The AI Hangover Is Coming. The Pandemic Already Showed Us How It Ends.
Financial pundits looking for an analogy for what is about to happen to AI stocks reach back decades, to the 1999 dot-com bubble or the 2008 financial crisis. I have done it myself in past letters. Both offer lessons, but both are fading. Anyone under 40 was a kid in 1999, and 2008 is nearly two decades in the rearview mirror. The further we get from a crash, the harder it is to relate to it.
We don’t have to go decades back to find an analogy. Just look back a few years, to the pandemic. We all lived through it, most of us in sweatpants. And it offers a near-perfect preview of what is about to happen in AI.
The pandemic changed supply and demand for many goods and services. Supply chain constraints limited supply, lockdowns skewed spending patterns, and a temporary injection of government cash changed demand. As an analyst, it was fascinating to watch how these forces impacted businesses. Many pandemic darlings woke up with a hangover they are still nursing today.
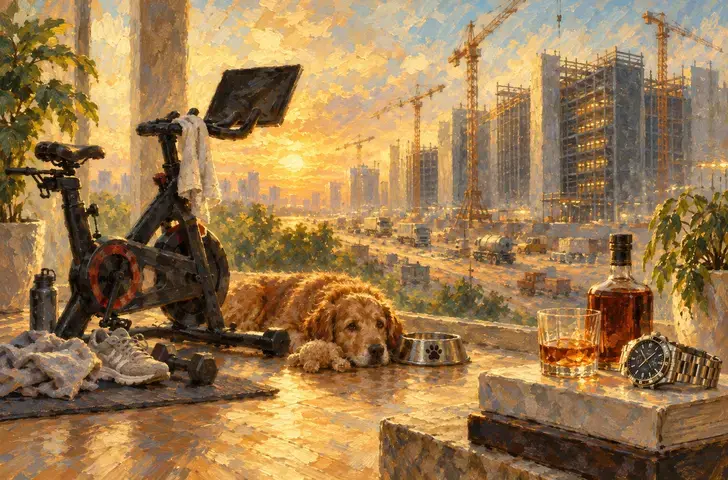
If I had to sum up the pandemic hangover in one company, the one almost every reader can relate to, it would be Peloton (PTON). A locked-down population decided, all at once, that it wanted to get in shape, and it couldn’t leave the house. Peloton was the best alternative, and demand for its bikes surged severalfold. The company could not keep up. At one point it spent $100 million just on air freight to get bikes to customers faster. So, it bought a fitness equipment manufacturer, Precor, for $420 million, and committed $400 million to build its own factory in Ohio. All of this raised its operating costs substantially. And then… the economy opened up.
People canceled their memberships, and demand dried up. The company found that its costs were much higher, while the temporary spike in demand had stolen its future sales. Everyone who was ever going to buy a $2,000 bike had already bought one. The factory was never finished; it was written off. At the height of demand, management made many suboptimal decisions to satisfy customers. Today the customers are gone, but the decisions, including the debt, remain. The stock fell from $160 to single digits.
Peloton is the extreme case, but milder versions played out everywhere.
Spirits: locked-up folks, given a choice between water and booze, chose booze. Alcohol sales went through the roof, the industry increased capacity and raised prices. Demand normalized but capacity stayed.
Watches: Swiss watchmakers raised prices too much during the boom, and the same applies to many other luxury goods. The problem with luxury goods is that you can only raise prices, you cannot lower them; discounting kills the perception of what you sell.
Pets: people felt lonely, and you had a mini boom in pets. Companies like Zoetis (ZTS), the largest maker of pet medicine and vaccines, went to the moon. Then pet spending normalized, and Zoetis crashed back to earth.
Comments
Log in or sign up to join the conversation.