
The good news is:
The market is oversold and due for a bounce.
The Negatives
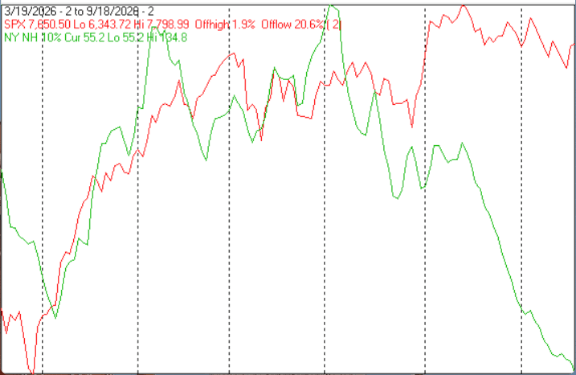
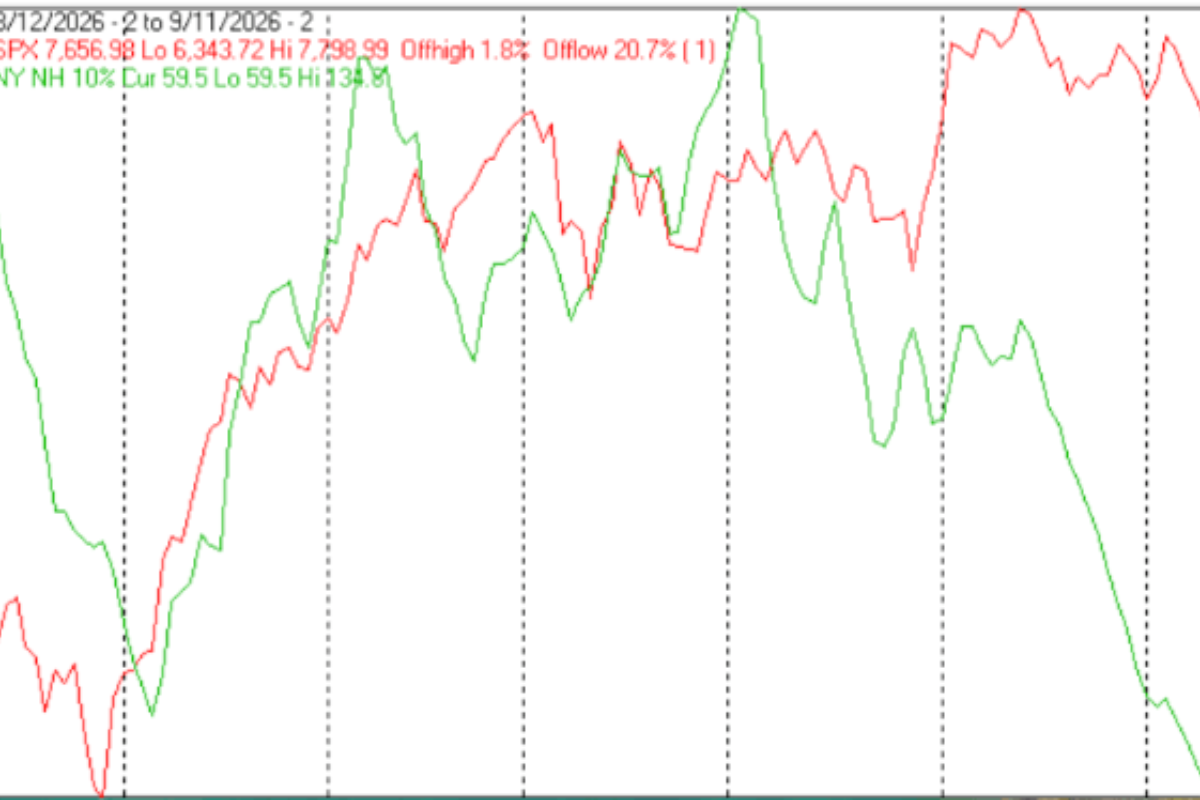
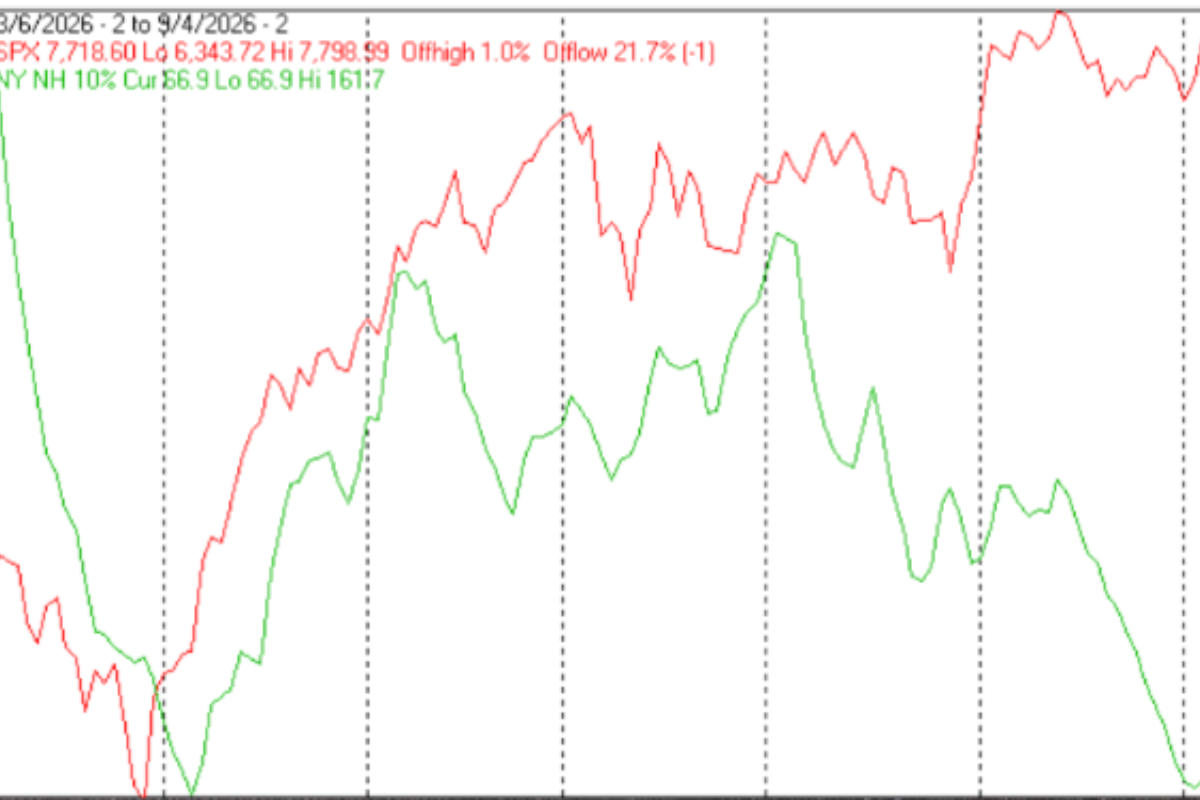
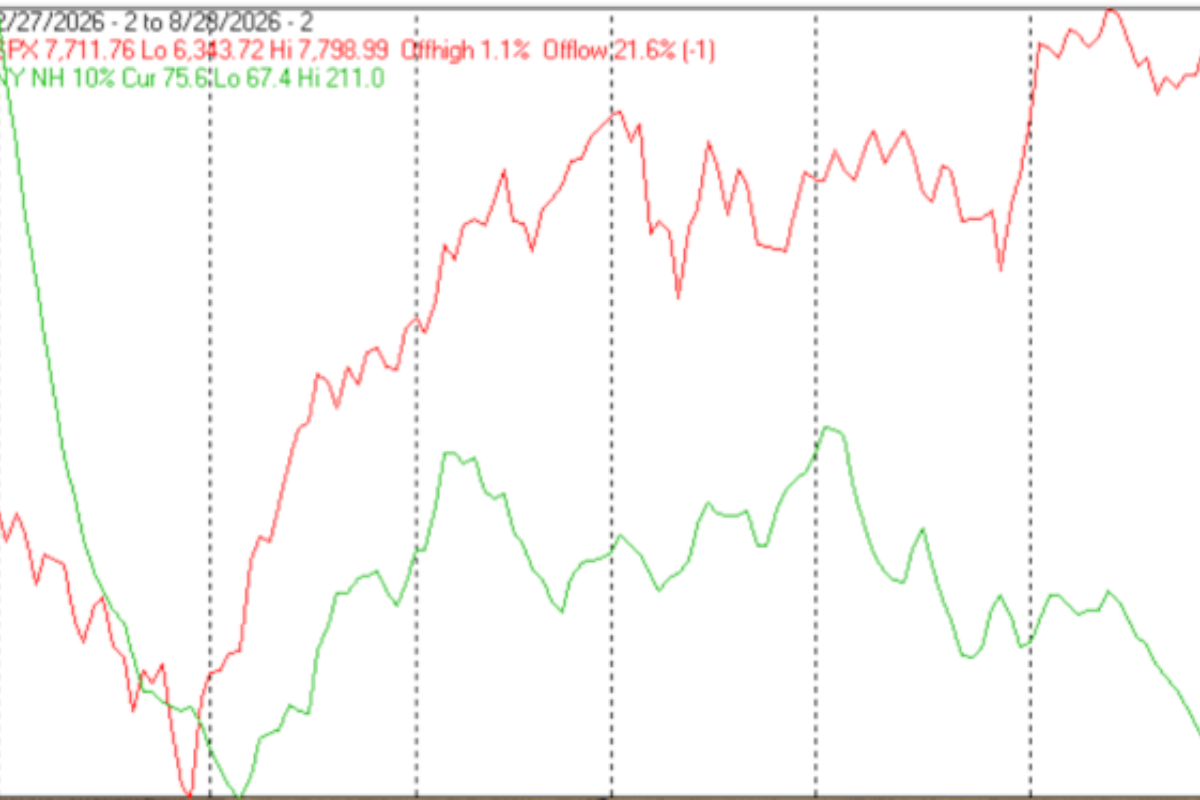
The first chart covers the past 6 months showing the S&P 500 (SPX) in red and a 10% trend (19 day EMA) of NYSE new highs (NY NH) in green. Dashed vertical lines have been drawn on the 1st trading day of each month. Declining new highs imply narrowing leadership.
NY NH looks the same as last week at its lowest level of the year.
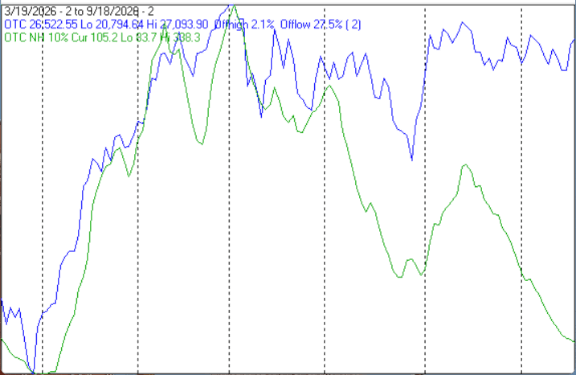
The next chart is similar to the first one except it shows the Nasdaq composite (OTC) in blue and OTC NH in green has been calculated with Nasdaq data.
OTC NH ditto except note quite its low for the year.
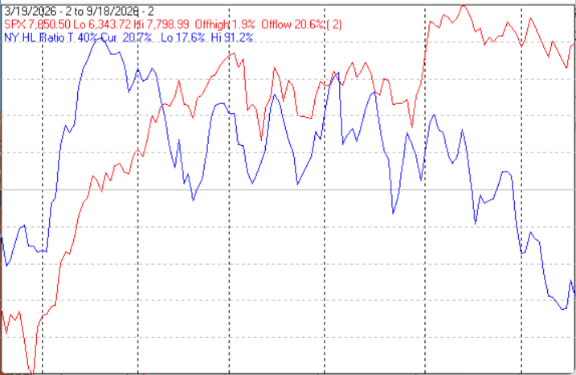
The next chart covers the past 6 months showing the SPX in red and a 40% trend (4 day EMA) of NYSE new highs divided by new highs + new lows (NY HL Ratio), in blue. Dashed horizontal lines have been drawn, on the Y axis at 10% levels for the indicator; the line is solid at the 50%, neutral level (equal numbers of new highs and new lows).
NY HL Ratio also finished the week slightly above its lowest level of the year.
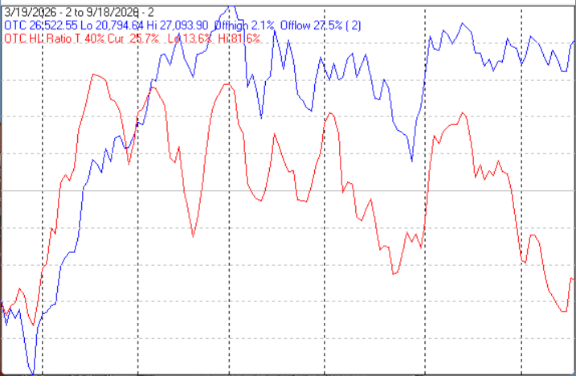
The next chart is similar to the one above except it was calculated with Nasdaq data and the OTC is shown in blue while OTC HL Ratio is shown in red.
OTC HL Ratio also recovered a little at the end of the week..
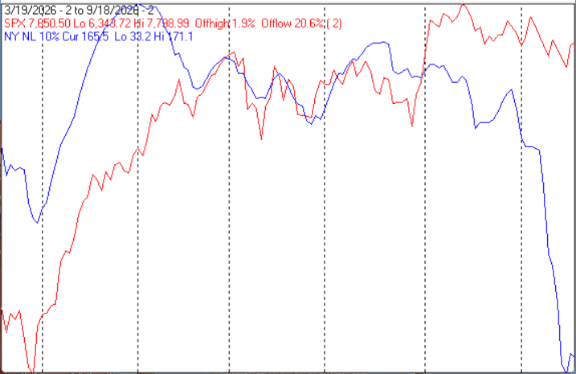
The next chart covers the past 6 months showing the SPX in red and a 10% trend (19 day EMA) of NYSE new lows (NY NL) in blue. NY NL has been plotted on an inverted Y axis so decreasing numbers of new lows move the indicator upward (up is good).
NY NL moved upward from its lowest level of the year at the end of the week.
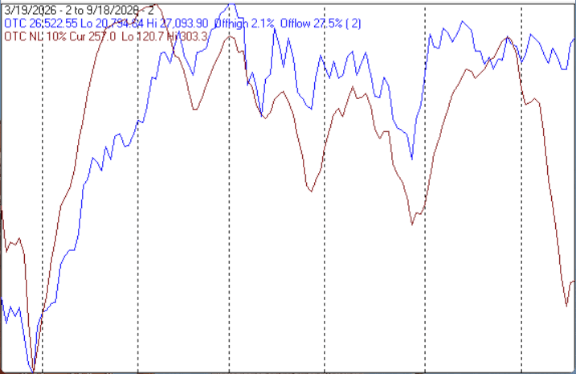
The next chart is similar to the chart above except it shows the OTC in blue and OTC NL, in brown, has been calculated with Nasdaq data.
OTC NL continued its decline but finished the week with a modest move upward.
The Positives
The market is due for a bounce, which may have begun late last week..
Seasonality
Next week includes the 5 trading prior to the 4th Friday of September during the 2nd year of the Presidential Cycle. The tables below show the daily change, on a percentage basis, for that period.
OTC data covers the period from 1963 to 2025 while SPX data runs from 1953 to 2025. There are summaries for both the 2nd year of the Presidential Cycle and all years combined. Prior to 1953 the market traded 6 days a week; so that data has been ignored.
Seasonality for the coming week has been negative by all measures..
Report for the week before the 4th Friday of September.
The number following the year is the position in the Presidential Cycle.
Daily returns from Monday through the 4th Friday.
OTC Presidential Year 2 (PY2)
Year Mon Tue Wed Thur Fri Totals
1966-2 0.34% -0.15% 0.13% -1.18% 0.54% -0.31%
Avg 0.34% -0.15% 0.13% -1.18% 0.54% -0.31%
1970-2 -0.01% -0.71% -0.14% 1.10% 2.26% 2.50%
1974-2 -0.40% -1.36% -0.15% -1.51% -1.30% -4.72%
1978-2 -1.24% -1.17% -1.04% -0.42% 0.15% -3.73%
1982-2 -0.33% 1.03% 0.38% -0.25% 0.24% 1.07%
1986-2 0.89% 0.23% 0.33% -0.85% 0.03% 0.63%
Avg -0.22% -0.40% -0.13% -0.39% 0.28% -0.85%
1990-2 -2.79% 0.74% -1.34% -2.53% 0.97% -4.93%
1994-2 -0.15% -1.28% -0.79% -0.04% -0.39% -2.65%
1998-2 1.00% 1.04 - 3.68% -2.27% 1.35% 4.80%
2002-2 -2.96% -0.23% 3.39% -0.06% -1.84% -1.69%
2006-2 0.01% -0.60% 1.37% -0.67% -0.84% -0.73%
Avg -0.98% -0.07% 1.26% -1.11% -0.15% -1.04%
2010-2 1.74% -0.28% -0.63% -0.32% 2.33% 2.84%
2014-2 -1.14% -0.42% 1.03% -1.94% 1.02% -1.45%
2018-2 0.08% 0.18% -0.21% 0.65% 0.05% 0.74%
2022-2 0.76% -0.95% -1.79% -1.37% -1.80% -5.15%
OTC summary for PY2 1966 - 2022
Avg -0.28% -0.26% 0.28% -0.78% 0.19% -0.85%
Win% 47% 33% 47% 13% 67% 40%
OTC summary for all years 1963 - 2025
Avg -0.25% -0.09% -0.03% -0.33% -0.13% -0.82%
Win% 43% 51% 52% 39% 46% 43%
SPX PY2
Year Mon Tue Wed Thur Fri Totals
1954-2 -0.44% 0.70% 0.66% 0.56% 0.68% 2.16%
1958-2 -0.40% 0.73% 0.44% -0.42% 0.18% 0.53%
1962-2 -1.84% 0.58% -1.42% -0.68% 0.90% -2.46%
1966-2 -0.50% -0.69% -1.68% 0.30% -0.35% -2.92%
1970-2 -0.86% -0.31% 1.43% 1.30% 0.07% 1.64%
1974-2 -1.03% -2.02% -0.66% -1.64% -2.29% -7.63%
1978-2 -0.87% -0.66% -0.78% 0.17% -0.06% -2.20%
1982-2 -0.03% 1.93% -0.71% -0.15% -0.40% 0.65%
Avg -0.66% -0.35% -0.48% 0.00% -0.60% -2.09%
1986-2 1.17% 0.31% 0.26% -1.88% 0.17% 0.03%
1990-2 -2.16% 1.20% -1.04% -1.34% 1.69% -1.65%
1994-2 -0.07% -1.59% -0.41% -0.04% -0.35% -2.46%
1998-2 0.37% 0.58% 3.52% -2.19% 0.19% 2.47%
2002-2 -1.38% -1.73% 2.49% 1.82% -3.23% -2.03%
Avg -0.41% -0.24% 0.96% -0.73% -0.30% -0.73%
2006-2 0.10% -0.22% 0.52% -0.54% -0.25% -0.38%
2010-2 1.52% -0.26% -0.48% -0.83% 2.12% 2.07%
2014-2 -0.80% -0.58% 0.78% -1.62% 0.86% -1.36%
2018-2 -0.35% -0.13% -0.33% 0.28% 0.00% -0.54%
2022-2 0.69% -1.13% -1.71% -0.84% -1.72% -4.72%
Avg 0.23% -0.46% -0.24% -0.71% 0.20% -0.98%
SPX summary for PY2 1954 - 2022
Avg -0.38% -0.18% 0.05% -0.43% -0.10% -1.04%
Win% 28% 39% 44% 33% 50% 39%
SPX summary for all years 1953 - 2025
Avg -0.39% -0.06% -0.10% -0.21% -0.13% -0.88%
Win% 34% 44% 49% 40% 41% 35%
Conclusion
The seasonal bounce I expected last week got off to a late start - or perhaps that was all were going to get.
The strongest sectors last week were Electronics (for the 2nd week) and Precious Metals (up from the bottom last week) while the weakest were Leisure and Utilities.
I expect the major averages to be higher on Friday September 25 than they were on Friday September 18.
Last week the OTC was up while the other major indices were down, so I am calling last week’s positive forecast a tie.
Comments
Log in or sign up to join the conversation.