
Tech is rebounding from Thursday’s collapse as well-received earnings reports, cheapening valuations and lower interest rates are motivating investors to seize the turbulent opportunity and raise exposures. A better-than-expected manufacturing PMI release, which hit the strongest level in 53 months, strengthened confidence that the rapid AI buildout is continuing as capital expenditures and factory output levels were robust. The beat, paired with a positive UMich revision, is helping to quell slowdown concerns, but the developments are raising yields, which are also being propelled by a five-week high in oil prices stemming from Washington and Tehran intensifying their threats toward each other. The Treasury losses, which are comparable to only about a third of yesterday’s significant gains against the backdrop of credit assets posting their best daily performance since 2025, are clocking cyclical stocks, the group that partially offset recent Nasdaq carnage. Indeed, we have a broad selloff today with the Dow Jones Industrial leading the retreat. It has fallen approximately 1% amidst 8 of the 11 principal sectors suffering declines. In fixed income, the curve is rising in bear-flattening fashion led by the monetary policy sensitive short end, as the 10-year tries to stay beneath the pivotal 5% number. Elsewhere, cryptocurrencies are recovering modestly, commodities excluding precious metals are appreciating, the greenback is stronger and volatility protection instruments are catching bids in light of hesitation on Wall Street.
Services Deceleration Offsets Improving Manufacturing
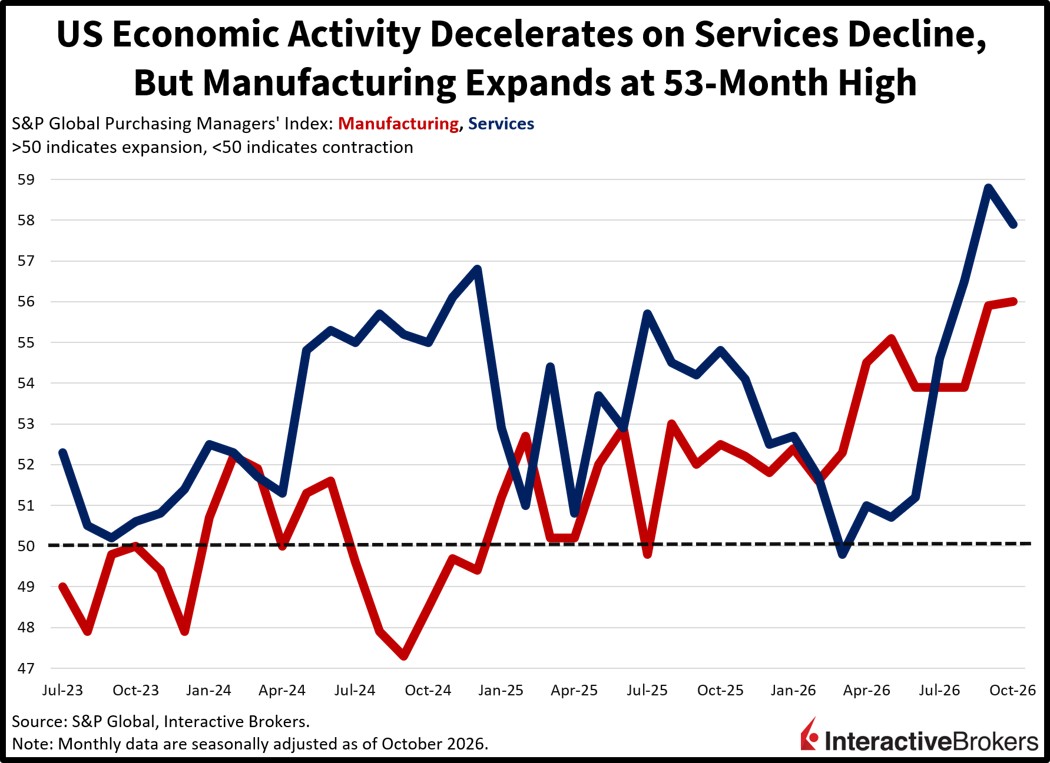
Economic growth remained buoyant this month, according to S&P Global, although a deceleration in services offset progress in manufacturing, which quickened its expansion to a 53-month high. The Flash Purchasing Managers’ Index (PMI) rose to 56 in the goods producing segment, beating the 55.5 median estimate and progressing from September’s 55.9. Production and orders reflected continued power; however, jobs, exports and delivery times increased significantly, indicating a need for more workers, international buyers engaging with sellers and heavy demand that extended the number of days it took to fulfill purchases. Prices were a significant headwind that caused business confidence to soften, albeit modestly, as improving customer engagement, wage bills, freight expenses and elevated fuel charges drove costs north. In services, the PMI decreased to 57.9, missing the expectation of 58 and arriving beneath the prior period’s 58.8, which was a 62-month high. Transactions slowed marginally and inflation hurt, but a still optimistic outlook was met with momentous hiring and rising foreign revenues.
Consumer Sentiment Revised Upward
The University of Michigan’s Consumer Sentiment Index for October was upgraded from 46.3 to 48. The subindices of current conditions and the future outlook were both revised to 46.7 and 48.8 from 44.7 and 47.3. Inflation expectations over one and five years were unchanged at 4.7% and 3.5%.
Risk Premiums Looking Better
Recent stock market turbulence is overlooking the fact that lower equity prices, combined with sliding interest rates and earnings beats have materially lifted the risk premium calculation for investors. AI expansion numbers have been in the nosebleeds, and everyone is correct to expect a deceleration at some point, which is poised to occur in 2027; however, those slowdown concerns have substantially reduced yields to the tune of 32 to 42 basis points when examining the 2- through 30-year Treasury maturities, and that is a reason to want to lift exposures here ahead of the strongest seasonal window on the calendar. Additionally, these developments make it increasingly difficult for the Fed to raise in light of financial stability risks and incrementally push the White House towards a deal with Iran in consideration of pain at the pump being a top theme in the upcoming midterm elections. Furthermore, a potential relief in price pressures becomes much more pronounced as we turn to 2027, and the annualized growth in energy costs won’t be as notable in overall inflation gauges, as high fuel will be compared to high fuel, rather than cheap fuel, starting this March, paving the way for the conversation to tilt from hikes to cuts.
International Roundup
Mexico Economic Activity Growth Slows Modestly
Economic growth in Mexico grew 3.3% year over year (y/y) in August and slowed from July’s 3.4% gain, according to the country’s statistical agency, INEGI. The print nevertheless surpassed the economist consensus estimate of 3.1%. The month-over-month (m/m) pace, however, accelerated from 0.5% in July to 0.6%.
A 6.1% drop in agriculture resulted in primary activities sinking 2.6% y/y. Categories with growth and the extent of the expansions were as follows:
Wholesale trade, 12.1%
Construction, 7.5%
Other services excluding government activity, 7.3%
Information services in mass media, 5%
Manufacturing, 3.2%
UK Economic Activity Accelerates
UK businesses ramped up activity this month with the S&P Global Flash Purchasing Managers Composite Index climbing from 52 to 53.1. In addition to moving farther above the contraction-expansion threshold of 50, the gauge blew past the economist consensus estimate of 51.8. Gains were strong across the economy with the flash manufacturing PMI strengthening from 51.9 to 52.8 and the services version of the gauge moving from 52.1 to 53.1. Economists anticipated that both metrics would sink to 51.8.
Within the composite survey, new work orders experienced the sharpest rise since September 2024. Growth came from both domestic and foreign customers and contributed to a return to employment growth after a two-year period of flat payrolls. Some firms said AI investment helped them boost sales and that demand for technology services grew. Other firms, however, said weak consumer confidence, the Middle East conflict and other geopolitical conflicts created sales headwinds.
Headwinds included input cost inflation accelerating to its worse pace since June with the adversity the most prevalent in manufacturing. Inflation was driven by higher energy, raw materials and transportation charges. Regarding sentiment, optimism for the coming 12 months climbed but still remained below the long-run average. A handful of firms noted that sluggish UK conditions and domestic political uncertainty had dampened their confidence.
But Activity Weakens in Europe
The S&P Global Flash Eurozone PMI Composite Index sank from 53.1 in September to a four-month low of 51.9 this month and fell short of the economist consensus estimate of 52.7. The separate manufacturing and services PMIs both underperformed, falling from 52.9 and 53 to 52.4 and 51.7, respectively. Economists anticipated that the manufacturing and services gauges would only fall to 52.7 and 52.6.
Output in France contracted after rising in September, which was the first improvement in 10 months. Other countries experienced slowing growth in business activity. Export orders, including intra-eurozone trade, climbed for the third consecutive month despite easing from September’s rate of expansion. Payrolls expanded but only marginally as hiring in the services sector was countered by broad declines in France over eurozone reductions by manufacturers. Despite the sluggish business environment, firms increased their purchases of input items at the fastest pace in four-and-a-half years. In doing so, they experienced ongoing supply chain disruptions and accelerated price hikes. Firms were limited in their ability to pass higher costs onto customers with output inflation slowing.
The decline in new orders and weakness in output growth resulted in business confidence slipping to its lowest level in five months. Pessimism was particularly strong in France, where political instability has recently intensified.
Singapore Inflation Cools Slightly
Singapore’s September Consumer Price Index was a tad cooler than expected and it eased slightly from August. The recent 2.2% y/y and 0.2% m/m prints were down from 2.3% and 0.6% in the preceding month. Economists anticipated a 2.4% annual climb. When excluding accommodation and private-transport costs, the resulting core CPI ascended 2% y/y following the 2.2% jump in August. It fell below the 2.3% economist consensus forecast.
Within the headline y/y result, the transport category inflicted the most pain on households, climbing 7.4% as higher energy costs from the Middle East crisis jacked up costs. Other categories and the extent of their gains were as follows:
Food, 2.4%
Miscellaneous goods and services, 2.4%
Housing and utilities, 1.4%
Recreation, sport and culture, 0.7%
Conversely, prices in the information and communications category and the education group slipped by 5% and 0.8%, respectively.
Comments
Log in or sign up to join the conversation.