
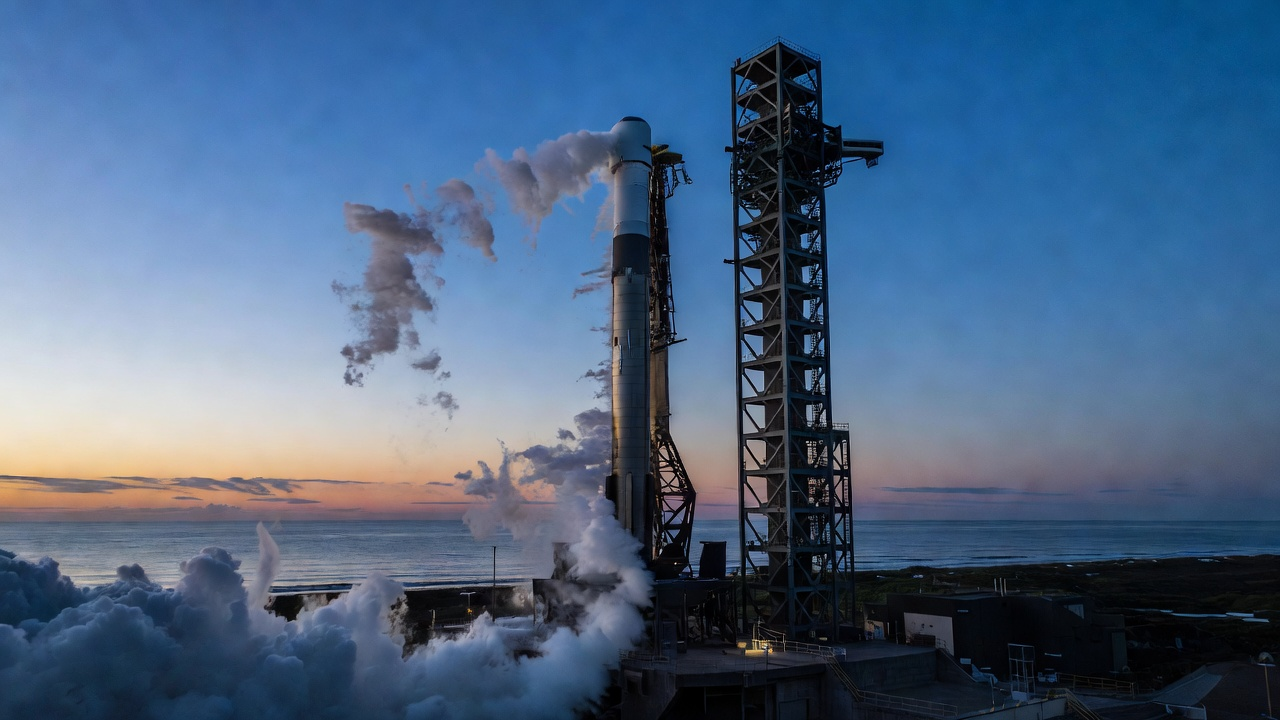
Most people still treat “space stocks” like one lottery ticket built from rockets on TV, moon landers, and tourism selfies. Then they wonder why the group feels random.
My take is simpler. Space is a stack of businesses with very different paychecks. No price targets. No calendar magic. Three seats I care about right now.
What space stocks actually are
A real space stock earns money putting mass into orbit, building satellites and components, selling imagery or connectivity from space, or supporting defense and civil programs that need hardware on schedule. After SpaceX listed as Space Exploration Technologies (SPCX), the map got clearer and messier at once. Clearer because the industry leader is finally on the board near a $1.8 trillion market value with Starlink and launch cadence. Messier because every pure-play now gets compared to that monster whether the business model matches.
There are only about thirty listed space pure-plays worth tracking. Most still lose money. The ones that matter split into launch and systems, satellite communications, Earth observation, exploration, and the primes that hide a space division inside a defense giant. If you buy the theme without naming the paycheck, you are buying a poster.
Worth looking at: Rocket Lab (RKLB)
Rocket Lab Corporation (RKLB) is the name I keep watching because it already has two real businesses, not one unproven showpiece.
Electron is a working small launcher with a long flight history. Space Systems, the spacecraft and components side, now carries most of the revenue. In the second quarter of 2026 the company posted about $234 million in sales, up 62% from a year earlier, with Space Systems near $190 million of that total. Backlog sat near $2.36 billion. Management guided the next quarter to roughly $250 million to $265 million. That is an operating company with orders, not a brochure.
The honest risk is Neutron, the larger reusable rocket. First flight slipped into 2027 after tank work issues, and the stock still prices a lot of medium-lift hope on top of the factory that already exists. Cash burn and dilution stay real while that rocket is unfinished. What would change my mind is Space Systems backlog that stops converting, or Neutron turning into a multi-year science project. Until then, RKLB is the pure-play I treat as worth the homework: paid work on the books plus a bigger rocket that still has to prove itself.
SpaceX remains the scale king. For most self-directed investors, Rocket Lab is still the cleaner public window into commercial launch plus satellite manufacturing.
The wannabe: Virgin Galactic (SPCE)
Virgin Galactic Holdings (SPCE) is the wannabe seat, and I mean that without cute soft language.
This is space tourism as a brand story. The company has not flown customers to space since mid-2024. The next-generation Delta-class ship rolled out, and commercial service has slipped again into the second quarter of 2027 while software and testing continue. Trailing revenue is around a million dollars. Quarterly losses still run in the tens of millions. Cash gets topped up with equity raises while the fleet is grounded.
I respect the dream of regular suborbital flights. A hangar rollout and a ticket waitlist still leave you short of a working business. At roughly $2.77 a share, the stock can rip on any flight rumor. Durable space economics look different. What would flip this seat is sustained commercial flight rate with real cash coming in, not another delay press release. Until the ships fly on a schedule people can trust, SPCE stays tourism theater wearing a space ticker.
The dark horse: Redwire (RDW)
Redwire Corporation (RDW) is my dark horse because nobody puts it on the poster next to Starship, and the order book keeps growing anyway.
Redwire sells space infrastructure and defense technology: structures, power systems, and related hardware that other missions need. In the third quarter of 2026 revenue was about $109 million. Gross margin jumped to roughly 32% from the mid-teens a year earlier. Book-to-bill landed near 1.73. Contracted backlog hit a record about $620 million, up roughly three-quarters from a year earlier. Management reaffirmed full-year revenue in the $450 million to $500 million range even with lumpy shipment timing.
This is a supplier story under government and commercial programs, so milestone timing can still wreck a quarter. Losses are not gone. What would break the thesis is backlog that stops converting into shipped product, or customers that freeze awards. I still like the under-counted angle. While the crowd argues Neutron dates and phone-from-orbit demos, Redwire is booking work that keeps other people’s constellations and defense systems alive.
Bottom Line
Space stocks are not one trade. Rocket Lab is the name worth watching because Electron and Space Systems already sell real work while Neutron still has to fly. Virgin Galactic is the wannabe: tourism branding, thin revenue, and another commercial delay. Redwire is the dark horse quietly stacking backlog in the infrastructure layer most people skip.
Comments
Log in or sign up to join the conversation.