
Palantir Technology Inc. (PLTR) has huge, unusual call option activity today. Palantir released strong Q3 financial results on Nov. 2, including a 53% free cash flow (FCF) margin. Analysts forecast 50% higher revenue, but PLTR is down. Is the stock too cheap, and is that why call option activity is so high?
PLTR is down 3.6% today at $171.91 and down 14.9% over the last 2 weeks from $201.72 on Oct. 21. And from Oct. 9, when PLTR peaked at $209.05, it's down 17.8%.
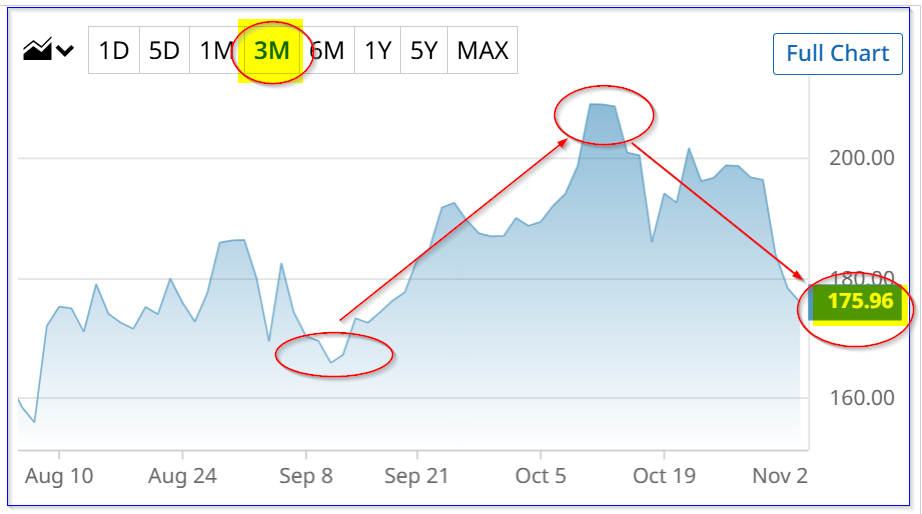
PLTR stock - last 3 months - Barchart - Nov. 3, 2026
But has Palantir really lost almost 18% of its underlying value in the last month, especially given its strong FCF results? Not likely. That could be one reason behind the call option activity.
Unusual PLTR Call Options Activity
Barchart's Unusual Stock Options Activity report today shows this huge call option volume in PLTR expiring Dec. 4, 2026. Over 1,050 call contracts have traded at the $190 strike price for a $3.56 premium.
That is over 8 times the prior number of calls outstanding at that strike price and expiry period.
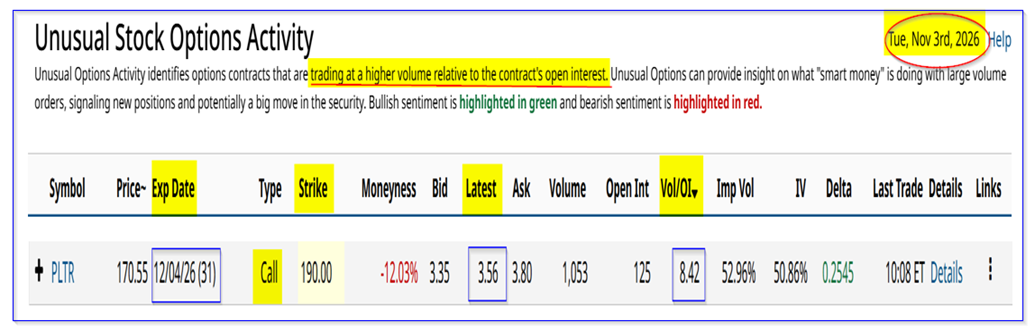
PLTR call options expiring Dec. 4, 2026 - Barchart Unusual Stock Options Activity Report - Nov. 3, 2026
That means call buyers expect PLTR to rise by $21.65 to $193.56, or +12.6% in the next month. And that's just to break even (i.e., $193.56/$171.91-1).
They may feel that the stock's tumble has been overdone. However, there could also be multileg plays, including call credit spreads.
That implies that some of these call option buyers have shorted lower strike prices but bought the $190 strike price to act as a hedge against potential short losses.
In addition, some call option sellers may be existing shareholders selling covered calls. They collect a one-month 2.07% yield (i.e., $3.56/$171.91).
Moreover, even if PLTR rises to less than $190 before Dec. 4, they get to keep the unrealized gains.
So, on balance, this heavy call option activity may be initiated by essentially bullish investors. However, some credit spread investors are hoping for PLTR to not rise over $190.
Let's look at what PLTR could be worth.
Palantir's Higher Projected Adj. FCF
Palantir reported that its software and technology Q3 revenue rose 95.87% YoY and 19.5% QoQ. Moreover, its adjusted free cash flow (FCF) was up 125% and represented 52.6% of revenue.
That adj. FCF margin was higher than last year's 45.7% figure, implying huge operating leverage. In other words, as revenue rose, cash flow rose even faster. This is because its costs don't rise as fast as revenue as it goes up.
For example, for the past 9 months, its adj. FCF margin was 62% vs. 47% last year. Moreover, management said it expects adj. FCF between $4.8 billion and $5.0 billion ($4.9b on average), and between $8.53 billion and $8.534 billion ($8.532b avg.). So, for 2026, they expect an adj. FCF margin of 55.5%.
That implies that, as analysts project higher revenue next year, the adj. FCF margin should rise over 55%.
For 2027, they are projecting a 50.8% revenue gain to $12.88 billion. So, just to be conservative, let's assume a similar 53% adj. FCF margin, just like in Q3 (and lower than the projected 55.5% adj. FCF margin:
$12.88 billion x 0.53 = $6.8264 billion adj. FCF
That is 39.3% above management's projected $4.9 billion adj. FCF for 2026. As a result, this could imply a higher PLTR valuation.
Higher PLTR Price Targets
For example, using an average 1.333% FCF yield, PLTR could be worth over $512 billion:
$6.8264b / 0.01333 = $512 billion
That is 21.3% over today's market cap of $421.9 billion, according to Yahoo! Finance. So, the price target (PT) is 21% higher:
$171.91 x 1.213 = $208.53 per share
Other analysts agree. Yahoo! Finance has a $216.00 average PT from 33 analysts, and Barchart's mean survey PT is $217.97. These are higher than my PT using a 53% adj. FCF margin and a 1.333% FCF yield.
This could be one reason why there is so much call option activity today in Palantir Technology (PLTR) stock.
Comments
Log in or sign up to join the conversation.