
Image: Bigstock
The Q3 earnings cycle is heating up, with this week's reporting docket partly highlighted by Magnificent Seven member Meta Platforms (META - Free Report). The release will be particularly important given the company's aggressive AI investments, with investors looking for continued growth to help justify its massive spending spree.
META Advertising Results
As expected, advertising results will remain a primary focus, with Meta's massive user base continuing to attract advertisers across its platforms. Advertising momentum has remained rock-solid as of late, with ad impressions climbing 14% YoY throughout its latest reported quarter. Average price per ad also increased by 12%, reflecting continued strength in monetization.
Our consensus estimate for advertising revenue stands at $61.9 billion, reflecting a double-digit 23.5% YoY growth rate compared to the same period last year. The company has regularly posted better-than-expected advertising results, exceeding our expectations in each of the last five periods.
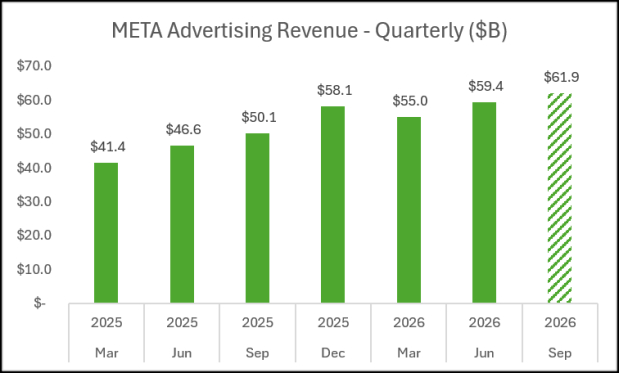
Image Source: Zacks Investment Research
Muse & AI Spending
Investors will also be listening closely for commentary on Muse, Meta’s recently launched personal AI agent that can complete tasks across the web and connected applications. Early reception appears to be positive, with reports indicating more than two million daily users following its launch back in September.
Continued adoption of Muse can easily justify the company's massive AI investments, with the market looking for further signs of momentum in the newly released app. Overall, the development ties into its massive capital expenditures, which have weighed on its cash-generating abilities, with META guiding for $130-$145 billion in capital expenditures for 2026.
META Headline Expectations
EPS expectations for META have trended downward in recent months, while revenue expectations have trended the opposite way. The growth picture is similarly mixed, with earnings expected to fall roughly 19% alongside a 23.5% YoY jump in revenue.
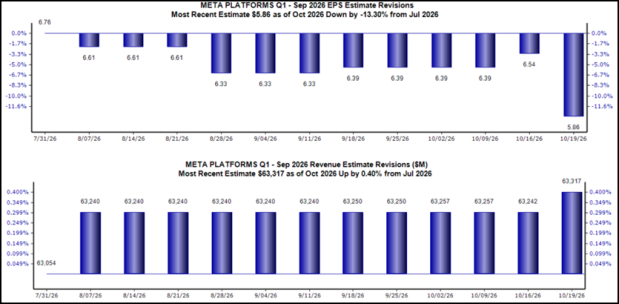
Image Source: Zacks Investment Research
Bloom Energy and Western Digital Also Report
Outside of META, several other companies with ties to the AI boom are also on the docket, a list that includes Bloom Energy (BE - Free Report) and Western Digital (WDC - Free Report).
Bloom Energy has enjoyed explosive growth thanks to rising electricity demand, particularly from data centers. Our consensus estimates suggest another period of outsized growth, with sales expected to climb by nearly 375% YoY on 106% higher revenues.
EPS and sales expectations have trended higher over recent months, though the sales outlook has primarily been stable.
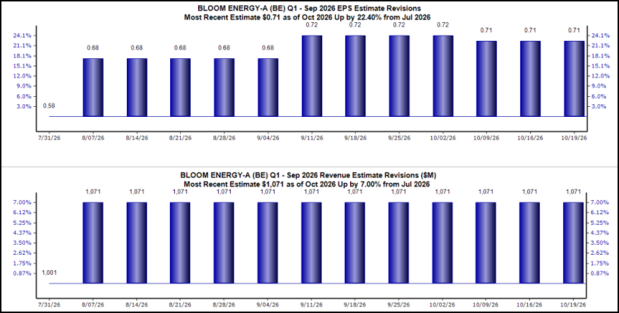
Image Source: Zacks Investment Research
Western Digital has similarly benefited from AI-related demand, with demand remaining red-hot for its high-capacity enterprise hard drives. Western Digital is similarly expected to see another period of hot growth, with our consensus estimates suggesting 130% YoY earnings growth on 48% higher sales.
EPS and sales expectations are higher than where they stood near the beginning of August, showing stability since.
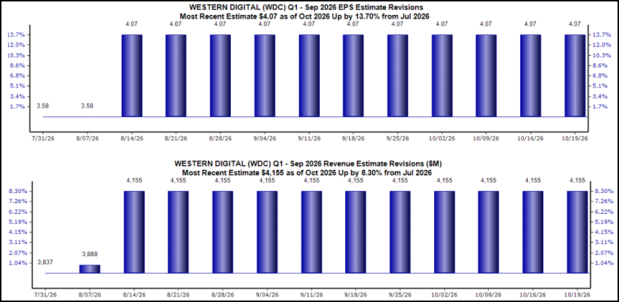
Image Source: Zacks Investment Research
Bottom Line
The upcoming release from Meta Platforms will provide an important look into how AI-related spending has translated. While advertising growth remains strong, the company's aggressive investments have drawn scrutiny, and the release will be a key hurdle to clear concerning sentiment surrounding shares.
Bloom Energy and Western Digital will also provide valuable insights into the broader AI infrastructure demand picture, with both companies enjoying robust growth heading into their respective releases.
Comments
Log in or sign up to join the conversation.