
Image: Bigstock
The Q3 earnings cycle continues to wind down, with this week’s reporting docket featuring several retail heavyweights, including Walmart (WMT - Free Report), Target (TGT - Free Report), and Home Depot (HD - Free Report).
The releases will provide valuable insight into the health of the U.S. consumer, particularly as affordability concerns, elevated fuel costs, and a sluggish housing market continue to impact spending habits. All three stocks have seen differing levels of momentum recently, with Target enjoying a big rebound and Walmart continuing to benefit from its defensive characteristics.
Walmart
Walmart is scheduled to report this Thursday, November 19th, before the open. The Zacks Consensus Estimate calls for $0.64 per share in earnings on $186.5 billion in revenue, reflecting year-over-year growth rates of 3% and 4%, respectively.
Walmart’s value-focused offerings have remained attractive amid consumer spending pressures, with its grocery business and growing appeal among higher-income shoppers helping provide a nice blend of defense and growth.
Comparable sales will be a major focus, with expectations calling for 2.9% U.S. growth on an ex-fuel basis. The metric grew 2.6% YoY in the preceding quarter, reflecting a slowdown that contributed to the stock’s weak reaction following its last release.
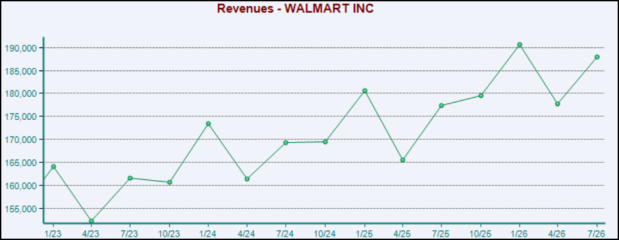
Image Source: Zacks Investment Research
Target
Target will report this Wednesday, November 18th, with our Consensus Estimates suggesting $2.04 per share in earnings and $26.4 billion in sales. The estimates reflect growth rates of roughly 15% in earnings and 4% higher sales.
The stock has enjoyed a notably strong rebound throughout 2026, delivering a 70% year-to-date total return compared with Walmart’s 16%.
Target’s recent performance has been supported by improving profitability and encouraging comparable-sales trends, with the latter growing 3.8% YoY in its latest release. The upcoming release is expected to show 3.2% comparable-sales growth, with discretionary spending trends particularly important given Target’s greater exposure to categories outside everyday essentials.
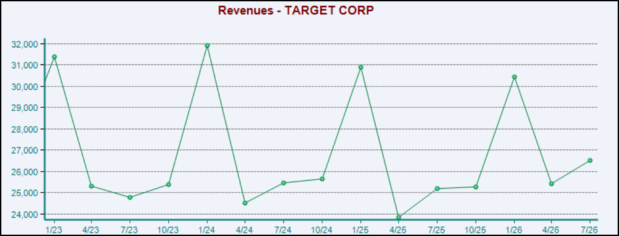
Image Source: Zacks Investment Research
Home Depot
Home Depot will kick off the trio’s reporting schedule on Tuesday, November 17th. The Zacks Consensus Estimate calls for $3.86 per share in earnings on $42.7 billion in revenue, reflecting roughly 3% growth on both metrics.
The housing market remains a major headwind, with sluggish home turnover weighing on demand for larger remodeling projects. Simply put, fewer home transactions translate to fewer opportunities for sizable home improvement purchases.
The company has benefited from more resilient spending on smaller projects, with its professional customer business also providing support. Comparable sales increased 1.7% in its latest release, a key metric to watch for signs of improving demand.
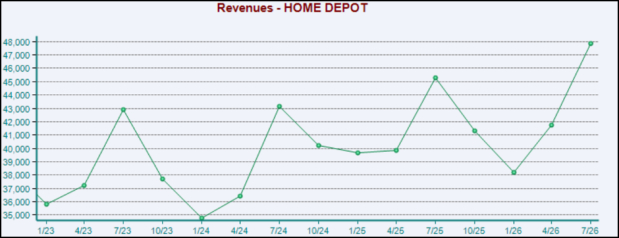
Image Source: Zacks Investment Research
Bottom Line
This week’s retail releases will provide a clearer picture of consumer spending patterns heading into the critical holiday shopping season.
Walmart’s value positioning, Target’s recovery, and Home Depot’s housing-related exposure each tell a different story. Above all, comparable sales trends and management’s forward guidance will be critical in determining near-term share movement.
Comments
Log in or sign up to join the conversation.