
The U.K. stock market’s benchmark FTSE 100 surrendered its early gains to turn modestly negative into the close, with the index down 0.30%. An initial bounce driven by mining and tech shares faded as a broader shift in global sentiment—sparked by a lack of substance from the eagerly anticipated Trump-Xi summit, rising U.S. bond yields, and a sharp pullback in oil prices—dragged on market heavyweights.
Energy majors bore the brunt of the late-session weakness as crude prices retreated amid renewed hopes that a fresh proposal submitted by Iran to the U.S. could help resolve the Middle East conflict and reopen the Strait of Hormuz. Brent crude futures fell nearly 2% to trade around $98.34 a barrel, sending energy plays Ithaca Energy, BP, and Shell down 4.9%, 3.2%, and 1.2%, respectively. Additional downside pressure saw British American Tobacco, BAE Systems, Babcock International, Bunzl, Imperial Brands, Smith & Nephew, Haleon, Tesco, Admiral Group, and Convatec Group drift down 0.7% to 1.7%.
Despite the benchmark turning lower, pockets of strength remained across mining, technology, and select financials. IT provider Computacenter topped the list of gainers, climbing 3.75%, while investment firm 3i Group added 3.4%. Precious metals miners held onto early firming, with Endeavour Mining and Fresnillo advancing 3% and 2.8%, respectively, while Antofagasta, Anglo American Plc, and Glencore gained between 1.5% and 1.7%. Broad-based buying across industrials and banking lifted Smiths Group, Standard Chartered, Aberdeen Group, IAG, Lloyds Banking Group, and Informa by 2% to 3%. Informa, Lion Finance, Barratt Redrow, Polar Capital Technology Trust, AutoTrader Group, BT Group, St. James's Place, and Barclays added 1.5% to 1.9%, while water utility United Utilities gained over 1% after reiterating its 2026-27 financial guidance and regulatory return targets.
On the domestic economic front, consumer sentiment provided a small positive signal. The GfK Consumer Confidence Index rose to -13 in September from -14 in August, beating consensus expectations of -16 and reaching its highest level since August 2024.
Next week will see a busy domestic data calendar. Tuesday kicks off with UK money and credit figures, followed by Wednesday's Lloyds Business Barometer, final Q2 GDP, and current account data. The primary highlight arrives on Friday with the Bank of England's Decision Maker Panel (DMP) survey, a key indicator for wage and price risks that could significantly influence market expectations ahead of the MPC's November rate decision.
Finish Line: The FTSE 100’s early attempt to snap recent weakness faded into the close as a heavy sell-off in energy majors outweighed early gains in miners, tech, and financials. While improving consumer confidence and resource strength provided a buffer, falling crude oil prices and broader international policy uncertainties ultimately pushed the benchmark into the red.
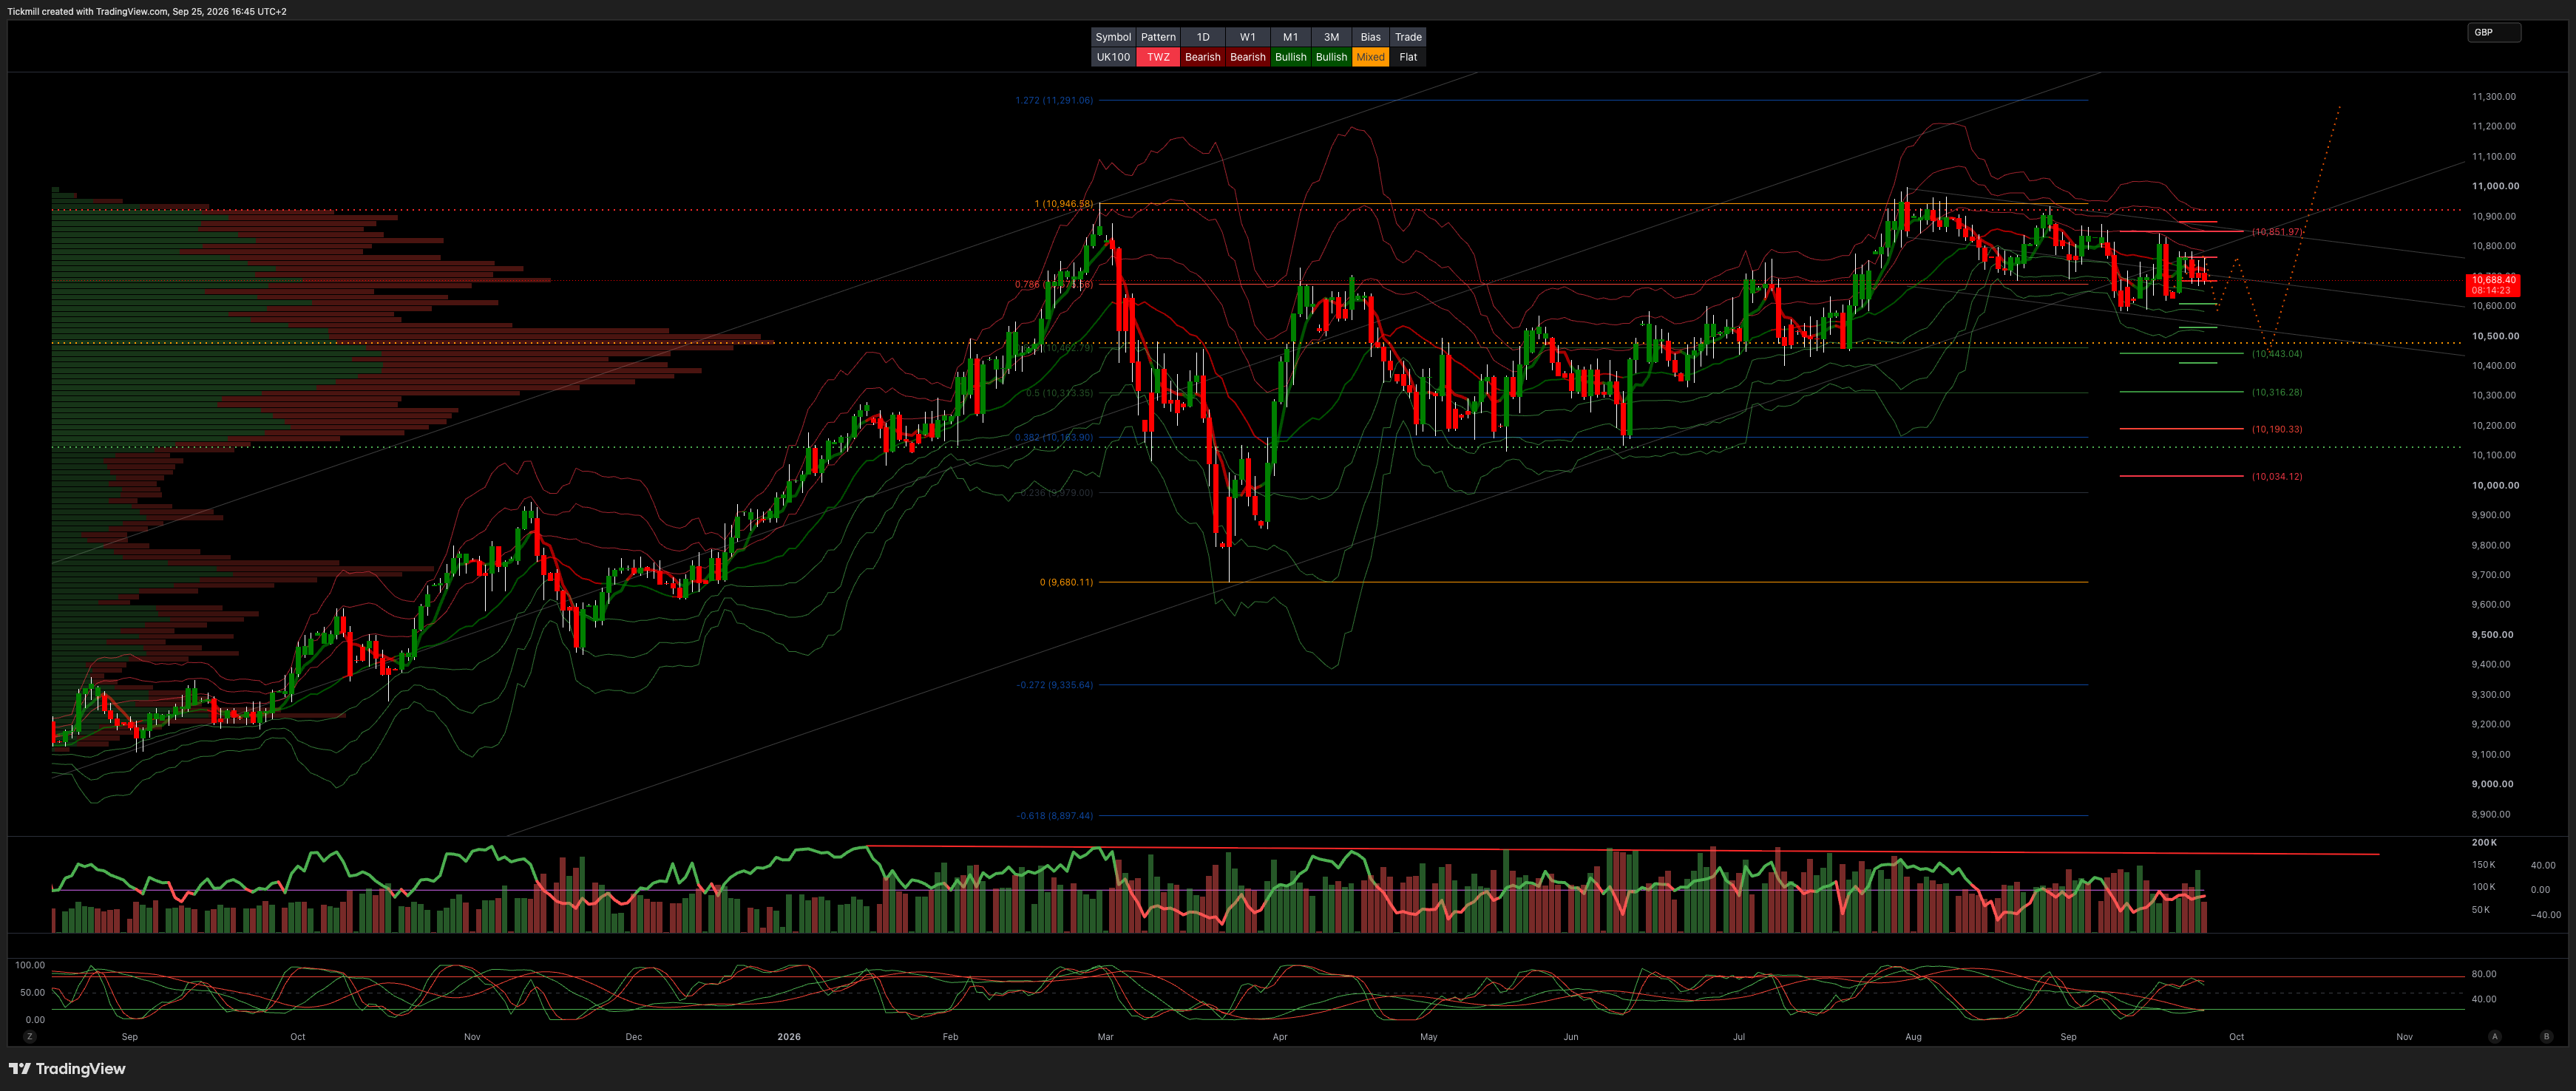
TECHNICAL & TRADE VIEW
Comments
Log in or sign up to join the conversation.