
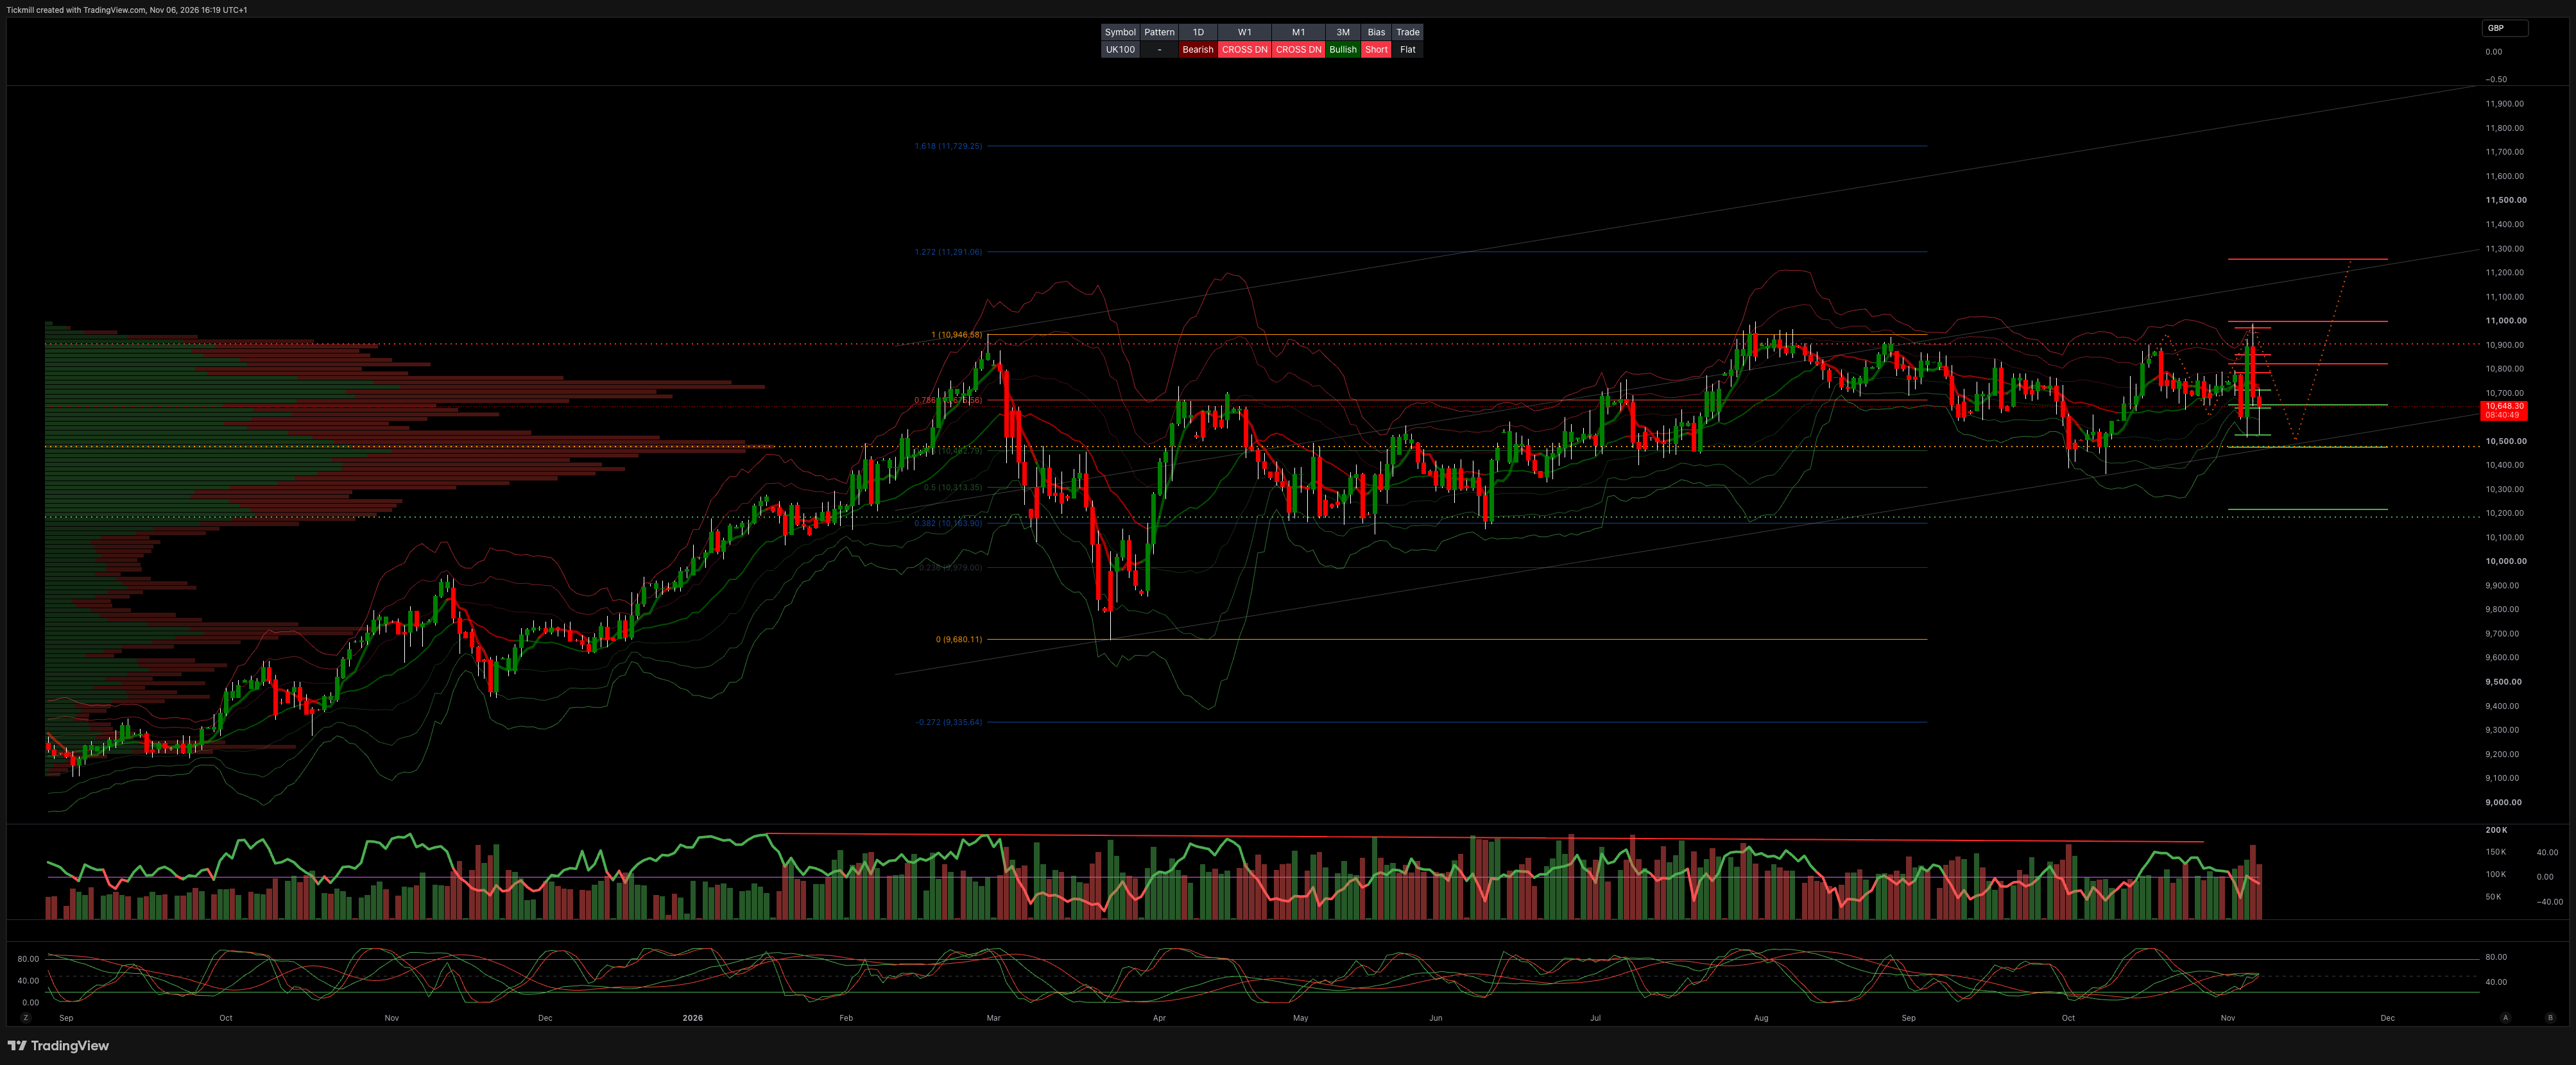
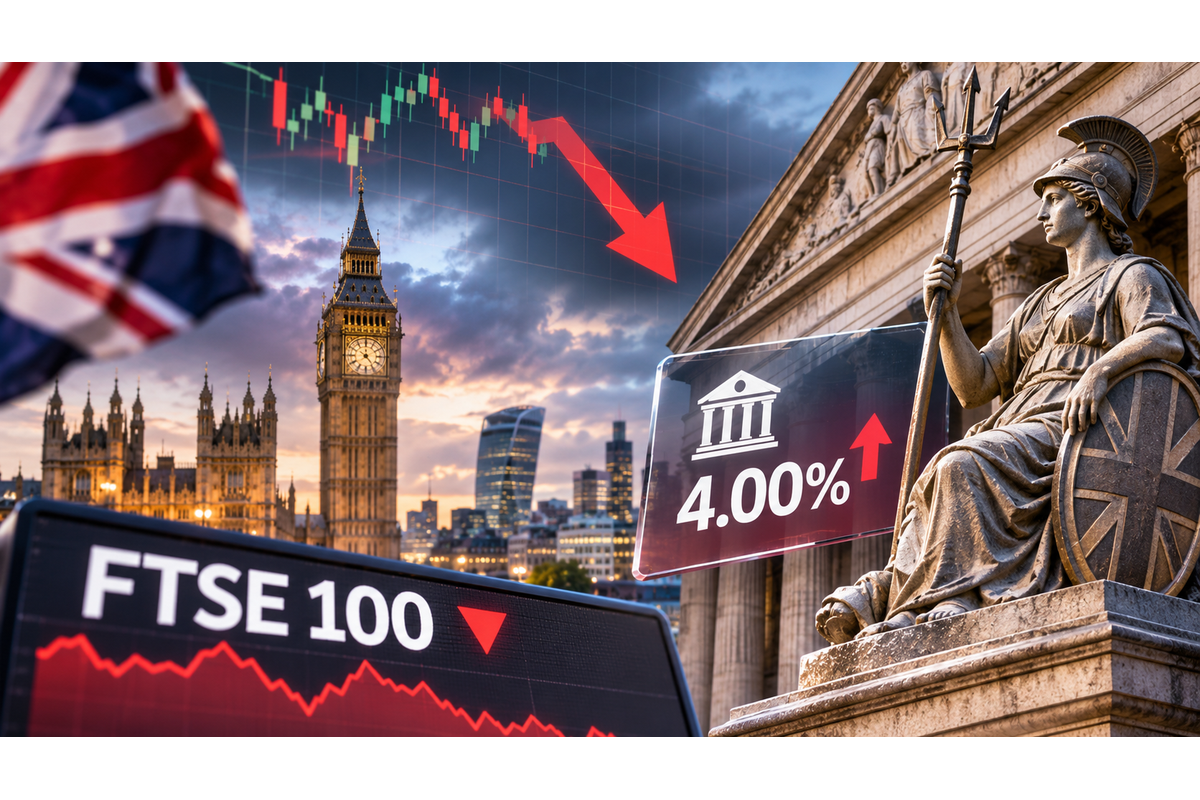
London's benchmark FTSE 100 tumbled to a four-week low on Friday morning as an aggressive global equity sell-off gripped markets before short covering and profit-taking on bearish positions trimmed the day's losses into the weekend. Having plunged as much as 245.86 points, or 2.28%, to an intraday low of 10,536.80 before noon, the blue-chip index staged a steady afternoon recovery in tandem with a bounce on Wall Street, settling down approximately 0.5% to end a volatile week. Uncertainty surrounding the broader macroeconomic implications of the U.S. midterm elections, paired with the domestic fallout from Thursday's Bank of England rate hike, triggered a wave of de-risking across blue chips.
Widespread selling pressure swept through almost every major sector. Telecom major BT Group dropped around 5%, giving up recent post-earnings gains, while steep declines of 4.1% to 4.7% hit Airtel Africa, RELX, WPP, Experian, and pharmaceutical giant AstraZeneca. Extensive losses between 3% and 4% battered cyclical, consumer, and financial names, including Next, The Sage Group, British American Tobacco, London Stock Exchange Group (LSEG), Marks & Spencer, National Grid, Associated British Foods, Vodafone Group, Pearson, Smith & Nephew, Imperial Brands, Burberry Group, GSK, Reckitt Benckiser, Haleon, and Aviva. Additional heavy selling extended across Unilever, Bunzl, Aberdeen Group, Hiscox, Tesco, Informa, ICG, Coca-Cola Europacific Partners, Diageo, BAE Systems, and oil majors Shell and BP.
Bucking the broad rout, only a handful of defensive and resource counters managed to hold positive ground. Metlen Energy & Metals climbed 1.5% to lead the risers, while precious metal miners Fresnillo and Endeavour Mining posted modest gains alongside Scottish Mortgage Investment Trust and engineering specialist Weir Group.
On the monetary policy front, Bank of England Chief Economist Huw Pill delivered balanced remarks at a BoE Agents briefing, offering context on Thursday's rate hike to 4.00%. Pill noted that the decision carried a "pre-emptive character" driven by concerns over near-term inflationary pressures, observing that while firms have been absorbing higher input costs into margins, "that is not sustainable". While acknowledging the central view that the economy is expanding more strongly than anticipated, Pill emphasised that interest rates are already "close to neutral levels" and that the future rate trajectory is by no means "baked in". Clarifying that policy is unlikely to replicate the aggressive multi-hike cycle of 2022, he stated that risks for next year are more balanced and that whether another rate increase is warranted will depend on incoming data on second-round effects over the coming weeks.
On the domestic economic front, housing data revealed deepening strain from elevated borrowing costs. U.K. house prices fell for a third consecutive month in October, declining 0.6% month-on-month and dropping 1.2% year-on-year—the sharpest annual contraction in three years compared to a 0.1% dip in September. The deterioration reflected renewed mortgage affordability pressures driven by persistent inflation and heightened Middle East energy volatility.
Looking ahead to next week, the macroeconomic schedule ramps up significantly. Thursday brings a critical U.K. data package featuring preliminary Q3 GDP, industrial production, and trade statistics, alongside key inflation, credit, and trade data from China. Central bank rhetoric will also be in focus, with scheduled appearances from the Fed's Christopher Waller and John Williams, the BoE's Andrew Bailey and Huw Pill, and the ECB's Philip Lane.
Finish Line: U.K. equities capped a turbulent week by clawing back the worst of an aggressive morning rout as late short-covering cushioned a slide to one-month lows. While Huw Pill's remarks provided reassurance that the BoE is nearing a neutral rate plateau rather than an aggressive tightening cycle, persistent housing weakness and global political uncertainty keep index bulls on guard ahead of next week's crucial Q3 GDP print.
Comments
Log in or sign up to join the conversation.