
There was nothing to like in today’s CPI report. This chart is the result.
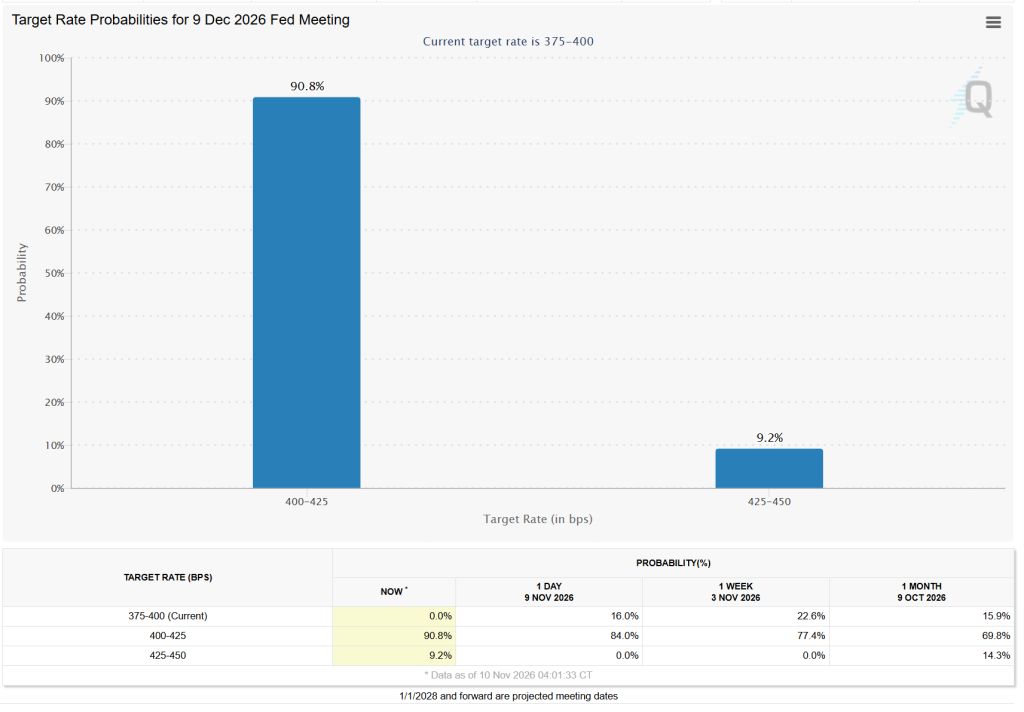
For a brief time today, the implied CME Fedwatch odds of a 25-basis-point hike plus a 50-basis-point-hike added to over 100 percent.
The double hike odds soared to something like a 22 percent chance. I failed to capture the chart, but made a mental diagnosis – forget about it.
It’s always baby steps on hikes. Giant steps are reserved for rate cuts.
All Eyes on Fed Governor Christopher Waller
Waller set the double-hike scenario in his play with a speech in the U.K. just ahead of the CPI release.
Please consider the key aspects of The Economic Outlook and Some Thoughts on Labor Market Dynamism by Governor Waller.
The outline of my speech is to first explain why I voted to hold the policy rate steady at the most recent meeting of the Federal Open Market Committee (FOMC). Then I will talk about the general state of the U.S. economy. After that, I will ask some open-ended questions about the dynamism of the U.S. labor market that are important to consider over the longer run. I’ll follow that by a discussion of recent inflation data and then describe my views about the future path of monetary policy.
At our most recent meeting, I supported the FOMC majority in holding monetary policy at its current setting. As I said in a speech a couple weeks before then, my rationale was that the Committee’s communication about the likely tightening of policy had already led financial markets to price in some tightening. When this communication is clear and credible, what really matters is that those hikes are eventually carried out—it is not necessary, for example, to raise rates at consecutive meetings.
[Mish: That is striking because Fed Chairman Kevin Warsh does not want forward guidance. We got forward guidance anyway, by everyone else.]
If, however, the hikes are not carried out, markets will reduce expectations of rate hikes and rates will immediately fall, which would loosen monetary policy in an undesirable way. So, while the precise timing of the hikes doesn’t matter, ensuring that the promised hikes are implemented in a reasonable period of time does.
[Mish: While I sympathize somewhat, Fed policy in retrospect is always late on hikes and early on cuts. We listened to transitory nonsense for a year. Second, I believe Waller is flat out wrong as to how the bond market would react at the long end of the curve. Yields would continue to surge.]
To recap my economic outlook, economic activity is strong, the labor market is stable, but inflation is too high, well above the FOMC’s 2 percent goal. This means that even if, as I expect, the monthly rate of inflation improves in October, I am leaning toward supporting an increase in our policy rate of 25 basis points at the FOMC’s December meeting.
That’s my plan if things proceed as I expect. But if the October CPI inflation data out later today are similar to the past two monthly readings—with core CPI inflation around 0.3 percent or even higher—then a stronger policy move may be needed. In that case, I believe a 50 basis point hike in the policy rate should be considered at the December meeting. Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take.
Waller Was Wrong, As Expected Here
Waller expected a tame CPI today, just hours before the CPI release. What a hoot!
On a long timeline horizon, the arrogance of the Fed is to always expect its policies to work even when it is obvious to the rest of the world its policies are not working.
To me it was a near given the Fed would hike in December.
Waller is trying to sound tough today, but the record shows he wimped out and is trying to explain it away.
Waller’s Timing
Waller’s speech came out before the report, but I did not see it until after the report when the Wall Street Journal commented Hot Inflation Revives Wall Street’s Rate Hike Fears
Fed governor Christopher Waller struck first, warning that he could support a larger-than-normal 0.5 percentage point rate increase in December if Tuesday’s consumer-price index report showed core prices rising 0.3% from the previous month. Then came that very CPI report, which laid out that very scenario. Bond prices tumbled, and investors scrambled to reset odds of future rate increases.
“Waller’s comments really laid the groundwork for pretty substantial market-sensitivity to an upside surprise, and that’s what we got,” said Zach Griffiths, head of investment-grade and macro strategy at the research firm CreditSights.
The journal did not link to Waller’s speech.
In general, mainstream media never links to anything but themselves.
I try to be meticulous with links so people can see for themselves who reported what.
Poor linking is a rampant disease.
CPI Hotter than Expected Again
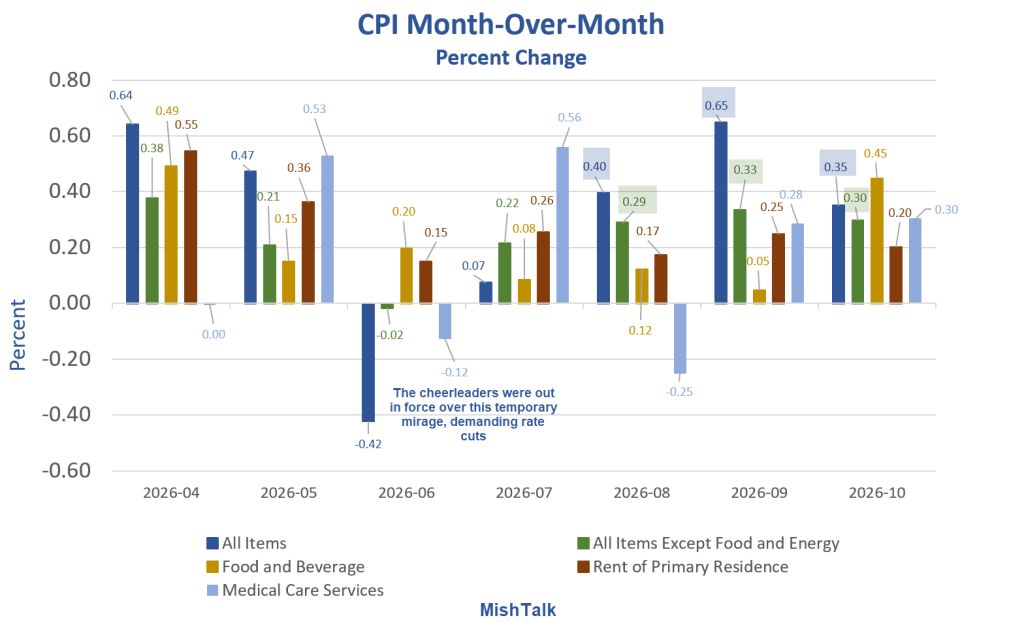
Earlier today, I commented CPI Hotter than Expected Again. Expect a December Fed Rate Hike
This was the third consecutive bad month for CPI inflation.
There are no bright spots in October. Every index is over the Fed target.
Another Fed Rate Hike Coming
In August I said “A rate hike in September is all but certain after this report.”
And so it was.
Last month I said there would not be a hike in October, but there should be. That was correct as well.
My statement from a month ago was “As of now, expect a December hike. There is no November meeting.”
The Fed went out of its way to issue forward guidance when a parade of Fed governors and presidents pushed back on an October rate hike, without mentioning the obvious reason – the election.
Fed Chair Kevin Warsh stopped forward guidance in theory, but not practice, The Fed will always find a reason to do what it wants and telegraph it, forward guidance or not.
The Fed is behind the curve again.
Flashback October 14, 2026
Please consider CPI Hotter than Expected in September, Up 0.65 Percent written about a month ago.
The Fed should hike in October, but won’t until December.
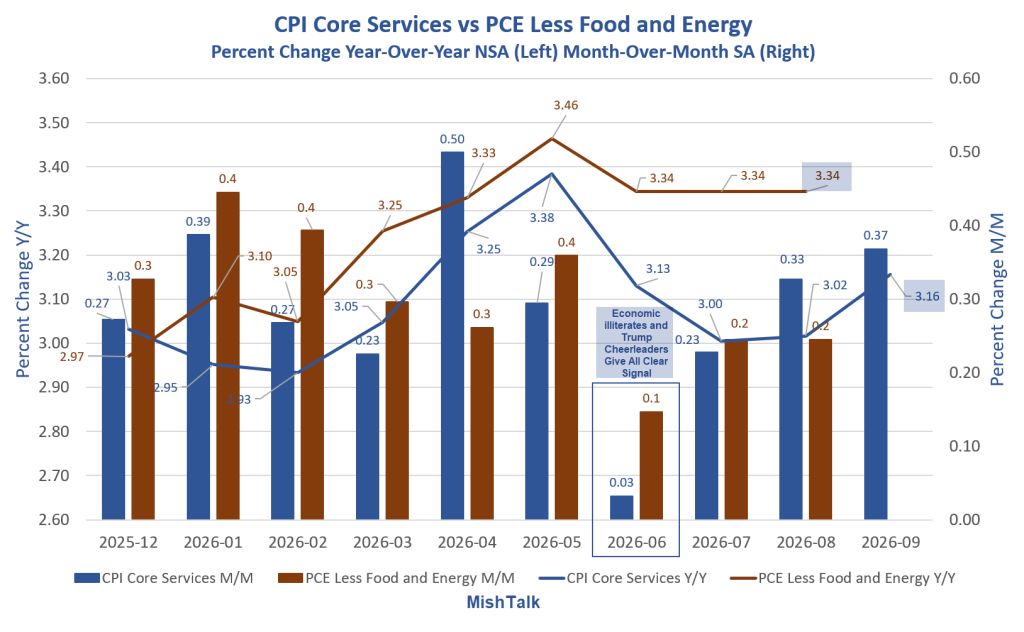
CPI Core Services vs PCE Less Food and Energy
Core Services M/M and Y/Y
CPI Core Services M/M: 0.37 percent
CPI Core Services Y/M: 3.16 percent
PCE Services Less Food and Energy M/M: 0.20 percent (August)
PCE Services Less Food and Energy Y/Y: 3.34 percent (August)
This is the key chart in this post because the Fed’s preferred measure of inflation is PCE excluding food and energy.
The Fed has missed inflation targets for 63 straight months on PCE and 65 straight months on the CPI.
I fail to see how anyone can get a rate cut or even a rate hold out of that chart.
CPI and PCE Are Both Understated
Neither measure counts property taxes, homeowner’s insurance, or home prices.
Food is understated because of improper weights.
Medical insurance costs are ridiculously calculated based on retained earnings, not consumer prices.
Yet, economists wonder why people are more upset about inflation than what the numbers show.
Another Fed Rate Hike Coming but Delayed
Last month I said “A rate hike in September is all but certain after this report.”
And so it was.
I also said there would not be a hike in October, but there should be. This report sealed the “should be” aspect.
However, the Fed went out of its way to issue forward guidance when a parade of Fed governors and presidents pushed back on an October rate hike, without mentioning the obvious reason.
I never expected a hike because the next meeting is October 28, just 6 days before the midterm elections.
Following the parade of Fed yaps, rate hike odds for October plunged from over 60 percent to 20 percent, now back up to 33 percent today (but headed to zero).
Fed Chair Kevin Warsh stopped forward guidance in theory, but not practice, The Fed will always find a reason to do what it wants and telegraph it, forward guidance or not.
As of now, expect a December hike. There is no November meeting,
I believe it’s safe to say that I made an accurate assessment.
Related Posts
October 7, 2026: Long-Term Bond Yields Surge to New 24-Year Highs
What happened to Bessent’s “I am the house” theory?
November 6, 2026: Jobs Gain 165,000 Led by Services, Up 144,000. Unemployment Drops
The jobs report was better than expected with an upward revision.
November 7, 2026: Making Healthcare Harder to Get Won’t Make Healthcare More Affordable
Here’s a well thought out Tweet on Healthcare.
Comments
Log in or sign up to join the conversation.