
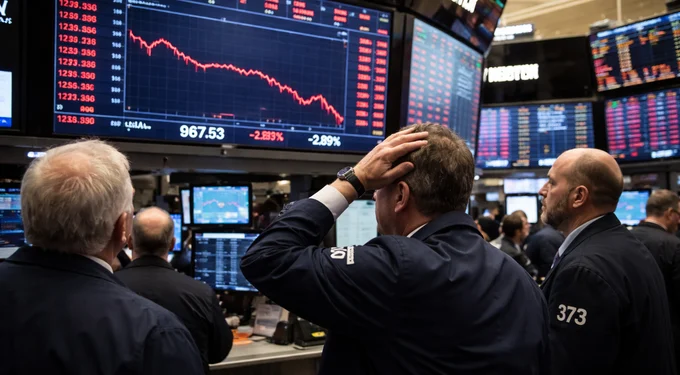
The S&P 500 is declining for the seventh consecutive session as the tech rout extends amidst a huge amount of derisking occurring here on Wall Street. The Nasdaq 100 is down nearly 4% and has effectively erased its year-to-date gains, as investors rapidly unload AI exposure in consideration of the monumental risks on the horizon. First off, a Jensen-less Nvidia (NVDA) is worrying participants about the lack of an influential hype-man that can support the sector during times of anxiety, like in the current moment. Additionally, investors are concerned that Asian momentum will decelerate in light of the space’s China avoidance, posing headwinds to revenue and earnings prospects. The blue sweep in the midterm election, which handed significant majority controls of both chambers of Congress to the Democrats, is also generating jitters pertaining to heavier regulations and stricter oversight. The four major US stock benchmarks are tanking as a result, but 5 of the 11 principal sectors are advancing while capital allocators lift exposures to the defensive consumer staples, healthcare, utilities and real estate categories, as well as the energy segment, even as oil prices decline on strengthening Middle East crude exports. Cheaper fuel alongside heavy safe-haven demand is plunging yields by more than double-digits at the short-end, contributing to the Treasury curve descending aggressively in bull-steepening motion, as the odds of a one-and-done hike by the Fed to end the current tightening cycle rises meaningfully. That dovish tilt is weighing on the greenback, while deteriorating sentiment crushes cryptocurrencies and commodities but lifts premiums on volatility protection instruments substantially, with the VIX exceeding 32, its highest level since March.
At Risk of a Down Year
Wall Street is at risk of having its first down year since 2022, which also happened to feature a midterm election and Fed rate hikes. But with the dramatic collapse from fresh equity records occurring a little over six weeks ago, a prolonged period of lackluster stock returns could be upon us. It could be the case, that the bull market could have ended in October, as serious doubts about AI’s ability to power corporate earnings and the economy forward are reflected via punishing repricing occurring across shares and fixed-income assets. And with risks piling up, investors are seeking free cash flow yields from these massive capital expenditures more than ever; nonetheless, the nosebleed expectations that drove this theme into the stratosphere amidst elevated potential of a meaningful slowdown have created too wide of a gap for overall firms to satisfy participants at this juncture.
International Roundup
China Holds Key Interest rates
The People’s Bank of China decided this morning to keep its one- and five-year prime rates unchanged at 3% and 3.5%. Those generally accommodative rates have been in place for more than a year with the central bank seeking to juice weak domestic demand. The central bank has maintained the current rate for slightly more than a year.
Retail Sales Strengthen in the UK
Retail sales volumes in the UK strengthened in October and exceeded economist consensus estimates, according to preliminary data from the Office for National Statistics. Consumer shopping grew 0.7% month over month (m/m) and 2.3% year over year (y/y) following September’s 0.6% slip and anemic annual gain of only 0.4%. Economists estimated that October would post no monthly change and a y/y gain of only 1.7%. Pain at the pump caused purchases of automobile fuel to fall 2.2% by volume last month. The contraction dragged down the broad headline result. Indeed, the core retail sales metric, which excludes auto fuel, was up 0.9% m/m and 2.5% y/y. Both metrics strengthened from September’s 0.9% m/m descent and anemic 0.4% annual gain. At the same time, they easily exceeded the economist consensus expectations for a 0.1% m/m dip and a 0.7% y/y ascent. For the monthly headline print, sales at other non-food stores, textile clothing and footwear, non-store retailing and food stores climbed 3.1%, 1.5%, 0.9% and 0.8%. Department stores and household goods stores experienced declines of 1.2% and 1%.
But In Mexico, Retail Activity Weakens
Mexican consumers trimmed their spending in September by 0.3%, which matched the economist consensus estimate and weakened considerably from the preceding month’s strong 1.2% expansion. Sales were still 2.2% higher than in the year-ago period. Nevertheless, the y/y result decelerated from 3.3% in August and missed the economist consensus prediction of 2.7%.
And Canada Experiences Sales Decline
The value of retail transactions in Canada is expected to have sunk 1.5% m/m in October, according to a preliminary estimate from Statistics Canada. The result is based on responses from 58.1% of companies that were surveyed. Statistics Canada also provided final data for September. In that month, the value of cash register transactions was up 0.8% m/m. Sales were up in five of nine subsectors, led by increases at gasoline stations and fuel vendors.
Comments
Log in or sign up to join the conversation.