
Italian headline inflation jumped above 4% in September, but the underlying picture remains considerably softer. This is still very much an energy story, with additional support from unprocessed food, another volatile component – a combination which will be increasingly felt by households
Istat’s preliminary estimate puts national consumer price inflation at 4.2% year-on-year, up from 3.3% in August, which is higher than expected. Harmonised inflation rose to 4.1% YoY from 3.2%, with the 2.0% monthly rise also reflecting the end of the summer sales.
Energy prices push inflation above 4%
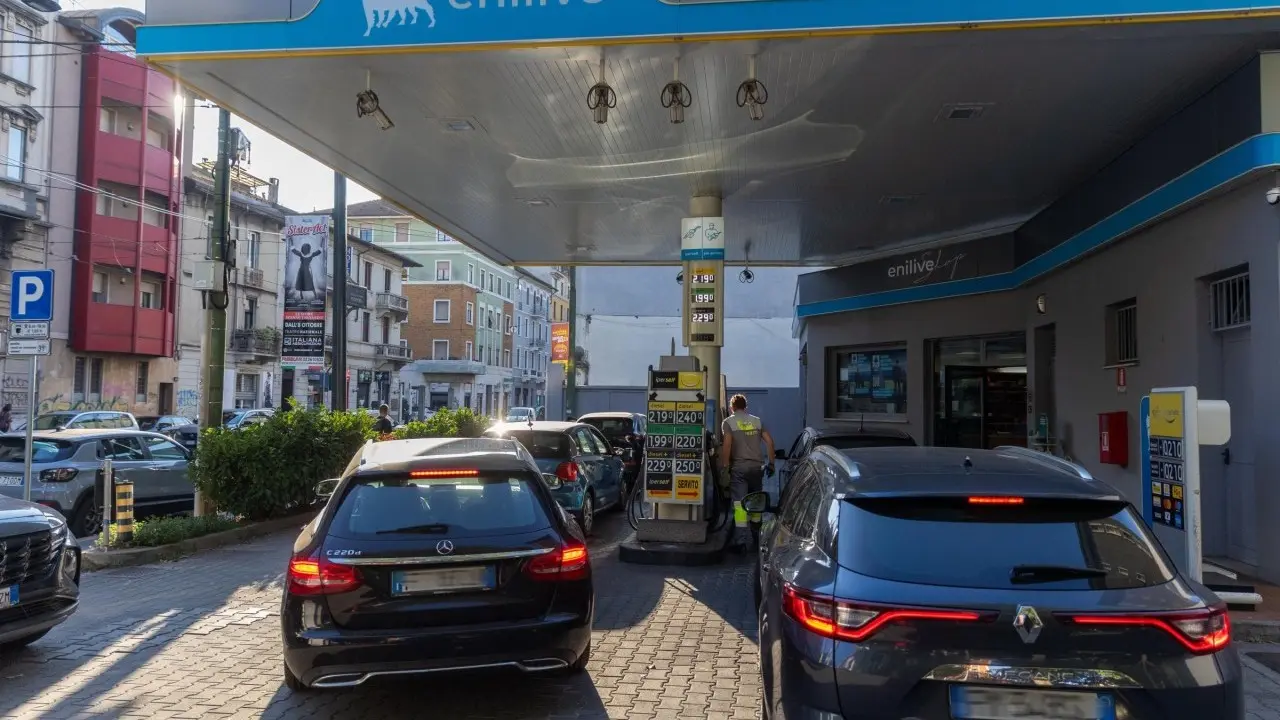
The renewed acceleration was overwhelmingly energy-driven. Energy inflation rose to 22.3% from 17.1% as prices rose sharply across both regulated and non-regulated components. Regulated energy inflation reached 25.9%, led by a sharp rise in protected-market gas prices, while non-regulated energy rose by 22.2%, reflecting sizeable increases in motor fuels, heating oil, free-market gas and electricity.
Food inflation also strengthened to 1.8% from 1.0%, entirely because of unprocessed food, which accelerated to 5.5% from 3.8%. This pushed inflation in the 'shopping basket' of food and everyday household and personal-care products to 1.7% from 0.9%. By contrast, processed food prices were still slightly lower than a year earlier. Services inflation edged up more moderately, to 2.6% from 2.4%, with firmer recreational, personal-care and transport services. For the time being, the services domain, more directly affected by wage costs, is not showing evidence of emerging second-round effects.
The composition is less alarming than the headline suggests, but not entirely benign
Core inflation excluding energy and fresh food rose only modestly, to 1.7% from 1.5%, and inflation excluding energy stood at 2.0%. The September spike therefore looks mainly like a fresh energy shock rather than a broad-based resurgence in domestic price pressures. Even so, the rise in high-frequency purchases to 5.3% will make the inflation rebound particularly visible to households and could weigh on real purchasing power.
Istat’s acquired inflation rate for 2026 now stands at 3.1% for the headline index, while remaining at 1.9% for core inflation. Taking into account that more increases will follow protected energy bills starting from October, headline inflation will likely remain above the 4% mark over the last quarter of 2026, pushing average 2026 inflation to 3%, our new base case.
Comments
Log in or sign up to join the conversation.