
Lots and lots to cover today. Let’s see how far I get before I go into the national debt discussion.
Kevin Warsh and the FOMC did what was expected and stood pat. That won’t be the case in December when rates will go up again. And guess what? The stock market didn’t crater another 1% during his presser. Progress.
Q3 GDP printed +3.4%. That is very solid growth on the heels of +2%+ for Q1 and Q2. Corporate earnings are at record highs. Corporate profit margins are at record highs. Poverty is at record lows. Homeowner equity is at 60-year highs. Bulls will point to accelerating momentum. I am a bit skeptical for now. I think growth may slow shortly. I hear from folks all the time about inflation, and I remain firm that it’s not the issue. 3.5% is the long-term average. The problem is that prices are still going up, and that won’t change until the next recession hits.
The midterms are coming up, and I doubt we will know the outcome until a few days later. My crude model still says the House goes blue by 30-40 while the Senate is now a toss-up. Affordability remains the driving issue among voters, and the GOP promised relief during the last campaign. Campaign taglines are easy to create, but hard to deliver. Midterms almost always see the party in power lose significant seats. Memory says 1998 and 2002 were the only midterm years that bucked the trend in the modern era. Absent the 5% chance that the GOP retains control of the House, the elections should be a non-event for the markets.
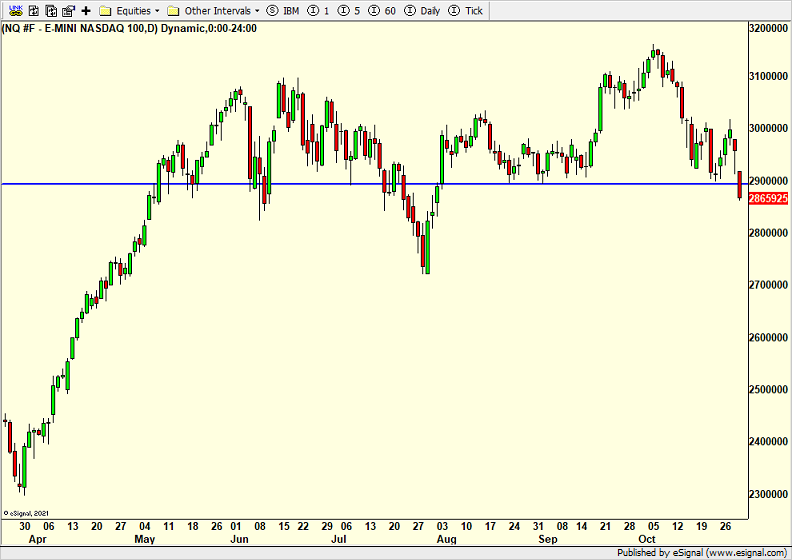
Speaking of the markets, they are under pressure, with the Nasdaq 100 leading the way lower after its recent all-time high. Google (GOOGL) disappointed. Intel (INTC) laid an egg. Amazon (AMZN) missed sharply. Marvel (MRVL) was poor. Lots of portfolio changes, mostly reducing risk and exposure, as you can see at the end.
Judging by pre-market, it will be down roughly 12% since its October 6 high. It has also entered the area where I have long looked for a bottom, sub-29,000. Unless today sees its worst at the open, which I doubt, the stock market should be poised for its Q4 bottom next week and run to new highs into January. Of course, I could be wrong, and this decline ends up deeper and cancels the one I see coming early next year. If that’s the case, 2027 should end up being a big up year. I am putting the cart before the horse. Let’s see what happens.
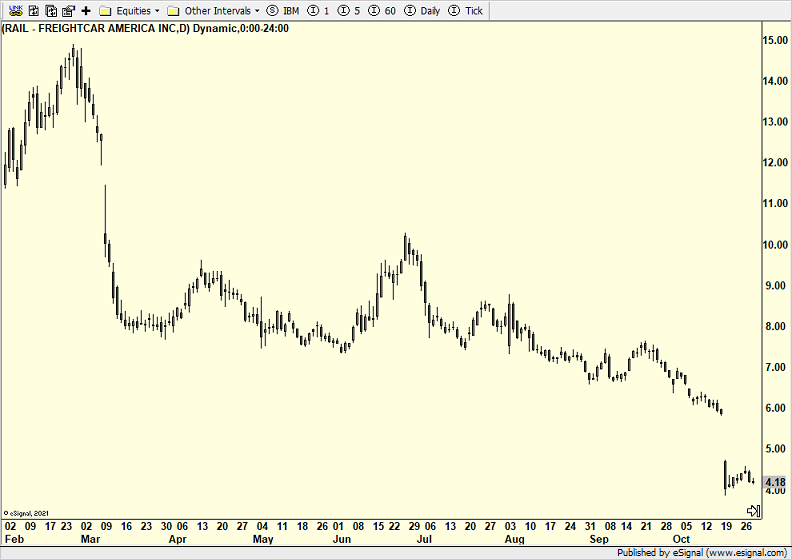
Someone asked about the big mistakes in our Unloved Gems portfolio. I laughed. While success stories in Moderna (MRNA) make up for a lot of mistakes, they don’t eliminate them. Here are two mistakes, but in different ways. RAIL is below. We have sold it a few times, and we bought it back over the summer. It’s been ugly and now susceptible to tax-loss selling. Thankfully, our position size is small.
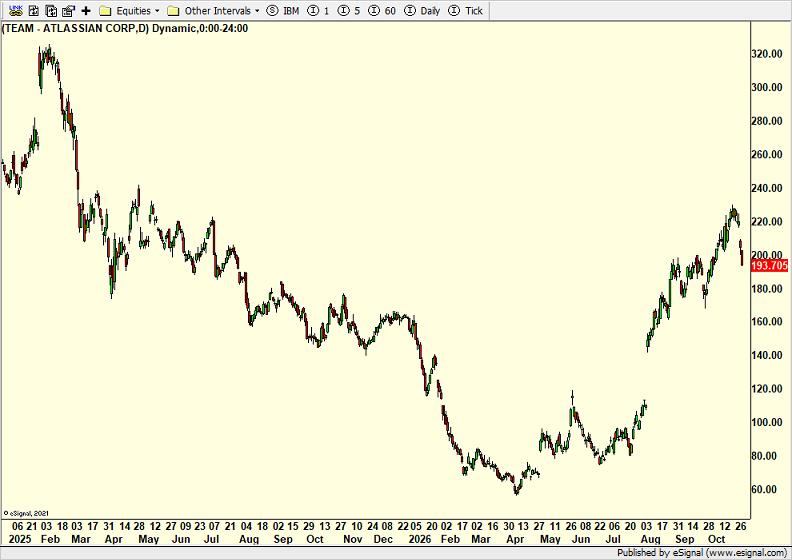
On the flip side, we owned Atlassian (TEAM) for years and rode it down during the software apocalypse. When it bounced during the summer, we sold it because we needed funds elsewhere. And then it jumped from $110 without us.
I am going to save the debt and answer more of your questions until next week. My wife and I planned to be celebrating our 25th anniversary on a beach right now, but work got in the way, so I will be strapped in to my chair all next week with the markets.
Another beautiful fall weekend is here. Hoping for a round of golf, pizza outside tonight with friends, and football. It’s only our second weekend with the nest empty, so we’ll see how that goes. I am sure I will be in the office for at least half a day.
On Wednesday we sold some RSPU, some QLD, and some MQQQ. On Thursday we bought VGK, more QLD, and more MQQQ. We sold SPY, PMPIX, MANH, DWAS, some RYRSX, some SPHB, some PDBC, some XBI, some IYR, and some XAR.
Comments
Log in or sign up to join the conversation.