
Global equity markets continued their march toward record highs as investors shrugged off elevated oil prices, multi-decade highs in sovereign bond yields, and deepening political risk across Europe. A megacap technology rally propelled the Nasdaq 100 to a fresh all-time high, while strong momentum in Nvidia and Microsoft left the S&P 500 within striking distance of its peak. AI-linked earnings growth continues to overpower broader macro discomfort, providing an effective floor for risk appetite.
Asia-Pacific benchmarks followed Wall Street’s lead with more measured gains, lifting the MSCI Asia-Pacific Index 0.1% while the MSCI All Country World Index traded within 1.5% of its August high. European and US equity futures signalled further upside despite structural duration headwinds. In fixed income, the US 10-year Treasury yield rose 1 bp to 5.32%—holding near levels last seen in 2002—while the 2-year yield climbed 2 bps to 4.83%. Higher yields spilt globally: government bonds across Japan, Australia, and New Zealand weakened, with 10-year JGB yields topping 3.0%—a landmark shift marking the end of Japan as an automatic anchor for low global yields.
Energy and safe-haven assets reflected ongoing macro friction. Brent crude edged up 0.6% to $100.90/bbl, remaining high enough to feed inflation expectations and keep central bank rate-cut bets contained. Spot Gold dipped 0.4% to $4,120/oz, caught between structural reserve-diversification bids and the immediate drag of elevated real yields. In FX markets, the Euro hovered near a 17-month low, burdened by soft relative growth, persistent US yield differentials, and mounting fiscal angst in Paris.
France remains a primary focal point for European sovereign risk. Investors are scrutinizing alternative budget proposals from Marine Le Pen’s party aimed at deficit reduction, with the Bank of France’s Governor Moulin warning that the country faces being "strangled by interest rates." Long-end spread compensation suggests markets are pricing in fiscal convergence between France and Italy by roughly 2036—a far faster pace than implied by IMF baseline projections (2042–2046). This creates an asymmetric risk profile: while additional political friction could widen spreads further, any credible fiscal compromise could trigger a sharp relief rally in French paper.
In the US, a stark divergence between Wall Street and Main Street is reshaping the political landscape ahead of the November midterm elections. Despite third-quarter GDP tracking at an annualized 3.7% on the Atlanta Fed’s GDPNow model, consumer confidence remains depressed due to high mortgage rates, elevated fuel prices, and stretched affordability. RealClearPolitics polling places President Trump’s approval rating at a new low of -22.1%, with betting markets pointing toward a higher probability of a split Congress.
Looking to the session ahead, the macroeconomic calendar features UK and German construction PMIs, the US trade balance, German factory orders, and French industrial production. Central bank commentary from Bank of Japan Governor Ueda and the Fed’s John Williams will also be parsed for signals on policy normalisation and the reaction function following recent employment data.
Macro to Micro: Financial markets are navigating a clear divide. On one side, megacap tech earnings and robust US nominal output are driving equity benchmarks toward record territory. On the other, 10-year Treasuries at 5.32%, Brent crude above $100/bbl, and widening European sovereign spreads signal a tight financial environment. For traders, the key focus remains on whether narrow AI leadership can continue to insulate broad equity indices as long-end yields test multi-decade highs.
Overnight Headlines
Ray Dalio Warns China And Japan May Pull Back From US Treasuries
US Treasury Issues Notice To Foreign Banks Doing Business With Iran
NY Fed Questions Major Banks On Risk Management, Collateral
Japan 10-Year Bond Sale Demand Stronger Than 12-Month Average
Australia’s Consumer Confidence Tumbles Further After Rate Hike
Asia’s Buffers Too Thin To Keep Absorbing Oil Shock, World Bank Says
Germany, France Propose Measures To Counter Flood Of Chinese Goods
Wall Str Banks Launch Record $60B Chip Deal For Broadcom, Anthropic
OpenAI In Talks With UAE Funds And BlackRock For $30B Round
Google And Constellation Near Billion-Dollar Nuclear Power Deal
BMW Makes €2B Bet, As Domestic Rivals Cut Capacity, Jobs
Petronas CEO Warns Of LNG ‘Bloodbath’ Risks As Prices Surge
Yemen Says It’s Retaken Mocha As Battle For Bab El-Mandeb Looms
CFTC Proposes Registering Crypto Exchanges Offering Leverage
FX Options Expiries For 10am New York Cut
(1BLN+ represents larger expiries and is more magnetic when trading within the daily ATR.)
EUR/USD: 1.2500 (EU2.02b), 1.1550 (EU1.34b), 1.1860 (EU1.22b)
USD/JPY: 156.00 ($3.05b), 154.00 ($1.77b), 150.00 ($1.59b)
AUD/USD: 0.7000 (AUD510m), 0.6990 (AUD310.2m)
USD/CAD: 1.4100 ($451.1m), 1.4075 ($325.4m)
GBP/USD: 1.3340 (GBP533.9m)
USD/MXN: 18.45 ($304.6m)
EUR/GBP: 0.8660 (EU441m)
USD/BRL: 5.3000 ($308.9m), 5.4750 ($306m)
USD/KRW: 1355.85 ($310m)
CFTC Positions as of 1/10/26
Bitcoin net long position is 2,465 contracts
Swiss franc posts net short position of -24,617 contracts
British pound net short position is -91,075 contracts
Euro net short position is -63,256 contracts
Japanese yen net long position is 55,440 contracts
Speculators increase CBOT US 5-year Treasury futures net short position by 114,848 contracts to 995,701
Speculators increase CBOT US 10-year Treasury futures net short position by 88,863 contracts to 900,615
Speculators trim CBOT US 2-year Treasury futures net short position by 115,041 contracts to 792,024
Speculators trim CBOT US UltraBond Treasury futures net short position by 10,289 contracts to 326,436
Speculators increase CBOT US Treasury bonds futures net short position by 31,070 contracts to 186,875
Equity fund managers cut S&P 500 CME net long position by 33,658 contracts to 901,255
Equity fund speculators increase S&P 500 CME net short position by 575 contracts to 355,697
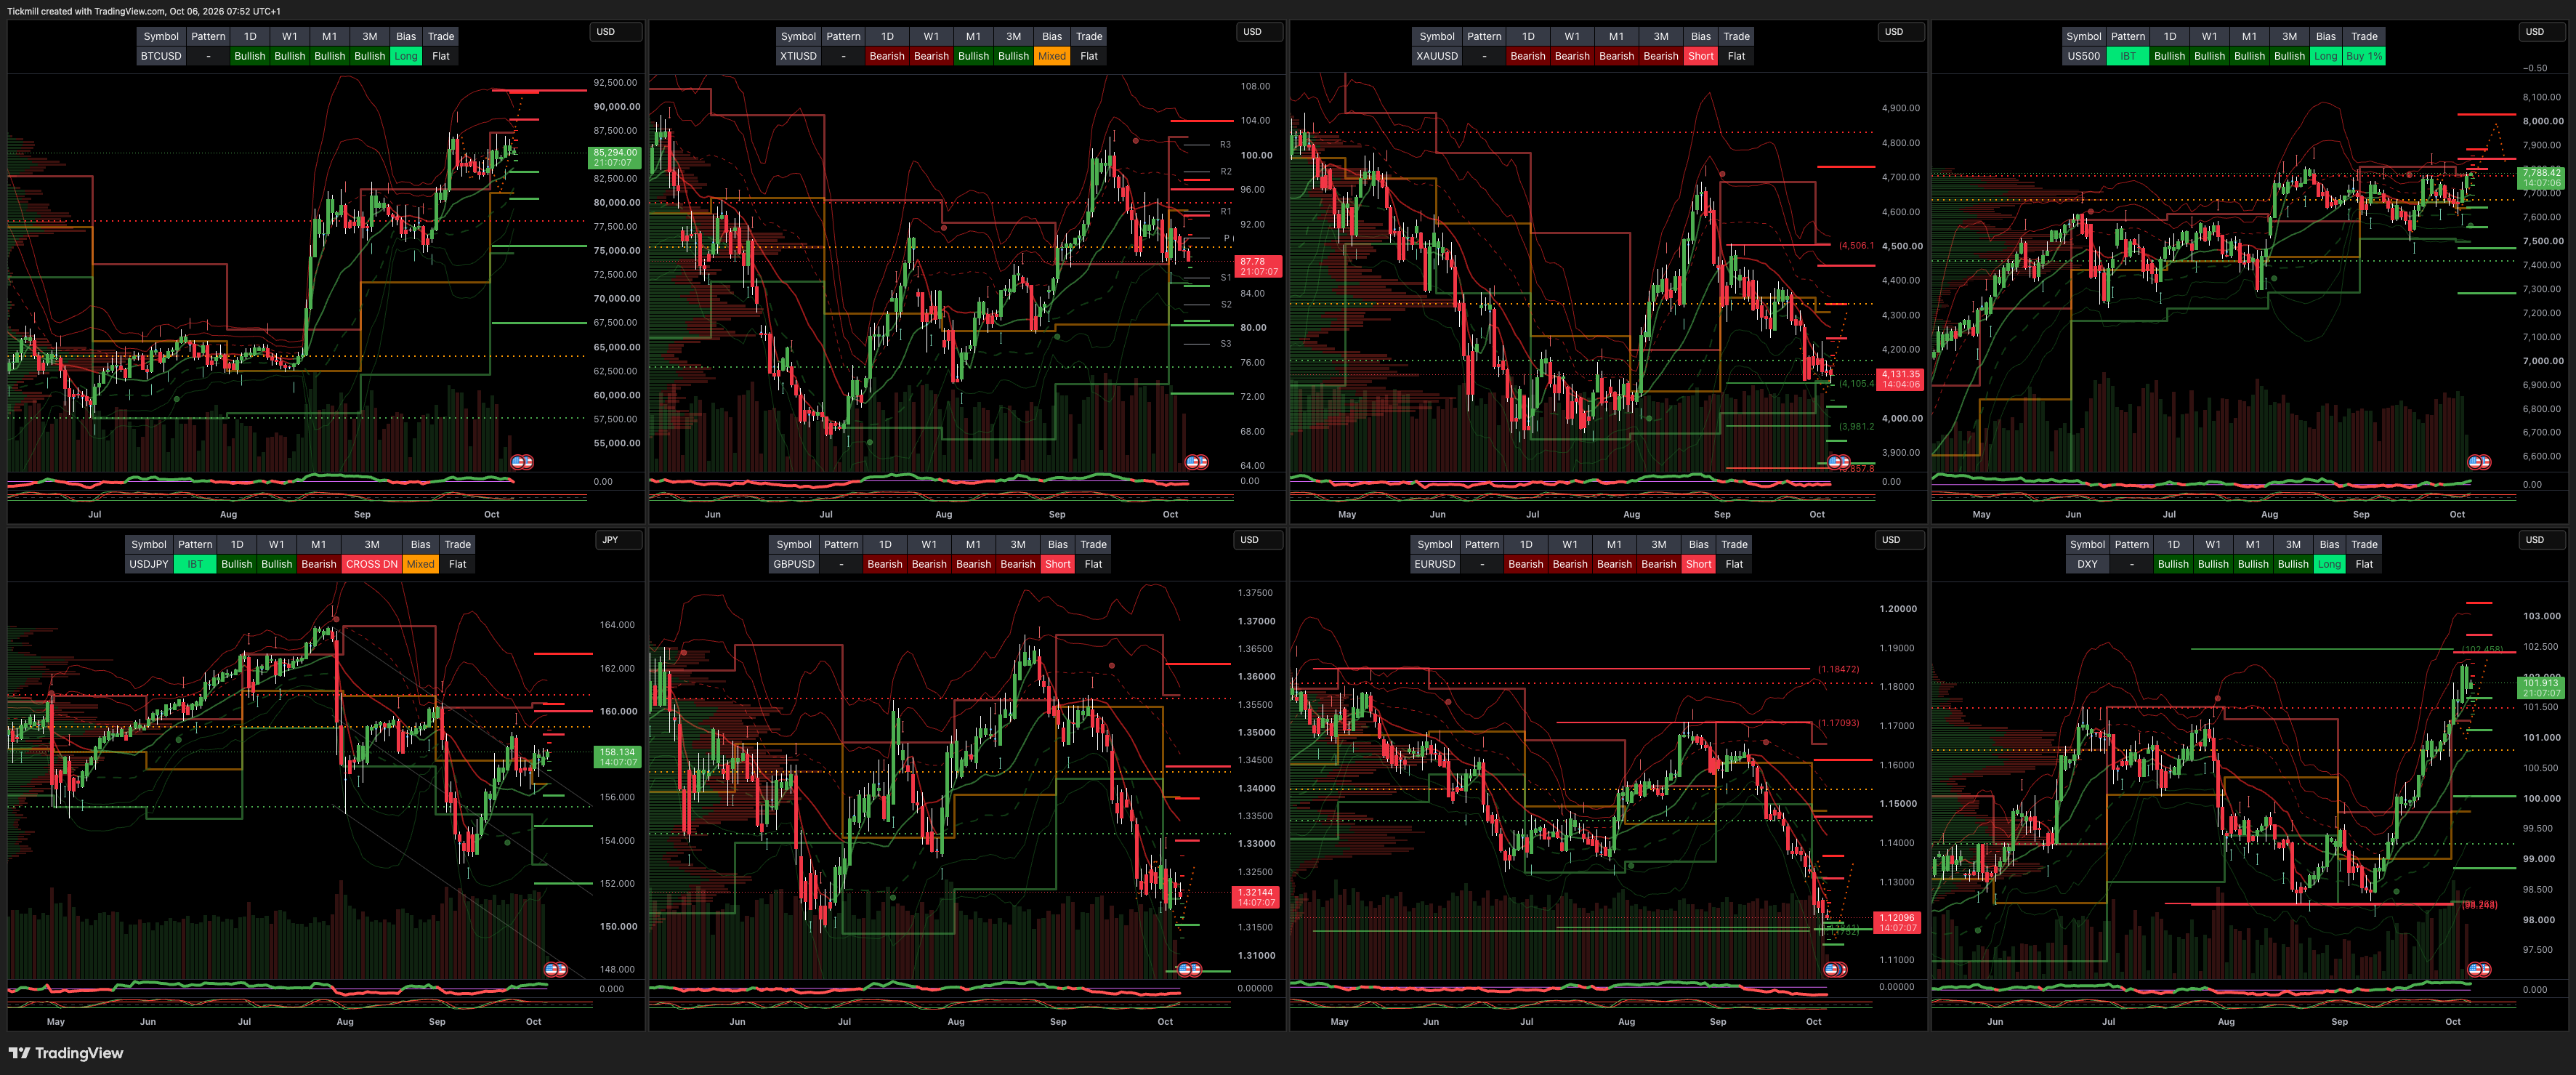
Technical & Trade Views
Comments
Log in or sign up to join the conversation.